


RHI Magnesita (LSE:RHIM) Stock May Trade At A Discount As Bid Talks Extend
RHI Magnesita has delivered a 35.6% return over the past year, which naturally raises a pointed question for anyone looking at the stock today. Is the current share price, at a last close of £26.90, adequately grounded in the earnings the business is producing right now.
- A 35.6% gain over 12 months puts meaningful expectation into the price and invites a closer look at how much of that move is supported by profit generation rather than sentiment.
- The possible offer for Vesuvius, with anti trust conditions and disposal thresholds attached, may reshape future earnings power and the timing of cash flows that underpin what you are willing to pay for each pound of profit.
- The analysts covering RHI Magnesita have run their own numbers. See what analysts think RHI Magnesita's shares could be worth.
The stock's next move may depend on whether the current valuation can be squared with what the business is earning today and is realistically expected to earn over time.
If you want to compare RHI Magnesita with other opportunities based on earnings power, you can use a focused screen of 14 high quality undervalued stocks.
Is RHI Magnesita Still Cheap on Earnings?
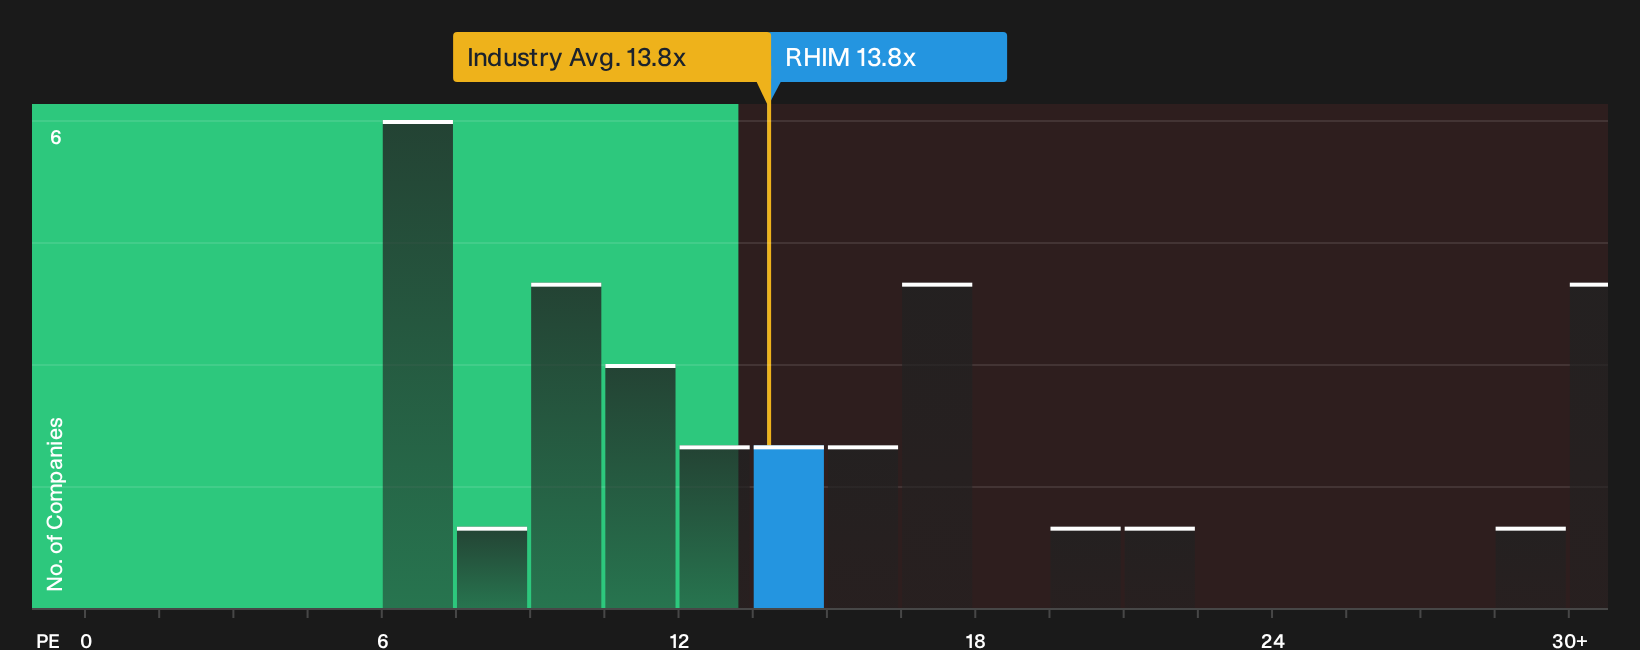
The P/E ratio works reasonably well for RHI Magnesita because earnings are a key reference point for how investors weigh a materials supplier with steady demand drivers. On this measure, the stock trades on about 13.8x earnings, compared with roughly 14.2x for the wider Basic Materials group and about 17.0x across closer peers, so the market is paying a lower price for each euro of current profit than it is for similar businesses.
The fair multiple implied by a more tailored model that factors in RHI Magnesita's size, risk profile and industry economics sits above where the shares trade today, so on this framework the P/E screens as undervalued rather than stretched. Because the possible offer for Vesuvius has introduced a live corporate event into the story, that discount persists despite deal speculation that often pushes valuations higher. If you want to see how far the current P/E is from that modelled reference point, and how it compares against other Basic Materials stocks, you can check the fuller breakdown in. Explore the numbers behind RHI Magnesita's P/E valuation.
The RHI Magnesita Narrative: What Would Justify Today's Price?
RHI Magnesita's valuation puzzle only really comes into focus once you spell out the future it implies. Simply Wall St Narratives do that by mapping out which earnings, margin and growth paths would need to play out for the share price to look meaningfully cheap or expensive, and by setting out the assumptions behind each fair value view so you can compare them with the actual results reported over time on the Community page.
The community is essentially split on RHI Magnesita, with one camp focusing on cost savings and recycling upside while the other fixates on project delays and raw material swings.
Bull case: 20% undervalued
"The current valuation implies that the share price does not fully reflect the improvement in adjusted EBITA margin, progress on cost savings and debt reduction targets..."
Discover why this Narrative puts RHI Magnesita at 20% undervalued.
Bear case: 17% overvalued
"The numbers imply that RHI Magnesita’s current share price already reflects successful delivery of structural margin improvement, recovery in industrial projects and disciplined leverage reduction..."
Explore why this Narrative puts RHI Magnesita at 17% overvalued.
One more RHI Magnesita check that belongs beside the earnings multiples
Price and profit only tell part of the story. Internal checks have also flagged specific concerns about RHI Magnesita that many investors will want to weigh before drawing any conclusions. Take a closer look at 3 warning signs (1 major) before settling on a valuation.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com