


Lumen Technologies (LUMN) Launches AI Network Tools On A Cheap Stock Or Fair Warning
Lumen Technologies (LUMN) just put its network resilience story in the spotlight, rolling out new AI-driven service assurance tools alongside Dual Path, a wavelength service built around physically diverse routes.
These AI tools arrive at a time when Lumen Technologies’ share price has been under pressure, with the stock up 6.78% over the past week but showing a 30 day share price return of down 15.13% and a year to date share price return of down 36.54%, while the 1 year total shareholder return is down 52.53% and the 3 year total shareholder return is very large. Taken together, these figures point to long term holders still sitting on gains even as shorter term momentum has been fading.
Scan how Lumen Technologies compares with other infrastructure plays by checking which companies make the cut in our 54 AI infrastructure stocks list right now.
Lumen Technologies has a fresh product story and a share price that has fallen hard over the year, then bounced this week. Is that an early reward for patience or a reason to wait for a clearer entry?
Most Popular Narrative: 35% Undervalued
Lumen Technologies is trading at $4.88 against a widely followed fair value estimate of $7.49, so the market price sits well below what that framework implies for the business today.
The modernization program targeting US$700m run rate cost savings exiting 2026 and US$1b by 2027, including ERP consolidation, product retirements and future copper exits that can reduce the US$200m to US$300m of annual CapEx tied to legacy networks, is intended to lift EBITDA and free cash flow over time.
See why 62 investors see Lumen Technologies as 35% undervalued.
Result: Fair Value of $7.49 (UNDERVALUED)
Still, the narrative around Lumen Technologies can break if legacy service declines keep outpacing higher margin offerings, or if heavy CapEx and cost cuts do not translate into stronger cash generation.
Find out about the key risks to this Lumen Technologies narrative.
Another View: SWS DCF Says Lumen Is Ahead Of Itself
The analyst fair value story paints Lumen Technologies as 35% undervalued at $7.49. A different lens tells a cooler story. The SWS DCF model points to a fair value of $4.16, which sits below the current $4.88 share price and frames Lumen as overvalued on future cash flows. That gap raises a simple question: Which set of assumptions do you trust more, the earnings path or the cash flow path?
Our DCF model packs in those cash flow assumptions in full, so you can see exactly where the tension with the analyst target comes from. Look into how the SWS DCF model arrives at its fair value.
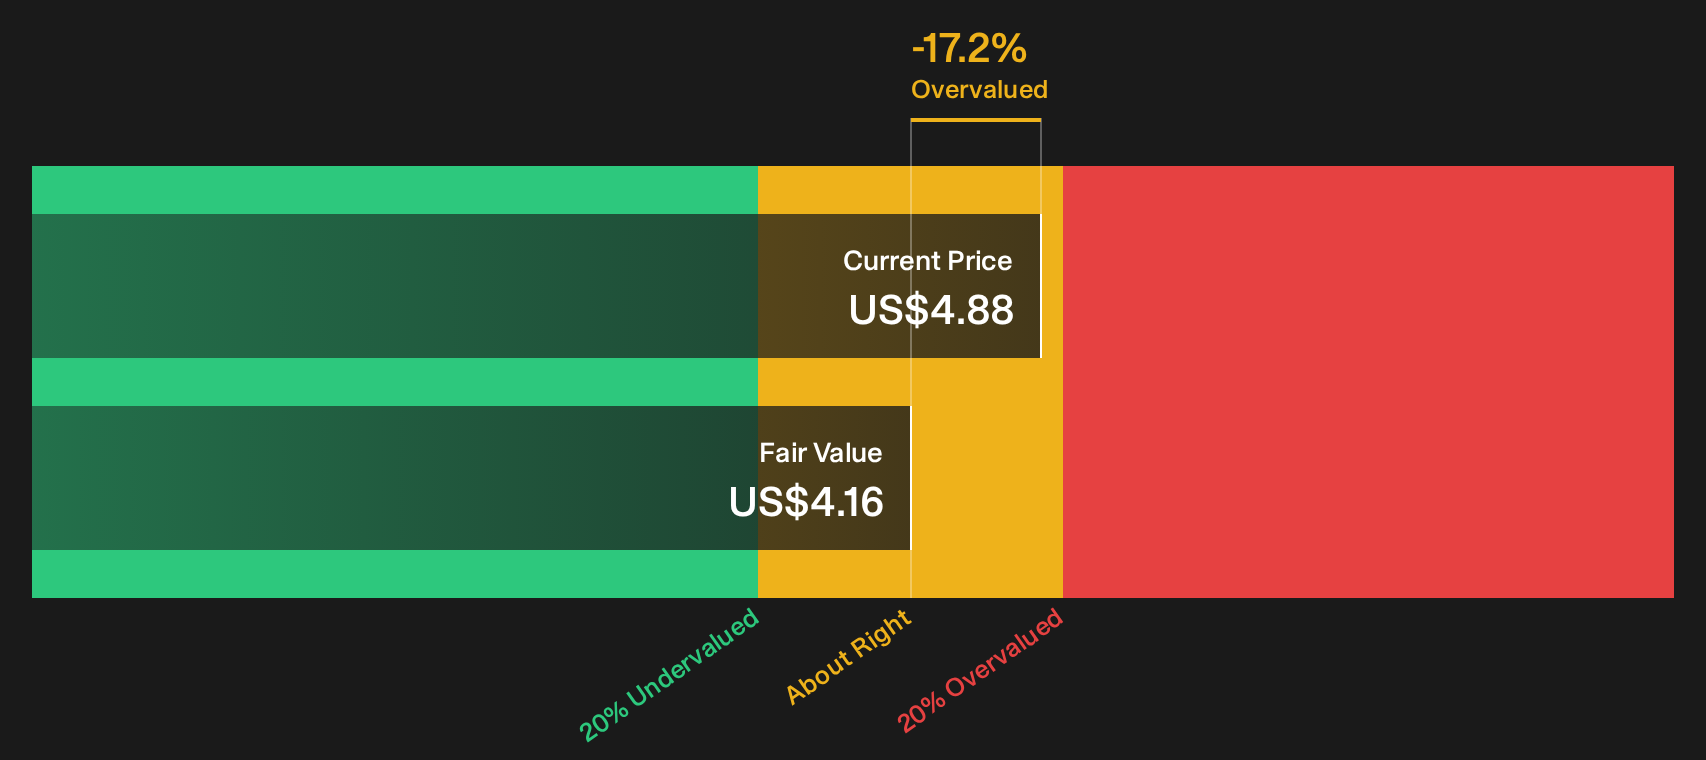
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Lumen Technologies for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 33 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals or an early inflection for Lumen Technologies. Either way, move quickly and stress test the story against the data on 2 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Lumen Technologies?
If Lumen Technologies has your attention, do not stop here. Broader context across other opportunities can sharpen your judgement and help you position with more confidence.
- Target resilient compounding potential by focusing on businesses with durable earnings profiles and low volatility using our 29 resilient stocks with low risk scores.
- Hunt for mispriced opportunities where quality and valuation line up cleanly by scanning the 33 high quality undervalued stocks.
- Prioritise balance sheet strength so short term shocks do not derail your thesis with the list of solid balance sheet and fundamentals (24 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com