


Genky DrugStores (TSE:9267) Q1 Results Reflect A Profit Margin Squeeze
Genky DrugStores came into this Q1 2027 print with a market narrative built on steady earnings compounding and a valuation roughly in line with peers. The stock closed at ¥3,395 on the day of the release, after a choppy few months that left the 90 day return down about 8.6%. The fresh quarter shows revenue of ¥59,503m but net income of ¥1,878m, which points to the real story this time. Profit pressure, not sales, is where expectations and reality part ways.
Love the steady top line at Genky DrugStores but concerned that profit pressure is doing the damage this quarter? You can screen for retailers with sturdier earnings power using our list of solid balance sheet and fundamentals stocks (21 results)
Q1 2027 Earnings Summary
- Revenue (Q1 2027 vs Q1 2026): ¥59,503m vs. ¥54,630.5m (up about 8.9%)
- Net Income (Excl. Extra Items, Q1 2027 vs Q1 2026): ¥1,878m vs. ¥2,010m (down about 6.6%)
- Basic EPS (Q1 2027 vs Q1 2026): ¥61.55 vs. ¥66.05 (down about 6.8%)
- Trailing 12-Month Net Income (Excl. Extra Items, Q1 2027 vs Q1 2026): ¥7,716m vs. ¥7,519m (up about 2.6%)
Prefer clean charts over staring at raw earnings tables and margin lines for Genky DrugStores? Get a full visual read on the business with an at a glance look at its financials and how they fit together in the company report for Genky DrugStores.
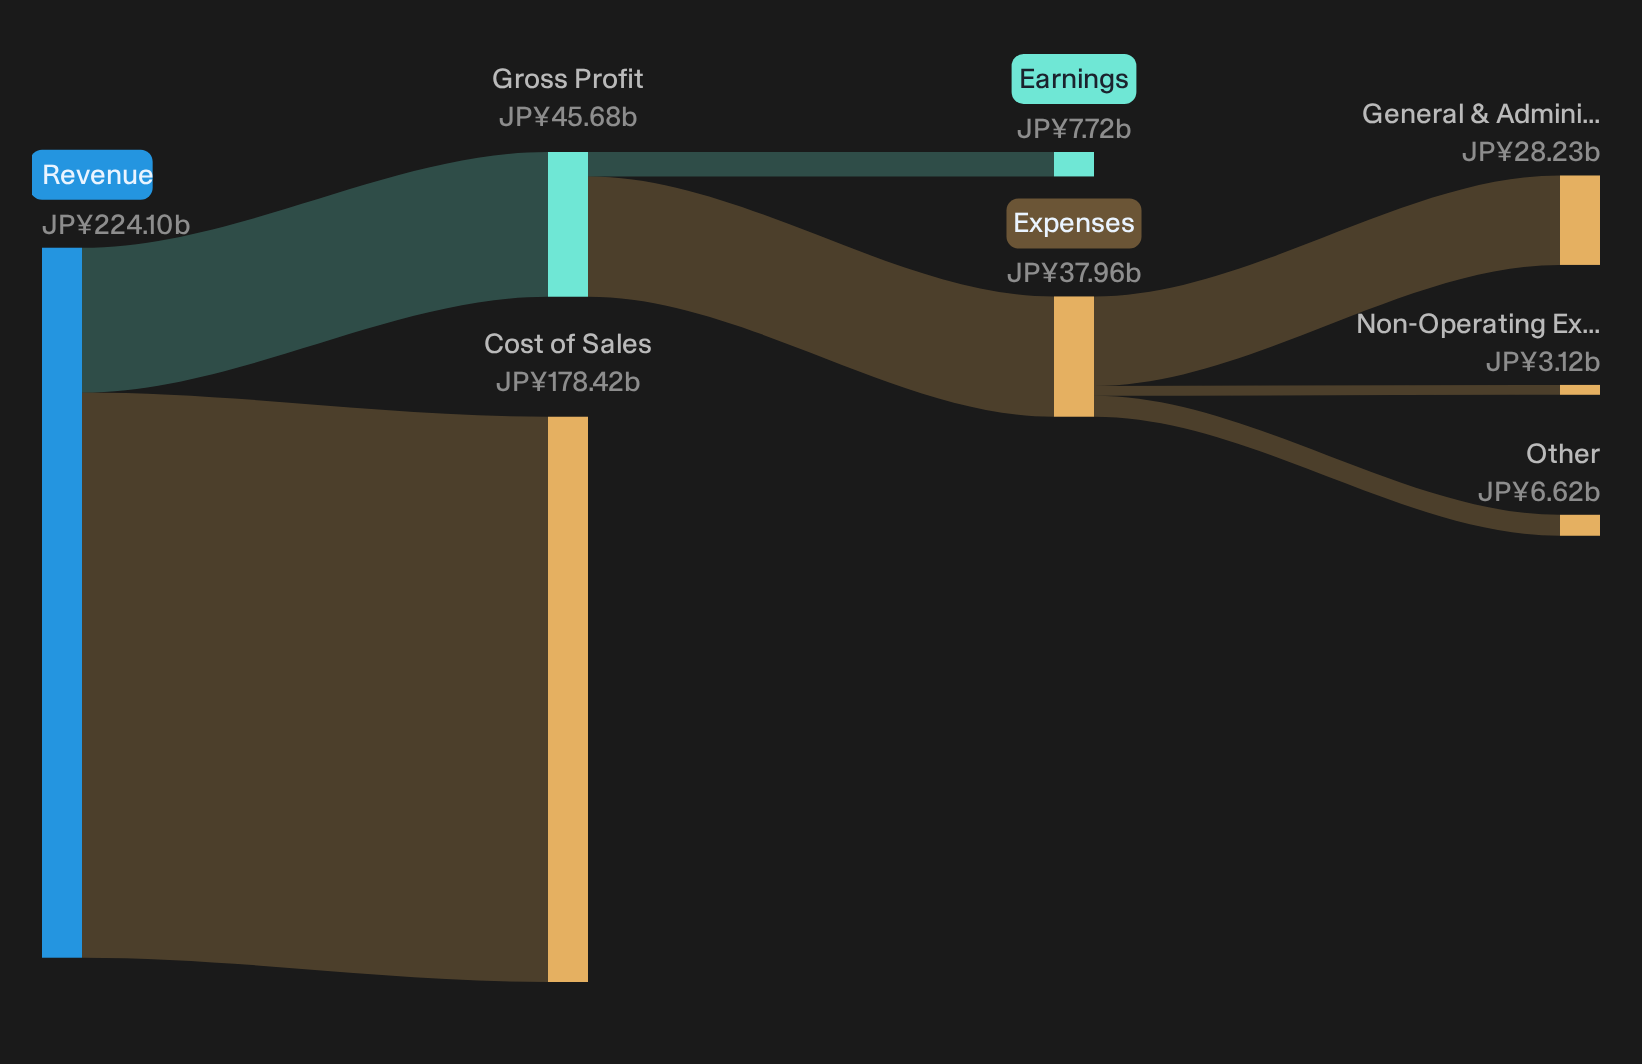
Genky DrugStores and the Resilient Bullish Angle
For anyone leaning positive on Genky DrugStores, the appeal is that everyday spending still shows up in the top line. Revenue sits at ¥59,503m, above the prior year period, which fits the idea of steady demand for food and drug items. Trailing 12 month net income excluding extras of ¥7,716m is also above the prior comparable figure, so profitability over a longer window still tracks upwards even if not by a huge amount.
Margin Squeeze Concerns and the Bearish Read
Bearish arguments around margin pressure find firmer footing in this quarter. Net income excluding extra items slipped from ¥2,010m to ¥1,878m and basic EPS moved from ¥66.05 to ¥61.55. That is consistent with a backdrop where discounts, promotions, or cost inflation are having an impact. The share price performance adds weight, with the 90 day return down about 8.6%, which suggests investors have already been uneasy about earnings quality, not just sales momentum.
Are analysts backing the idea that Genky DrugStores still has a resilient earnings story despite this margin squeeze, or turning cautious instead? Check the consensus price target analysis for Genky DrugStores.Hunt For Mispriced Earnings Power
Genky DrugStores shows how solid sales can coincide with profit pressure and uneasy share price moves. The real opportunity could be finding stocks that appear mispriced before expectations reset.
- Company 1 - 37% below our estimate - designs and maintains complex air and water systems that critical facilities rely on to stay operational.
- Company 2 - 36% below our estimate - wins long duration build and reinforcement projects as infrastructure owners upgrade aging transport and public facilities.
- Company 3 - 45% below our estimate - expands fee based lending and deposit services for smaller businesses that traditional banks sometimes underserve.
Three companies from the same screener. Open the full list of 16 companies trading below our fair value estimates →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com