


Is Raised 2026 Guidance Altering The Investment Case For SPX Technologies Stock (SPXC)?
- SPX Technologies reported third quarter 2026 sales of US$714.5 million and net income of US$81.9 million, alongside higher earnings per share and updated 2026 revenue guidance of US$2.745 billion to US$2.805 billion.
- A key driver was HVAC, where data center demand and the recent FIS Water acquisition are shaping how SPX Technologies allocates capital and manages capacity expansion.
- We will now look at how SPX Technologies' raised 2026 revenue outlook could reshape the broader investment narrative around its HVAC platform.
Scan how SPX Technologies compares with other HVAC and data center beneficiaries by reviewing our curated list of 41 power grid technology and infrastructure stocks in one place.
SPX Technologies Investment Narrative Recap
To own SPX Technologies, you need to believe the HVAC platform can keep turning data center demand, FIS Water integration, and new capacity into resilient cash flows, even as Detection & Measurement remains more project dependent. The raised 2026 revenue outlook leans in that direction, since it is rooted in already visible orders and current operating momentum.
The near term swing factor is execution on HVAC volume ramp and margin stabilisation while Section 232 tariff costs and growth related inefficiencies run through the system. The biggest risk still sits in project timing and backlog rebuild in Detection & Measurement, which the latest results do not fully resolve.
The clearest announcement tied to this story is the updated 2026 revenue guidance to US$2.745b to US$2.805b, which implies roughly 23% year on year growth at the midpoint. That revision is grounded in strong Q3 HVAC trends, higher data center exposure, and contributions from FIS Water rather than a purely financial reframe.
For you as a shareholder, that raised range sharpens the near term catalyst. Progress on data center HVAC, capacity utilisation at sites like Olathe and Springfield, and integration of recent HVAC acquisitions all contribute to whether SPX Technologies can sustain its current earnings base while absorbing tariff headwinds and possible Detection & Measurement lumpiness.
SPX Technologies' current analyst narrative points to revenues of about US$3.7b and earnings of US$509.6 million by 2029. That profile assumes roughly 14.6% yearly revenue growth and an earnings increase of about US$224.6 million from US$285.0 million today.
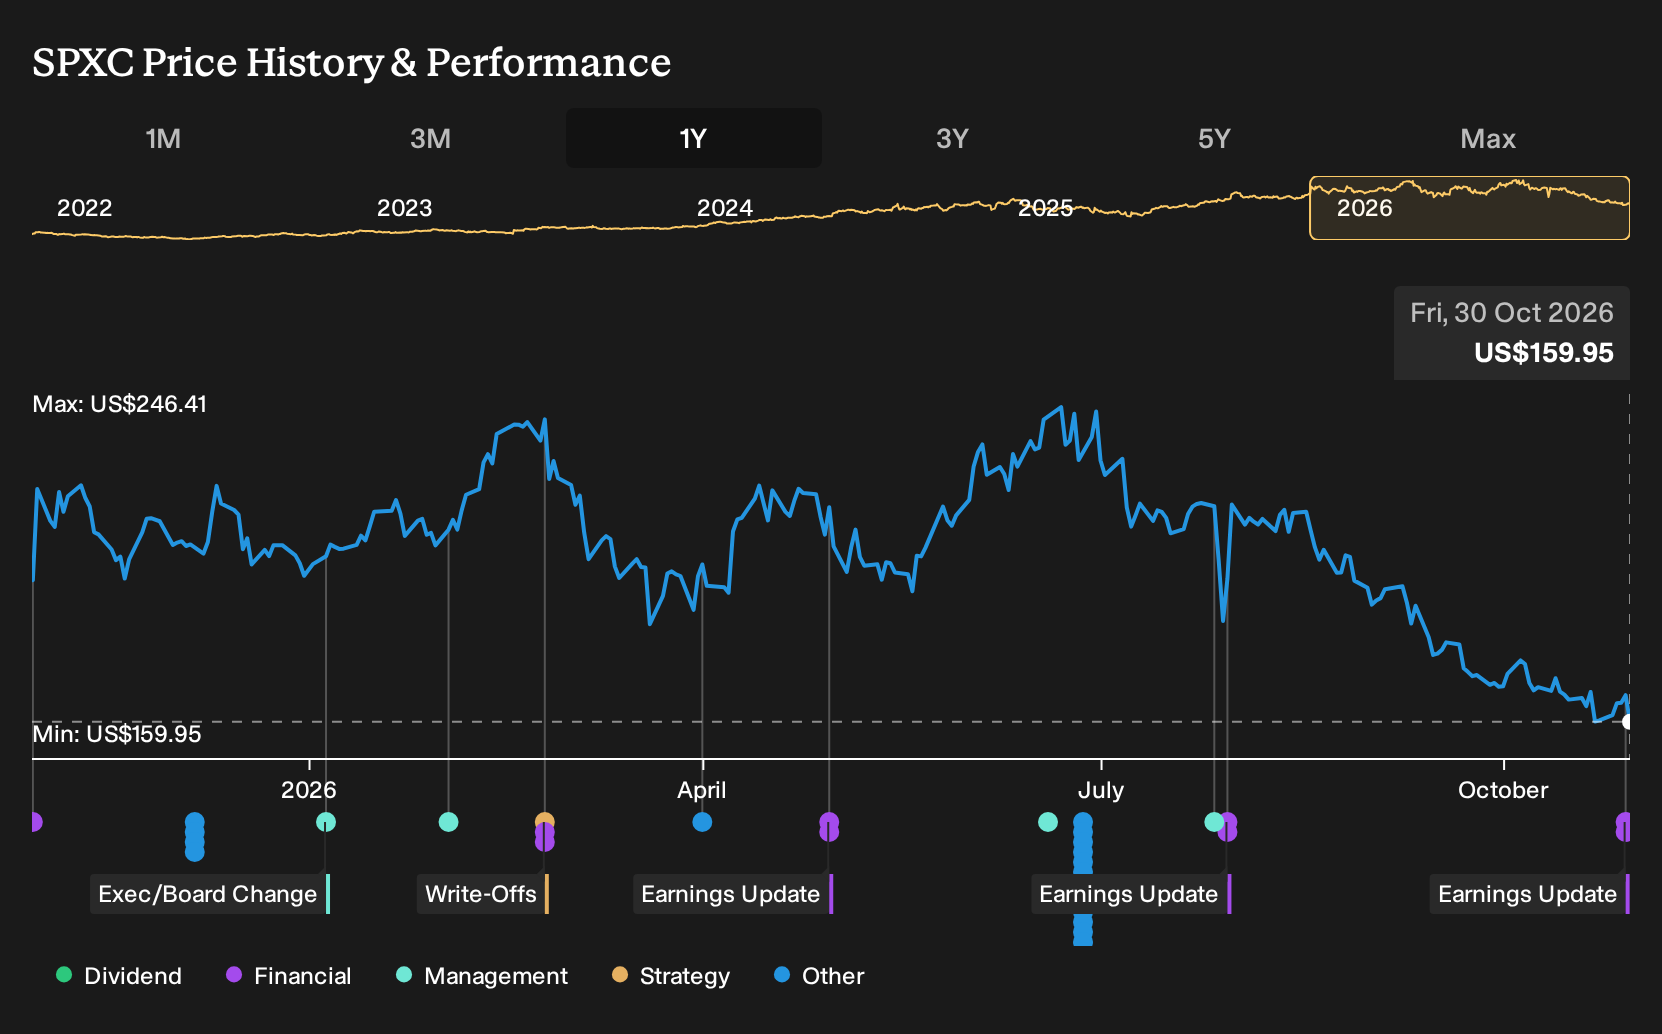
Uncover why SPX Technologies' fair value points to a 58% potential upside to its current price, which could narrow quickly as expectations catch up.
Exploring Other Perspectives
Across three fair value estimates from the Simply Wall St Community, SPX Technologies is pegged between about US$200.55 and US$252.79, with opinions spreading across that full band. Those views were set before the latest Q3 beat and raised 2026 guidance. You are weighing them against fresher risks around Detection & Measurement project timing and Section 232 tariff costs that could still influence how the story plays out. Investor opinions clearly differ, so use these community inputs as a springboard to explore several alternative viewpoints before deciding how SPX Technologies fits your portfolio.
Explore 2 other SPX Technologies fair value estimates, including one that suggests it could be worth just $200.55!
Decide For Yourself
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your SPX Technologies research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for SPX Technologies. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate SPX Technologies' overall financial health at a glance.
Looking For More Investment Ideas Beyond SPX Technologies?
Once you have a view on SPX Technologies, it can help to broaden your watchlist with companies that offer different risk and return profiles, all filtered through the same Simply Wall St framework.
- If you want income and resilience to play a bigger role in your portfolio, consider screening for 5 dividend fortresses that can anchor your returns with regular payouts.
- For investors who care most about balance sheet strength and business quality, filter the market using our list of solid balance sheet and fundamentals (24 results) to see which companies clear a higher financial bar.
- If you prefer to look where fewer people are paying attention, scan our 19 high quality undiscovered gems and see which under followed stocks still show strong underlying fundamentals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com