


Digital Turbine Stock In Focus After Earnings Delay and Financial Statement Review
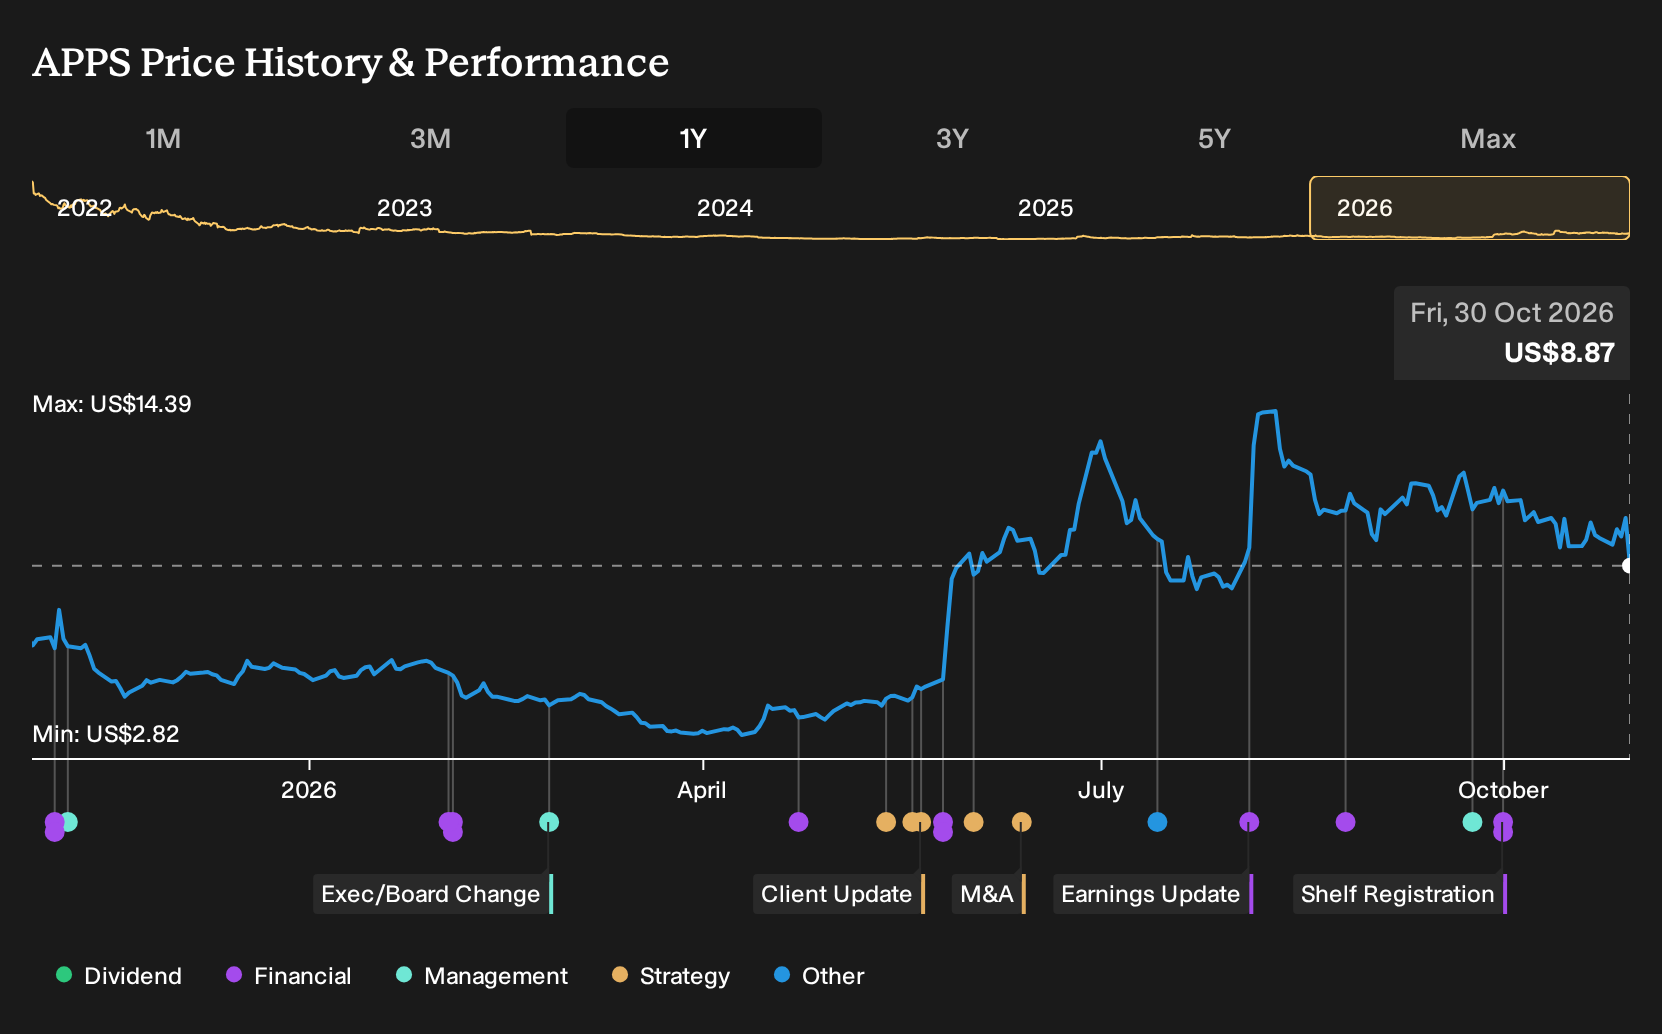
- Digital Turbine postponed its fiscal 2027 second quarter earnings release and conference call from November 2 to November 9, 2026 to finish reviewing and finalizing its unaudited financial statements, following an earlier correction that widened a prior GAAP net loss.
- The extra review time signals real pressure on Digital Turbine’s reporting controls and accounting processes, which directly affects how confidently investors can interpret current losses, future profitability targets and any long term margin ambitions built into existing forecasts.
- We will examine how Digital Turbine’s earnings delay and financial statement review pressures relate to the existing long term investment narrative.
Balance the accounting uncertainty around Digital Turbine by scanning hand picked alternatives through the 29 resilient stocks with low risk scores. These options feature cleaner financial profiles and lower reported risk scores.
Digital Turbine Investment Narrative Recap
To own Digital Turbine, you need to believe its on-device software and app growth platform can turn a larger installed base and carrier ties into a more durable, higher-quality revenue mix over time. The immediate question is whether the current operating model can eventually support consistent profitability, given the business still reports losses.
The delayed second-quarter update and the prior widening of the GAAP net loss put short-term focus squarely on reporting quality and expense discipline. That matters for the next catalyst. The upcoming November 9 release is mainly about confirming underlying demand trends and cost control. The biggest near-term risk is that accounting issues distract from fixing operations.
The rescheduled fiscal 2027 second-quarter release is the key announcement to watch. A clean set of unaudited financials would help you assess whether the smartphone penetration and advertiser demand themes are translating into healthier contribution from On Device Solutions and the App Growth Platform, or whether profitability timelines are stretching further out.
Digital Turbine also enters this print with a share price that has been volatile and a history of deep losses, despite revenue of about US$600.3m and a reported net loss of US$35.0m. That context makes execution on carrier and OEM partnerships, ad tech capabilities and cost structure crucial catalysts. Any signs of slippage here could matter more than short-term stock moves.
Digital Turbine's current narrative assumes revenue rising to US$842.3 million and earnings reaching US$14.9 million by 2029. That path lines up with a 12.0% yearly revenue growth rate and a swing in earnings of about US$49.9 million, from a loss of US$35.0 million today to the projected profit level.
Uncover why Digital Turbine's fair value indicates a 94% potential upside to its current price, which could close far quicker than many investors expect.
Exploring Other Perspectives
For a different angle on Digital Turbine, focus on the Orange rollout as a possible upside swing factor. The most optimistic analysts were pencilling in revenue of about US$902.6m and earnings of US$131.5m by 2029 before this delay. Those projections now sit exposed. Your view on the earnings review could shift that story meaningfully.
Explore 4 other Digital Turbine fair value estimates, including one that suggests as much as 159% upside from the current price!
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Digital Turbine research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Digital Turbine. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Digital Turbine's overall financial health at a glance.
Looking For More Investment Ideas Beyond Digital Turbine?
If the Digital Turbine story has sharpened your view on risk, cash flows and earnings quality, it can be useful to line it up against other opportunities that fit very different checklists. The Simply Wall St Screener lets you filter for traits that matter most to you, whether that is balance sheet strength, income potential or mispriced quality.
- If capital preservation is high on your list, start with a basket of companies that score well on resilience and financial strength by checking out 29 resilient stocks with low risk scores.
- For investors who want income potential alongside fundamental support, scan for stocks offering robust yield profiles and solid business metrics through 5 dividend fortresses.
- If you are hunting for quality that is not yet crowded, focus on under-the-radar businesses with strong fundamentals using 19 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com