


China PMI Weakness Puts Powell Industries Stock And Onshoring Plays In Focus
Factory data out of China just slipped back into contraction, which can rattle investors who remember how quickly supply chains used to clog up or clear out. That weakness in Chinese manufacturing and exports is also nudging production decisions closer to home, and some onshoring beneficiaries are already in the spotlight. This article walks through three stocks linked to that story and how this latest PMI print could matter for your portfolio decisions.
The three stocks that follow are only a small sample of this onshoring theme, and the full screen on Simply Wall St surfaced another 30 companies with equally compelling relocation and capacity expansion stories that are not covered below. To identify your own highest conviction ideas in this trend, head straight into the Developed-Market Industrial & Manufacturing Onshoring Beneficiaries screener.
Powell Industries (POWL)
Powell Industries builds custom electrical power systems that sit behind new factories, data centers, and energy facilities. This positions the company squarely in the onshoring theme as manufacturers add or expand plants closer to end demand.
Powell generates essentially all of its roughly US$1.16b revenue from electric equipment. This reflects a focused product mix in power control rooms, switchgear, and related services. The stock carries a market value of about US$5.7b.
For onshoring investors, Powell Industries matters because it supplies the electrical backbone for localized industrial capacity. Recent expansion moves have sharpened that story without removing all the uncertainty.
"There is significant optimism that Powell's acquisition of Remsdaq and expansion into the electrical automation and SCADA markets will quickly and materially accelerate both revenue and margin growth, while integration risks and the lengthy sales cycles for new offerings could temper near-term financial impact."
What happens to Powell's earnings power if a single assumption about future project economics and customer spending patterns quietly shifts?
If that quiet shift is what you care about, read the full narrative for Powell Industries to see how onshoring, pricing power and integration risk really intersect.

Proto Labs (PRLB)
Proto Labs is a digital manufacturer that helps U.S. and European customers keep production closer to home, using online ordering and automated factories to turn designs into physical parts quickly for low volume runs and rapid prototyping, and the stock is valued at about US$1.64b.
As Western manufacturers rethink long supply chains out of China, Proto Labs gives engineers and supply teams a way to source critical parts locally and on short timelines, which is exactly the kind of capability many reshoring projects now depend on.
"Continued expansion of Proto Labs’ CNC Machining and Injection Molding work into higher requirement production programs for aerospace and defense customers, including rockets, satellites, drones, and space exploration, can add more recurring revenue and support gross margin resilience as these projects move beyond one off prototyping into multi year programs."
What happens to Proto Labs’ earnings power if a single assumption about how quickly customers shift from small jobs to longer production runs proves too optimistic?
If that shift in customer behavior is what you are weighing, read the full narrative for Proto Labs to learn how Proto Labs’ onshoring role could affect its earnings power.

Ferrotec (TSE:6890)
Ferrotec supplies critical parts and services for semiconductor equipment and electronic components, which ties it directly to onshoring and capacity expansion in developed markets. The group earns ¥261.9b from semiconductor equipment related operations, ¥83.7b from electronic devices, ¥36.3b from automotive activities and ¥20.6b from other lines, and the stock is valued at about ¥413.0b.
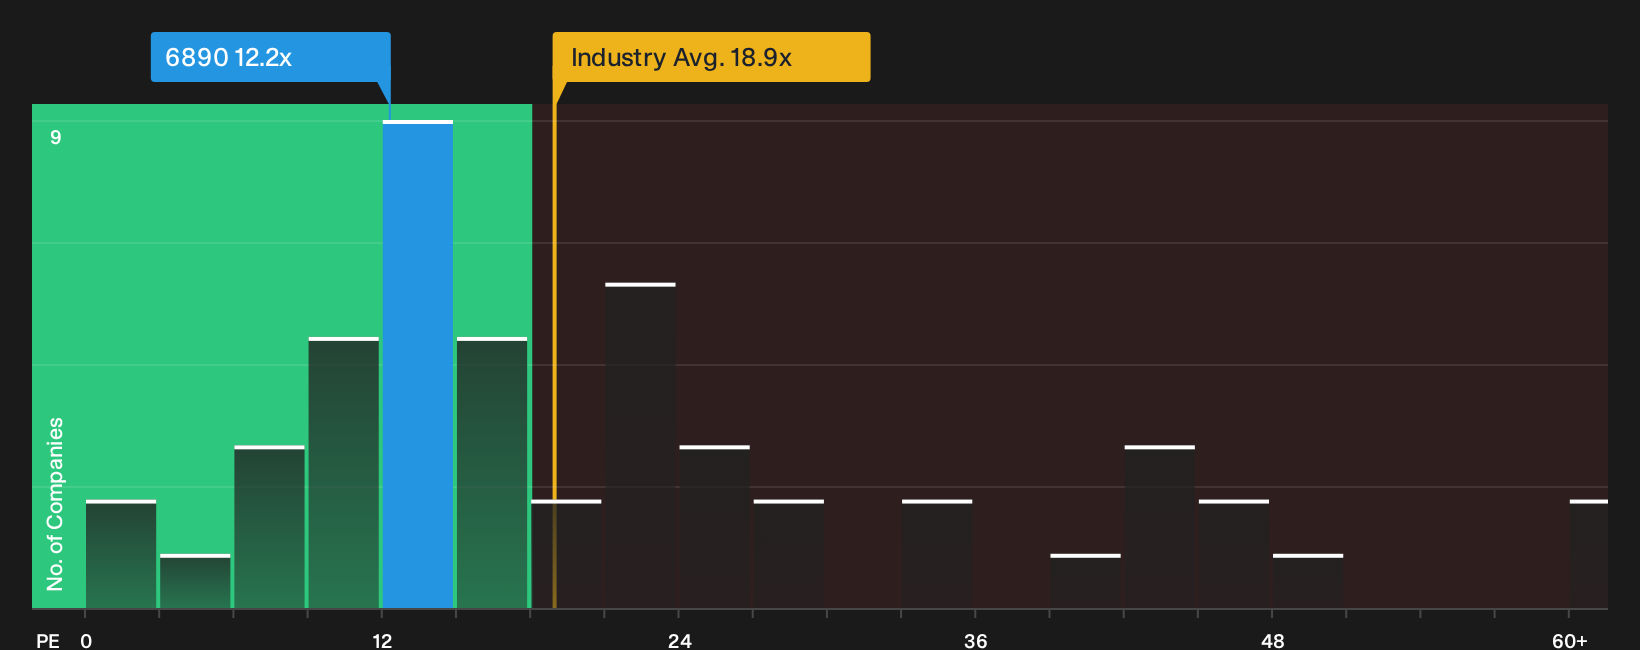
Ferrotec provides exposure to semiconductor and advanced manufacturing projects that are gradually shifting closer to end markets as supply chains diversify away from China. The P/E of 12.2x currently sits below both the Japanese market and many chip peers, which may make the onshoring angle especially noteworthy for investors who are focused on capacity spending trends.
That valuation gap raises a simple question about what the market might be missing on onshoring risk and upside, so go straight to the analysis report for Ferrotec for the full picture investors are debating.
Seeking Alternatives Before Momentum Flies
Fresh themes can move quickly, and the best breakout ideas are often picked up by early movers while they are still under the radar. Consider acting promptly if you identify an opportunity that fits your approach.
- Spot cash-generative opportunities early and review the 30 high quality undervalued stocks before stronger momentum potentially moves these fundamentals-driven ideas beyond your preferred price range.
- Focus on durable income and review the 5 dividend fortresses while yields remain elevated and prices may not yet fully reflect that payout strength.
- Monitor future-facing infrastructure and scan the 54 AI infrastructure stocks while capital is still rotating into the space and some potential leaders may still be priced as afterthoughts.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com