


Is ONEOK (OKE) Undervalued As Strong Q3 Results And Higher 2026 Outlook Lift Sentiment?
ONEOK (OKE) grabbed fresh attention after its third quarter report on 27 October 2026, as higher revenue, earnings and a raised 2026 profit outlook sharpened debate around the stock.
ONEOK’s latest earnings update landed against a backdrop of strong market interest, with the share price at US$97.07 and a 30.58% year to date share price return that has outpaced many peers. The 10.46% 1 month share price return and 10.01% 3 month share price return suggest momentum has been building into and after the third quarter release, while a 52.75% 1 year total shareholder return points to gains that go well beyond the recent move.
Extend that ONEOK lens across the sector and compare this earnings-fueled momentum with a curated list of peers in the midstream and energy space using our 30 high quality undervalued stocks.
ONEOK now combines a sizeable US midstream footprint with a share price that has already risen significantly on upgraded numbers. The real puzzle is whether that strong business is still on offer at a sensible valuation today.
Most Popular Narrative: 4% Undervalued
ONEOK is framed as modestly undervalued in the most widely followed narrative, with a fair value of $101.50 against the latest close of $97.07. That gap might not look huge on paper, but the reasoning behind it leans heavily on how the midstream footprint, tax profile and capital structure interact over time.
Extension of ONEOK’s cash tax runway out to 2031 and the self amortizing Class B interest from Apollo, which caps the investor’s IRR at 7% and gradually shifts more cash flow back to common shareholders, together support higher future free cash flow conversion and net income relative to adjusted EBITDA.
See why 81 investors see ONEOK as 4% undervalued.
Result: Fair Value of $101.50 (UNDERVALUED)
Still, pressure on NGL margins from a higher ethane mix and softer earnings from the Natural Gas Pipelines segment could quickly cool this ONEOK optimism.
Find out about the key risks to this ONEOK narrative.
Another View: ONEOK Through The P/E Lens
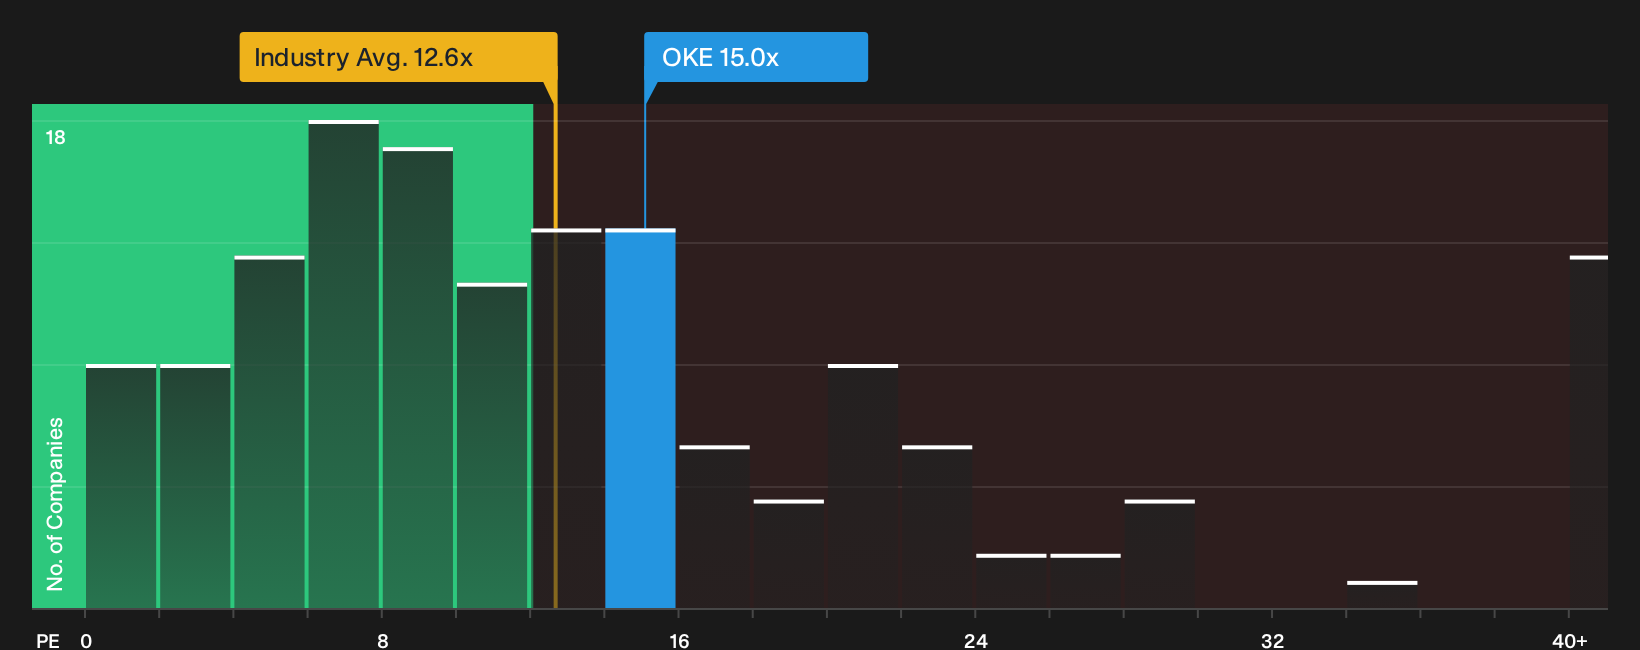
ONEOK might look inexpensive on cash flow models, yet its P/E of 15x presents a more cautious perspective. The ratio sits above the US Oil and Gas industry at 12.6x, but below both its peer average of 19.5x and a fair ratio estimate of 19x. Is that a margin of safety, or a signal that expectations are already rich enough?
To see how the numbers compare with this earnings-based view, take a closer look at the See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed signals around ONEOK’s value case and risk profile are exactly why the next move needs to be yours, not the market’s mood. Weigh the possible upside against the potential downsides by reviewing the 3 key rewards and 2 important warning signs
Looking for more investment ideas beyond ONEOK?
If ONEOK has sharpened your thinking, do not stop there. Broaden your watchlist now so you are not relying on a single opportunity.
- Target stronger income potential by scanning companies that feature 5 dividend fortresses for investors who want yield backed by robust fundamentals.
- Zero in on sturdier balance sheets through a list of solid balance sheet and fundamentals (24 results) that can help you focus on financially resilient businesses.
- Hunt for overlooked opportunities with the 19 high quality undiscovered gems that may sit off the usual radar but still show solid financial quality.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com