


Does Extended Credit Lines Change The Bull Case For New Jersey Resources Stock?
- New Jersey Resources and key unregulated subsidiaries amended their senior unsecured revolving credit facility, increasing total commitments from US$575 million to US$650 million and extending the maturity to October 27, 2031.
- The parallel extension of New Jersey Natural Gas Company's US$250 million facility to October 27, 2031 highlights an emphasis on long-duration liquidity to support its regulated capital program and related infrastructure spending.
- This article will examine how New Jersey Resources' investment narrative aligns with the expanded revolving credit capacity and longer-dated funding.
Scan other utilities and infrastructure players with extended funding runways using our curated list of 29 resilient stocks with low risk scores, which may offer similar balance sheet resilience to New Jersey Resources.
New Jersey Resources Investment Narrative Recap
To own New Jersey Resources, you need to be comfortable with a utility-led model that leans on regulated gas distribution and long-duration capital spending, while still carrying exposure to gas market policy shifts and project execution. The larger US$650 million credit facility and extended maturities support liquidity for that plan, but do not change the basic thesis.
The more important short-term swing factor remains delivery on the US$4.8b to US$5.2b 2026 to 2030 investment program, including recovery of about US$950 million of past spend and managing customer bill affordability. Key risks stay tied to thin free cash flow dividend cover, debt that is not well supported by operating cash flow, and policy pressure on natural gas demand.
The most relevant recent announcement is the multi-year capital framework that directs more than 60% of spending to New Jersey Natural Gas, alongside the filing that seeks to recover roughly US$950 million of infrastructure outlay while proposing an 8.9% cut to typical winter bills. That plan frames how New Jersey Resources wants to grow regulated earnings and still keep pricing competitive for customers.
Set against that backdrop, the extended US$650 million and US$250 million revolving facilities look like plumbing for this capex and rate case agenda rather than a new growth engine. For you as a shareholder, the focus probably sits on whether those projects move into the rate base as expected, Storage & Transportation delivers on planned contracts, and Clean Energy Ventures shifts from early-stage losses toward the earnings contribution analysts are modeling.
New Jersey Resources Forecasts Behind The Credit Extension
New Jersey Resources' forecast profile that sits behind the extended credit lines is relatively measured. Analysts are working with a 1.7% annual revenue growth rate over the next three years, a lift in profit margins from 16.4% today to 17.3% by 2029, and a move in earnings from US$366.2 million today to US$405.5 million by 2029. That implies an earnings increase of about US$39 million against current levels, with the 2029 view also pointing to revenues of US$2.3b and a consensus earnings outcome of US$405.5 million in that same year.
New Jersey Resources' narrative projects US$2.3b revenue and US$405.5 million earnings by 2029. This rests on 1.7% yearly revenue growth and an earnings increase of about US$39 million from US$366.2 million today.
Uncover why New Jersey Resources' fair value indicates a 12% potential upside to its current price that could narrow quickly.
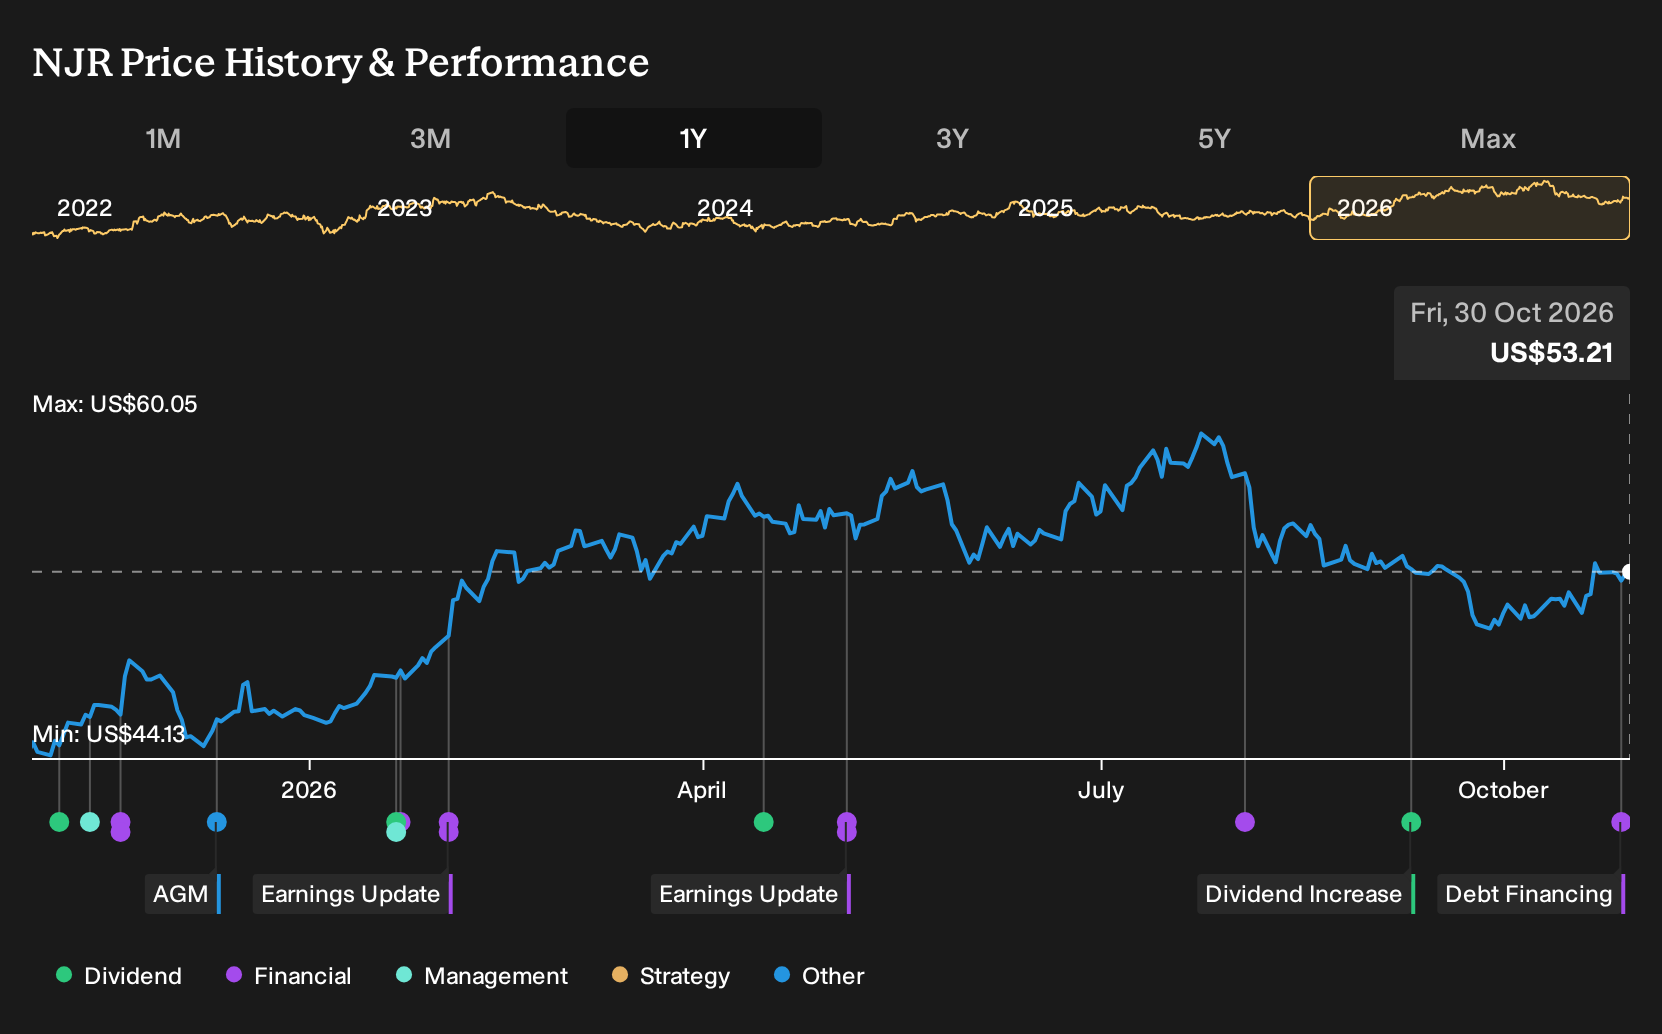
Exploring Other Perspectives
Two fair value estimates from the Simply Wall St Community span a wide band, from about US$13.07 to almost US$59.86 per share, which shows how far apart retail opinions on New Jersey Resources can be. When you also consider policy risk around gas usage and the extended credit lines, you can see how investors might arrive at very different narratives about the company’s future performance.
Explore another New Jersey Resources fair value estimate, including one that suggests there may be up to 12% upside from the current price.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your independent research and judgment.
- A great starting point for your New Jersey Resources research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for New Jersey Resources. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate New Jersey Resources' overall financial health at a glance.
Looking for more investment ideas beyond New Jersey Resources?
Once you understand how New Jersey Resources fits your portfolio, it can help to scan a wider field of candidates that align with your risk tolerance and income goals. The Simply Wall St Screener makes that easier by filtering the market into focused shortlists tailored to different objectives.
- If you care most about resilience and capital preservation, you can start with a basket of relatively steady businesses through the 29 resilient stocks with low risk scores.
- Income focused investors who want yield backed by fundamentals can use the 5 dividend fortresses to identify payout candidates with stronger profiles.
- For those looking for potential mispriced opportunities supported by robust underlying metrics, the 31 high quality undervalued stocks can highlight ideas that may warrant a closer look.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com