


Are Stronger Earnings Altering The Investment Case For Stifel Financial Stock (SF)?
- Stifel Financial reported third quarter 2026 revenue of US$1,635.17 million and net income of US$234.14 million, with basic earnings per share from continuing operations of US$1.48 and diluted earnings per share of US$1.40.
- For the first nine months of 2026, Stifel Financial produced US$4,939.6 million in revenue and US$712.04 million in net income, highlighting how earnings from continuing operations per share compare with the same period last year.
- We will now explore how Stifel Financial's higher year to date earnings may influence its investment narrative for long term holders.
Scan how Stifel Financial's earnings story compares with other financially solid opportunities by running through the hand picked list of solid balance sheet and fundamentals (24 results) in the same sector and beyond.
Stifel Financial Investment Narrative Recap
To own Stifel Financial, you need to be comfortable with a broker led wealth and capital markets model, where adviser recruitment, client assets and banking ties drive the story. The latest results show revenue and earnings in the quarter and year to date broadly in line with that narrative. The key near term swing factor remains execution on adviser productivity and client asset gathering.
The biggest business risk stays in the background, not in this report. Legal exposures, funding mix quality and any strain on capital from loan growth or venture banking expansion could still weigh on profitability. The new earnings numbers do not materially change that risk profile.
The most relevant update here is the nine month 2026 performance. Stifel Financial reported US$4,939.6 million of revenue and US$712.04 million of net income for the period, with basic earnings per share from continuing operations at US$4.45 and diluted at US$4.23. That provides a clearer view of how the franchise is converting its adviser, wealth and institutional efforts into profit.
For catalysts, those nine month earnings sit on top of existing drivers such as adviser hiring, AI tools and the venture and fund banking buildout. Stronger profitability gives management more room to support planned loan growth up to US$4b in 2026 if credit discipline holds. It also matters for absorbing any future legal costs or funding related pressures.
Stifel Financial's current earnings of US$939.1 million are set against analyst expectations for US$1.3b of profit by 2029, based on an assumed 2.0% yearly revenue growth rate and a forecast revenue line of US$6.2b in that same year. This implies an earnings increase of about US$360 million from today if those estimates play out.
Uncover why Stifel Financial's fair value indicates a 25% potential upside to its current price that could narrow quickly.
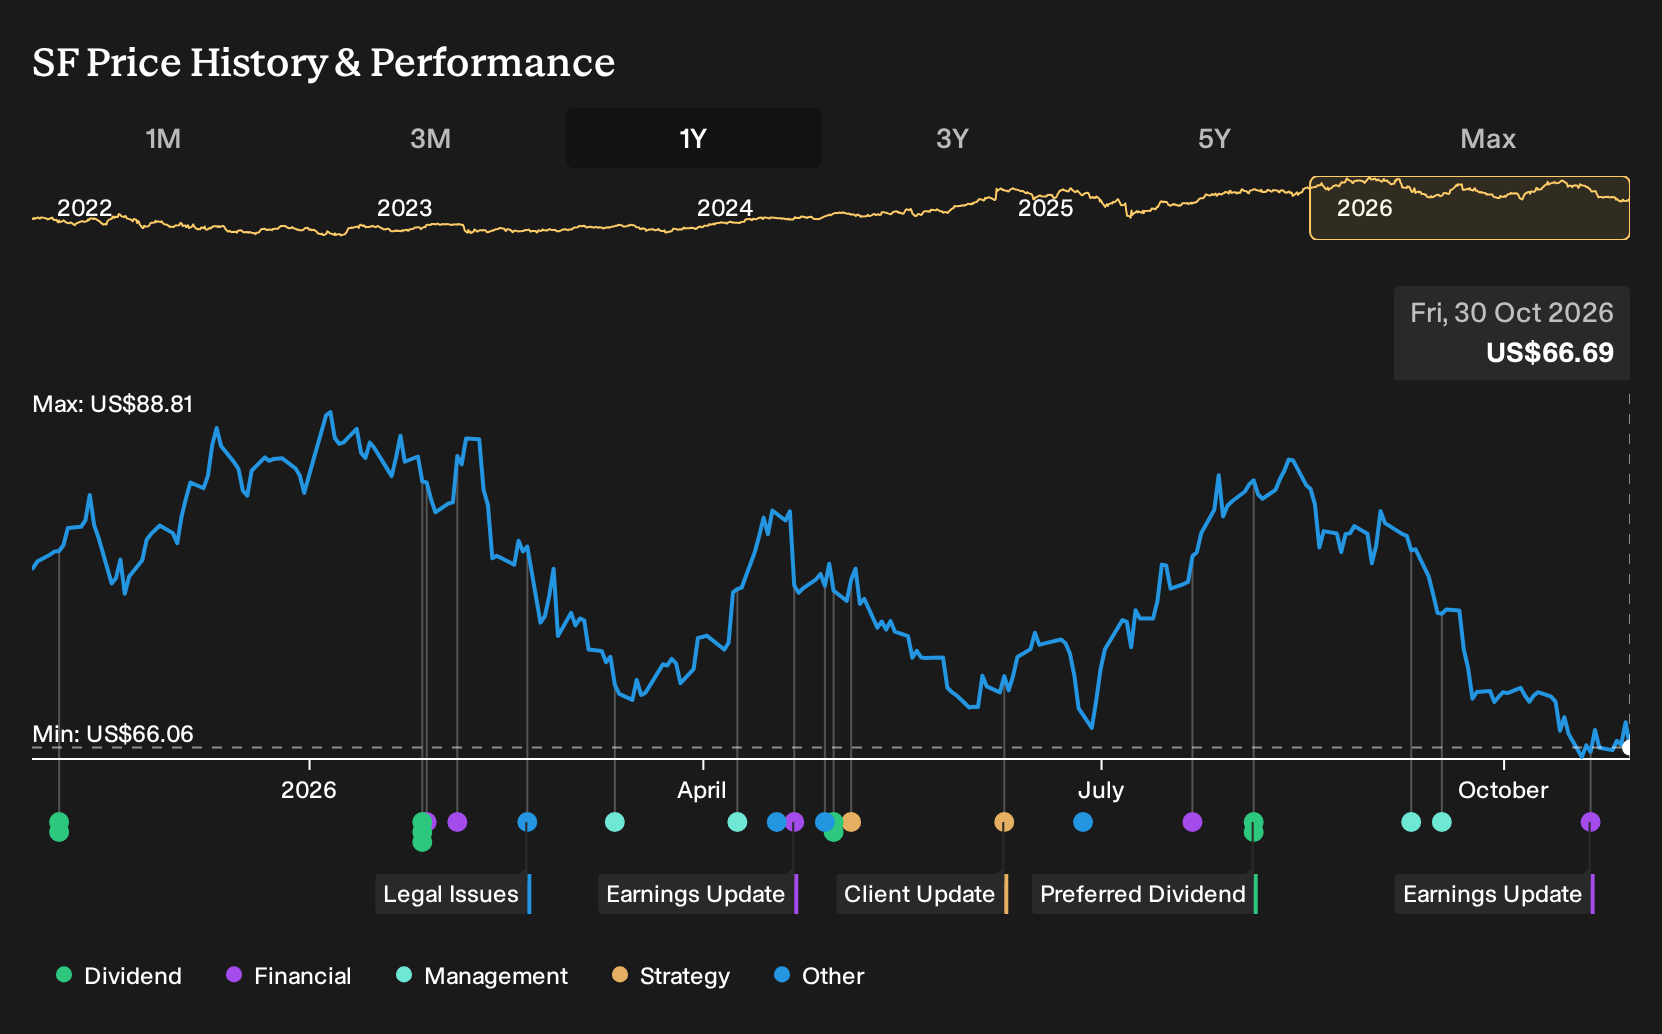
Exploring Other Perspectives
One alternate view zooms in on Stifel Financial’s planned US$4b balance sheet expansion into areas like fund banking and venture lending. The most cautious analysts were pencilling in about US$5.7b of 2029 revenue and a US$1.3b earnings line before this report. That flatter top line path reflects a more nervous stance on credit risk. You can use that as a reference point to explore how this fresh earnings release might shift those more conservative stories over time.
Explore 2 other Stifel Financial fair value estimates, including one that suggests it could be worth just $68.58.
Form Your Own Verdict
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Stifel Financial research is our analysis highlighting 5 key rewards that could impact your investment decision.
- See our latest analysis for Stifel Financial. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Stifel Financial's overall financial health at a glance.
Looking for more investment ideas beyond Stifel Financial?
Once you have formed a view on Stifel Financial, it can help to compare the risk and reward trade off with a wider set of quality businesses using the Simply Wall St Screener.
- If you want companies that combine financial strength with room to grow, start with this curated set of 19 high quality undiscovered gems that already show robust fundamentals.
- For investors who care most about resilience and capital protection, filter for steadier profiles using a focused group of 29 resilient stocks with low risk scores that score well on balance sheet and volatility metrics.
- Income focused readers can scan for reliable cash generators by zeroing in on 5 dividend fortresses that pair higher yields with solid underlying financials.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com