


How Weaker Farm Equipment Demand Will Impact AGCO Stock
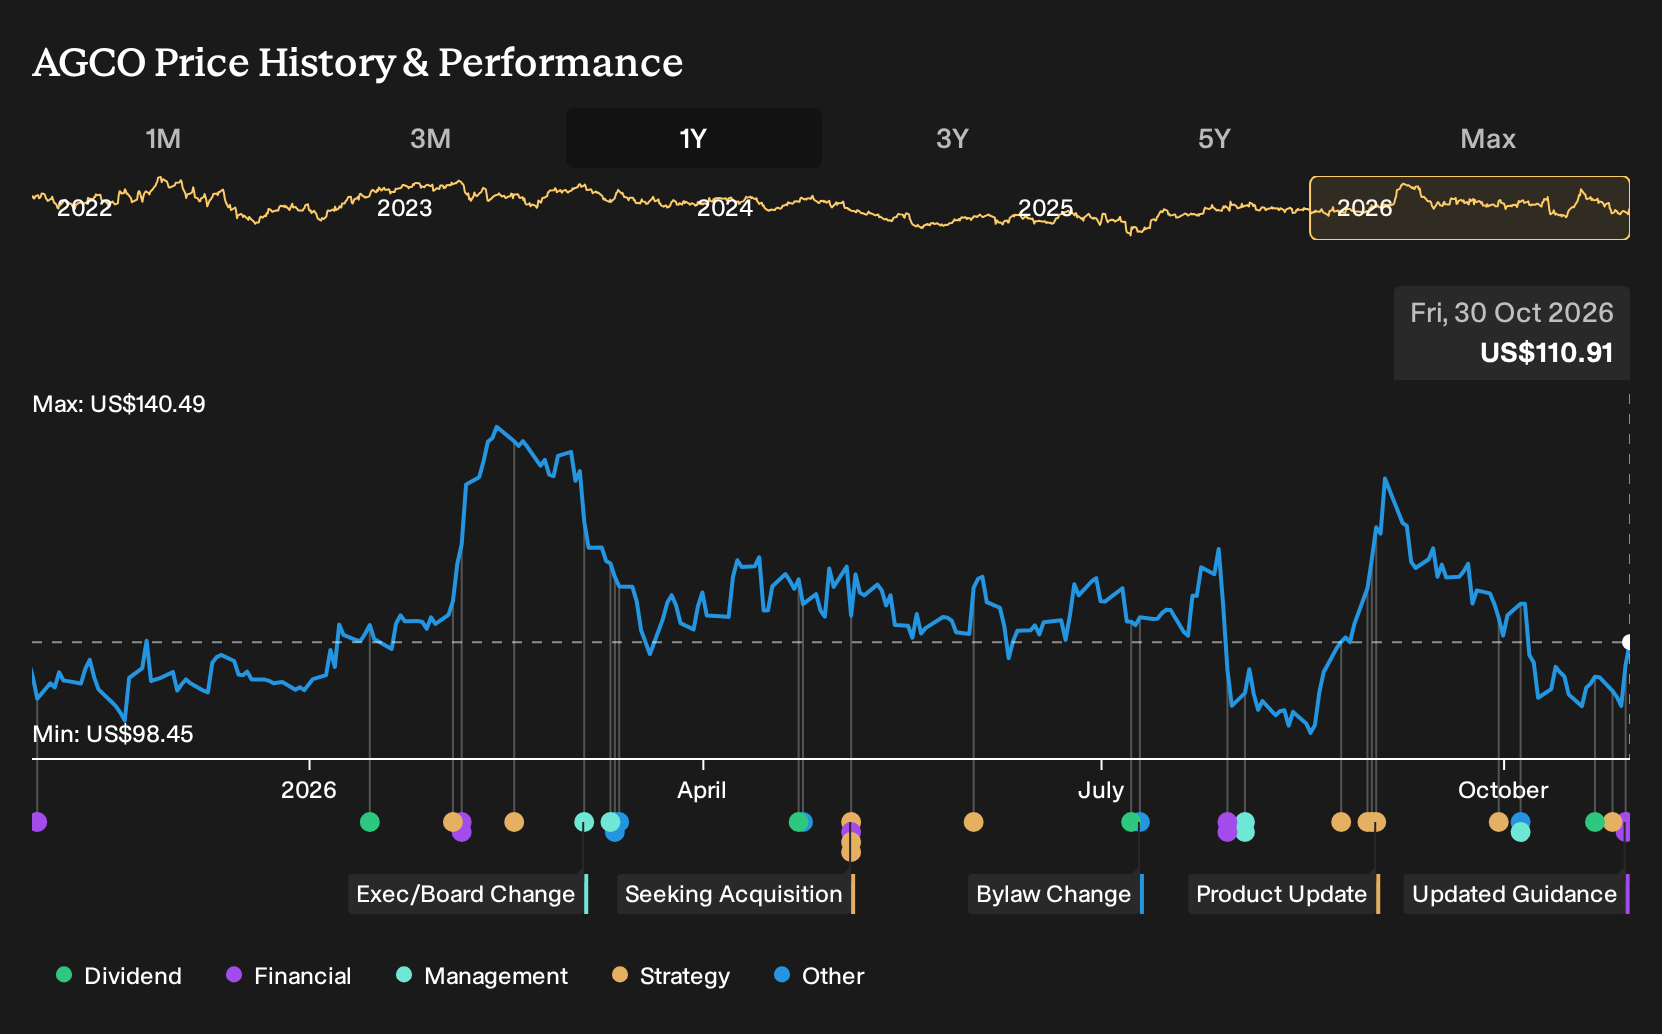
- AGCO reported third quarter 2026 sales of US$2,262.5 million and net income of US$51.7 million, and cut its full year outlook as management cited the weakest global agricultural equipment demand in more than a decade.
- Despite pressure in Europe, the Middle East and Latin America, AGCO is leaning on precision agriculture programs, cost controls and resilient North American demand to support its long term shift toward higher value, less cyclical revenue streams.
- The focus now turns to how AGCO's reduced 2026 sales guidance shapes the existing investment narrative built around precision agriculture expansion.
AGCO Investment Narrative Recap
To own AGCO here, you need to be comfortable with a tough cycle in global ag equipment while believing its precision programs, retrofit offerings and premium brands eventually support a less lumpy business mix. The latest quarter, with US$2,262.5 million in sales and US$51.7 million in net income, underlines how much earnings are tied to current volume pressure.
The key near term swing factor is how quickly demand stabilises in Europe and Latin America while North America holds up and cost programs offset weaker absorption. The biggest risk remains that depressed equipment orders and higher tariffs linger beyond 2026 and keep margins and cash generation below management’s ambitions.
Among the recent items, the new hydraulic singulation chute for the Massey Ferguson SB.1436DB baler is most relevant to the AGCO story investors are tracking. It targets practical gains in time, fuel and labour use for hay producers and plugs directly into the precision and workflow upgrade narrative, rather than being just another piece of iron.
If this type of hardware, tied into AGCO’s precision and retrofit ecosystem, gains traction in the field, it can support higher value, less cyclical revenue tied to productivity rather than just horsepower. Execution risk sits in proving reliability, dealer support and real world payback so that products like this become recurring upgrade decisions, not one off purchases.
AGCO's current analyst narrative points to US$12.2b in revenue and US$871.8m in earnings by 2029, built on an assumed 5.5% yearly increase in revenue. That earnings path implies a rise of about US$338m from US$533.4m today to the US$871.8m consensus figure.
Discover how AGCO's fair value points to a 12% potential upside from its current price before that valuation gap closes.
Exploring Other Perspectives
One alternate view around AGCO leans hard into the risk that weak equipment demand sticks. The most cautious analysts were only pencilling in about US$11.2b of revenue and US$672.0m of earnings by 2029, even before this Q3 reset. That is a far more pessimistic story. Use this as a cue to compare several viewpoints before deciding what makes sense to you.
Explore 3 other AGCO fair value estimates, including one that suggests there could be as much as 10% downside from the current price.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd. Trust your own analysis and go with your instincts.
- A great starting point for your AGCO research is our analysis highlighting 2 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for AGCO. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate AGCO's overall financial health at a glance.
Looking for more AGCO-sized investment ideas?
If the AGCO story has sharpened your thinking about cycles, balance sheets and future earnings power, use that same lens across a wider watchlist. The Simply Wall St Screener can help you quickly sort through companies that fit different risk and reward preferences so you are not relying on a single narrative.
- If capital preservation comes first for you, start with companies that score well on resilience and financial risk by screening for 29 resilient stocks with low risk scores.
- For investors focused on value and quality, narrow your research to stocks that pair solid fundamentals with compression in their valuation using the 30 high quality undervalued stocks.
- Income focused readers who care about reliable cash returns can concentrate on businesses with higher yields and sturdier payout profiles through the 5 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com