


Agree Realty (ADC) Beat On Earnings, Is It Still A Bargain?
Agree Realty earnings beat sets the tone
Agree Realty (ADC) just released third quarter and nine month results, with higher sales, revenue, net income, and earnings per share compared with the same periods a year earlier.
Investors now have fresh numbers to weigh against the current share price, which closed at US$67.07 on 29 October 2026, as they assess how this real estate investment trust’s retail focused portfolio is performing.
Over the past year, Agree Realty’s 1 year total shareholder return declined 4.09%, while the share price is down 7% year to date and 12.79% over the last three months, a pattern that hints at fading momentum despite the recent earnings update.
Compare Agree Realty’s earnings story with other real estate players by scanning a curated set of list of solid balance sheet and fundamentals (24 results) that have been holding up through recent market swings.
Agree Realty now trades below both analyst targets and one intrinsic value estimate, despite the earnings beat. So where does a reasonable fair value range sit in that gap between price and models?
Most Popular Narrative: 17% Undervalued
Agree Realty’s most followed valuation story anchors fair value at about $80.67 per share, which sits well above the latest $67.07 close and frames the recent earnings beat as only part of the picture.
Record capital deployment in Q2 2026 of more than US$500 million across acquisitions, development and developer funding, together with higher 2026 investment guidance of US$1.6 to US$1.8 billion and a medium term goal of at least US$250 million of annual development and developer funding commencements, points to a wider asset base that can support higher rental revenue and AFFO over time.
See why 120 investors see Agree Realty as 17% undervalued.
The fair value framework behind this narrative uses an 8.0% discount rate and assumes Agree Realty keeps expanding its US retail property portfolio while holding margins relatively steady. That approach links the current $80.67 estimate directly to expectations for rental income growth, funding costs and long term earnings power rather than short term share price swings.
For readers weighing the gap between the market quote and this narrative driven appraisal, the question is whether the assumptions on revenue growth, profit margins around 28% and ongoing capital deployment still feel realistic after the latest results and interest rate moves.
Result: Fair Value of $80.67 (UNDERVALUED)
Still, the Agree Realty narrative can crack if funding costs stay elevated for longer or if construction expenses climb faster than project-level rents.
Find out about the key risks to this Agree Realty narrative.
Another View: What Multiples Say About Agree Realty
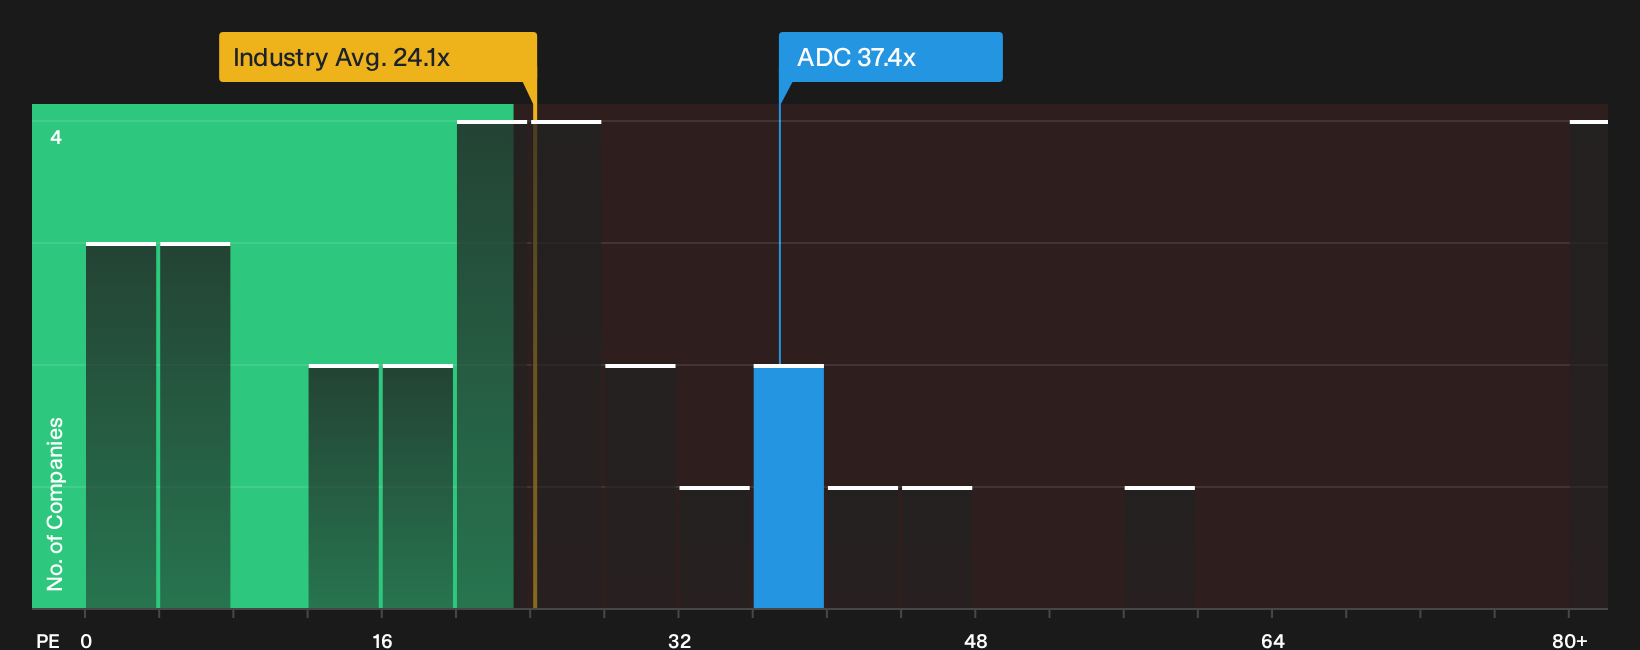
The first narrative leans on discounted cash flows and long term rental income to argue Agree Realty looks undervalued. A simple P/E check paints a tougher picture. ADC trades on a 37.4x P/E, compared with a 22.2x peer average and a fair ratio of 35.7x, which points to a premium valuation rather than a clear bargain.
That kind of gap can be a reward for quality earnings and dividend reliability, or it can just leave less room for error if sentiment toward retail REITs cools further. Which story feels more convincing to you right now?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on Agree Realty’s value story can cut both ways, so move quickly, review the full picture and weigh up the 4 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Agree Realty?
If Agree Realty has sharpened your focus, do not stop here. Fresh ideas often come from comparing different businesses, sectors and risk profiles side by side.
- Target resilient balance sheets and steady fundamentals by filtering for companies through a list of solid balance sheet and fundamentals (24 results) that can better handle shocks.
- Hunt for potential mispriced opportunities by scanning a curated pool of 30 high quality undervalued stocks before the crowd pays attention.
- Prioritize income and staying power by tracking companies in a selection of 29 resilient stocks with low risk scores that aim to pair resilience with measured upside.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com