


Bunzl (LSE:BNZL) Reaffirmed Guidance And Bought Blueleaf Care, Is The Stock Fully Valued?
Why Bunzl’s latest deal is moving the stock
Bunzl (LSE:BNZL) has been in focus after reporting resilient third quarter results, reaffirming guidance and announcing the acquisition of Blueleaf Care, a move that deepens its reach in the UK care market.
Investors now have fresh information on both trading conditions and capital allocation. This gives you more concrete reference points when judging how the current share price lines up with Bunzl’s recent progress.
The recent news comes after a strong run, with Bunzl’s share price delivering a 9.6% gain over the past month and a 38.8% year-to-date share price return. Meanwhile, the 1-year total shareholder return of 27.8% points to momentum that investors appear to view as increasingly credible, rather than just a short-term bump around the Blueleaf Care deal and third-quarter update.
Compare Bunzl’s recent surge with other distributors and service businesses that are quietly building momentum through acquisitions and steady execution in our curated list of 5 resilient stocks with low risk scores.
The recent jump puts Bunzl in a very different place to where it started 2026. The real task now is weighing up paying today’s price versus waiting for a calmer entry as the valuation picture comes into focus.
Most Popular Narrative: 3% Overvalued
Bunzl’s most followed valuation narrative pegs fair value at £27.82, slightly below the last close at £28.64. This frames the recent rally as pricing in a lot of the known progress already.
The main thing that has to go right is that Bunzl continues to execute on consolidation, automation and digital programmes. At the same time, it needs to keep the North America Distribution turnaround on track so that mix shift toward higher value sectors and own brand can offset pressure in softer markets.
See why 36 investors see Bunzl as 3% overvalued.
Result: Fair Value of £27.82 (OVERVALUED)
Still, the narrative can wobble if margin pressure in North America or softer conditions in markets like Mexico and Brazil weaken Bunzl’s earnings path.
Find out about the key risks to this Bunzl narrative.
Another view on Bunzl’s valuation
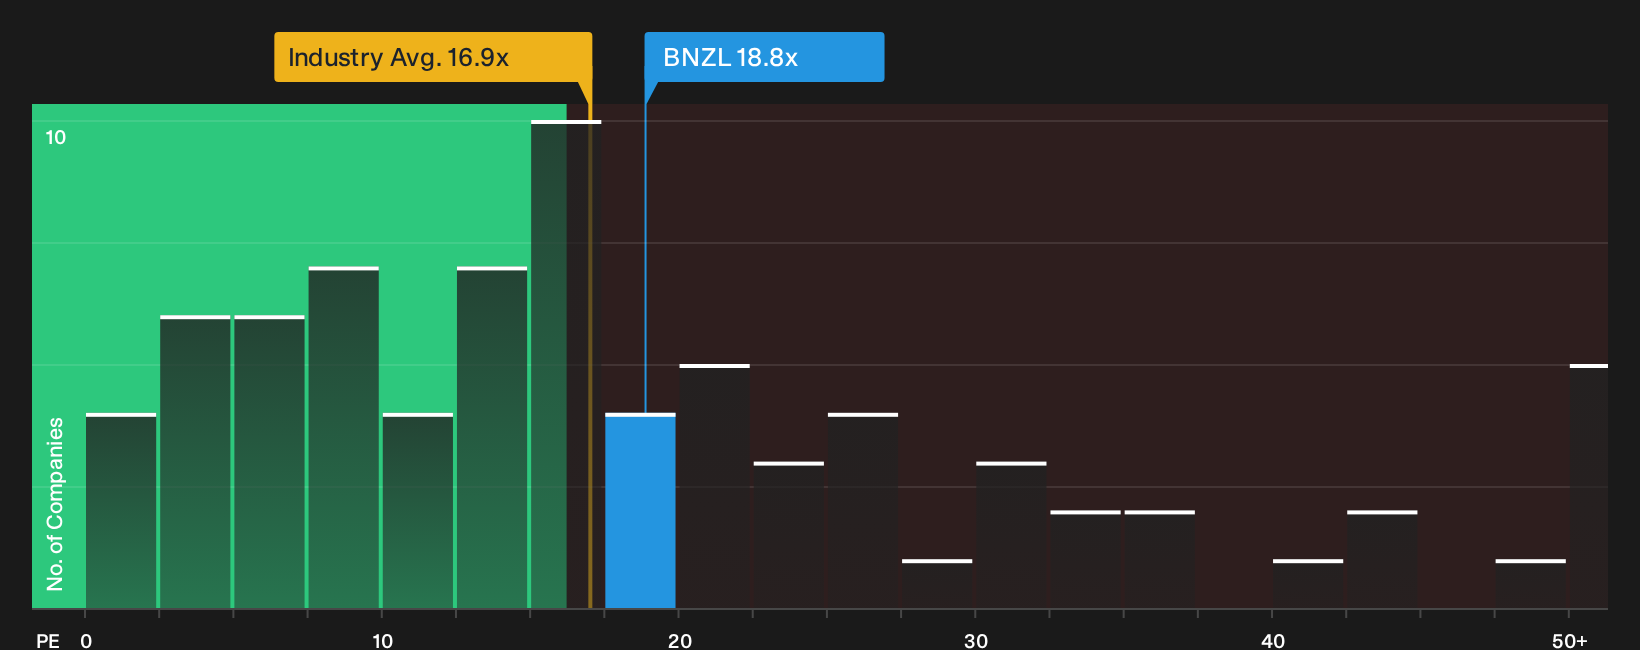
On simple earnings multiples, Bunzl looks less stretched than the 3% overvalued narrative suggests. The shares trade on a P/E of 18.8x versus a peer average of 26x and a European Trade Distributors industry level of 16.9x, while the fair ratio sits at 19.9x. That mix points to a stock where valuation risk cuts both ways if sentiment shifts toward either the sector or that fair ratio.
To see how this earnings multiple picture could evolve as expectations change, take a closer look at the valuation breakdown via See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
If the mixed tone of Bunzl’s story leaves you unsure, use that unease as a prompt to dig into the data and decide fast. To weigh the balance of concerns against the upside investors see, start with 3 key rewards and 2 important warning signs.
Looking for more Bunzl-like investment ideas?
You have seen how Bunzl’s story blends resilient operations with valuation debate, so do not leave your portfolio dependent on a single opportunity set.
- Target steadier compounding potential by scanning a list of solid balance sheet and fundamentals (10 results) that focuses on companies with robust finances and cleaner balance sheets.
- Hunt for better price tags by reviewing a 14 high quality undervalued stocks that filters for quality businesses trading below their assessed worth.
- Build a cash flow stream by lining up a 5 dividend fortresses geared toward higher yielding companies with income front and center.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com