


How PNC Partnership At ADP Has Changed Its Investment Story
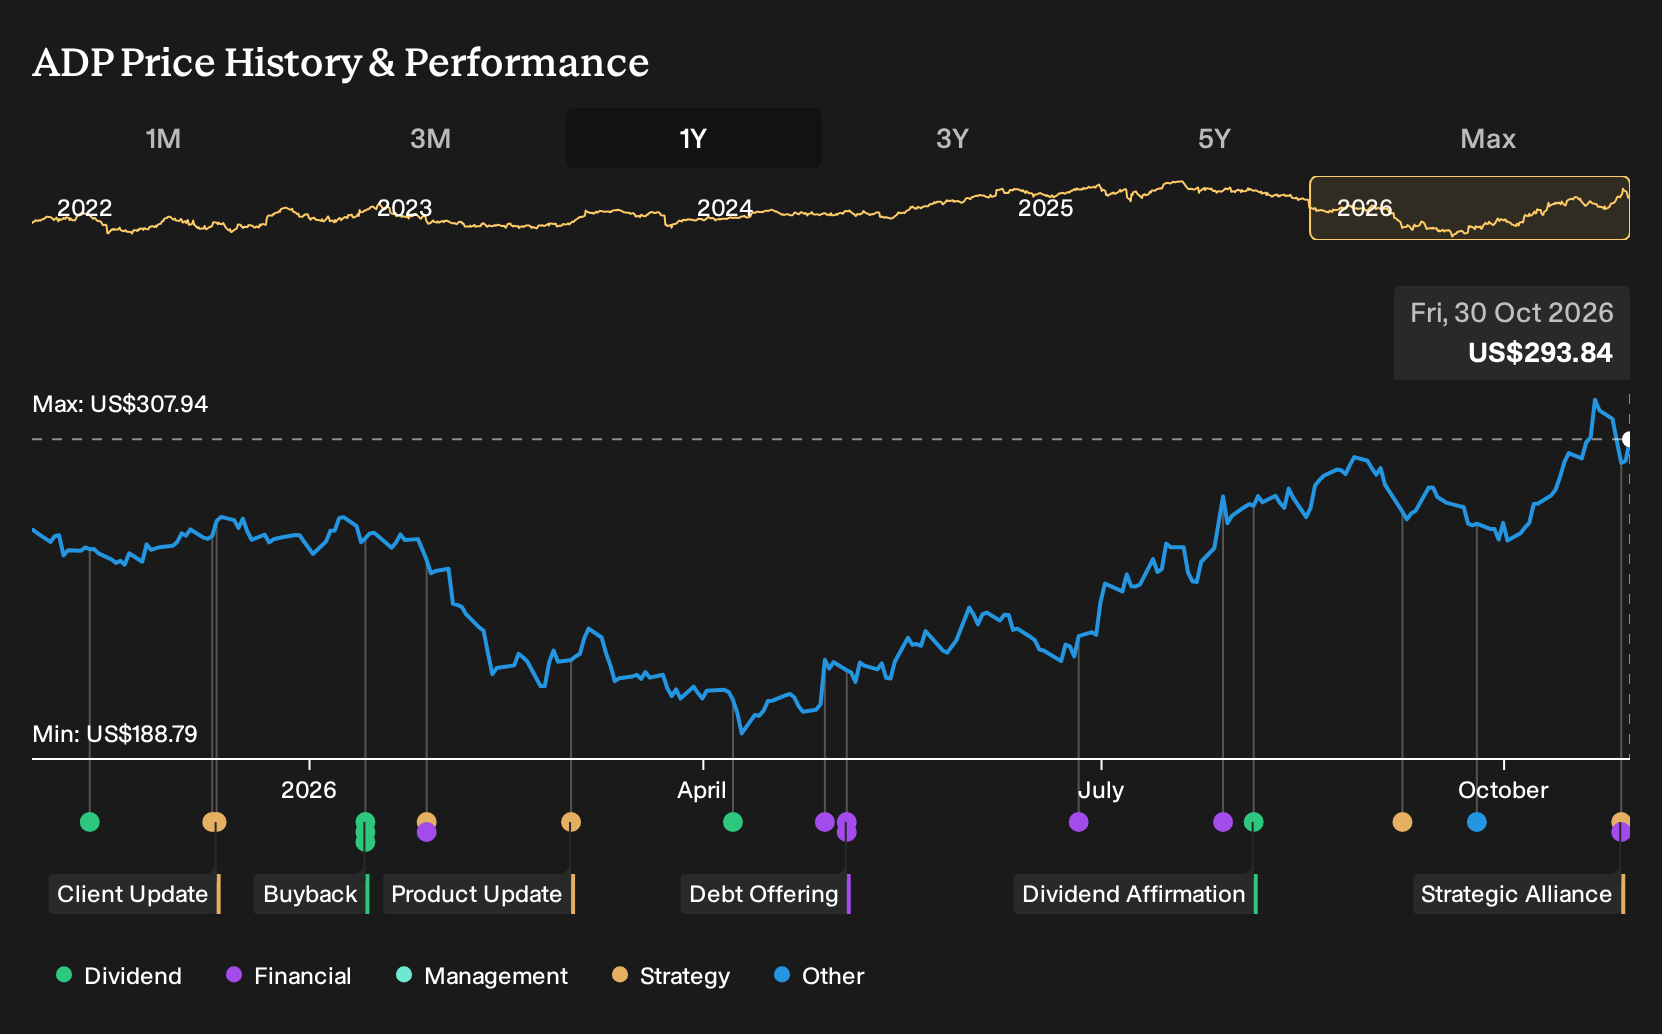
- Automatic Data Processing reported first quarter results for the period ended September 30, 2026, with revenue of US$5,490.7 million and net income of US$1,125.2 million, alongside a new partnership in which PNC Bank is embedding ADP payroll and HR tools into its digital banking platform for small businesses.
- The PNC Payroll by ADP arrangement provides Automatic Data Processing with a direct path into PNC's small business banking base, while the quarter's basic earnings per share of US$2.84 and diluted earnings per share of US$2.83 indicate how the underlying business is converting its payroll and HR scale into per share profitability.
- The following section considers how Automatic Data Processing's investment narrative is influenced by embedding its payroll tools within PNC's platform.
Scan how Automatic Data Processing’s embedded payroll move with PNC compares to other platforms reshaping back office workflows by running through the curated 95 robotics and automation stocks for process automation leaders.
Automatic Data Processing Investment Narrative Recap
To hold Automatic Data Processing, you need to believe its mix of cloud HCM platforms, PEO services and AI tooling can keep attracting new employers while keeping service costs in check. The latest quarter shows revenue of US$5,490.7 million and net income of US$1,125.2 million, so the operating base is sizeable. A key short term swing factor remains execution on Employer Services bookings and client implementations.
The biggest near term risk still sits in PEO margins and potential price pressure as more AI heavy HR tools enter the market. The PNC Payroll by ADP launch helps distribution into small businesses but does not fundamentally change those core risks. It looks additive rather than a thesis shifting event right now.
The PNC partnership is the clearest tie in to the current catalyst story. Automatic Data Processing is pushing embedded payroll into the digital experiences small firms already use, and PNC’s banking portal is one of those daily touchpoints. If adoption is solid, this can support demand for platforms like RUN and Workforce Now, alongside newer tools such as Lyric HCM and ADP Assist.
On the other side of the ledger, embedding services into a bank’s workflow raises execution demands. Service quality, uptime and compliance expectations are high in that channel. Any missteps could dent the brand just as ADP is leaning on AI driven automation and enterprise HCM deals to support earnings and margin targets, so investors will likely watch client traction and service performance closely.
What The ADP Embedded Payroll Story Implies About 2029
Automatic Data Processing’s embedded push with PNC is unfolding against a backdrop where analysts already model steady expansion in the core business. Consensus assumptions point to revenue growing by 5.7% per year over the next three years, supported by a shift toward higher margin cloud HCM platforms and AI powered tools such as Lyric HCM and ADP Assist. Those same forecasts build in an improvement in profit margins from 20.3% today to 21.7% over that window, so expectations already assume better efficiency on each dollar of payroll and HR processing that runs across the network.
On earnings, the analyst playbook is straightforward. Current net income of US$4.5b is expected to reach US$5.7b by 2029, which is about a US$1.2b increase in profit over that period. The path relies on earnings per share climbing to US$14.91 as share count declines roughly 2.2% a year, so per share metrics are expected to benefit from both operating progress and buybacks. Investors weighing the PNC embedded payroll rollout are therefore layering that distribution deal on top of an earnings curve that already bakes in higher margins and lower share count rather than treating it as the sole growth engine.
Valuation expectations for Automatic Data Processing sit on top of those operating assumptions. Analysts tie their price targets to a 2029 earnings figure of US$5.7b and revenue of US$26.3b, then apply a P/E multiple of 23.9x, which is above the current US Professional Services sector average of 22.3x. The current reported P/E for ADP is 25.0x, so the framework assumes the stock trades on a slightly lower multiple over time even as earnings rise. That mix of modest multiple compression and higher profit effectively says that much of the story, including efforts like embedded payroll with PNC, is already reflected in the valuation rather than being treated as blue sky upside.
Automatic Data Processing's narrative projects US$26.3b revenue and US$5.7b earnings by 2029. This requires 5.7% yearly revenue growth and about US$1.2b earnings increase from US$4.5b today.
Uncover why Automatic Data Processing's fair value is essentially in line with its current price.
Exploring Other Perspectives
Some of the lowest analysts focus on a different risk for Automatic Data Processing. They worry heavy AI and data platform spending could cap margin gains, even with the PNC Payroll by ADP launch. Their pre news models were calling for about US$26.0b revenue and US$5.6b earnings by 2029, with a much lower 19.7x P/E. That is a more cautious story than consensus, so use it as a reminder that reasonable views can differ widely and that this new partnership may nudge both narratives over time.
Explore 4 other Automatic Data Processing fair value estimates, including one that suggests it could be worth just $296.20.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Automatic Data Processing research is our analysis highlighting 4 key rewards that could impact your investment decision.
- See our latest analysis for Automatic Data Processing. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Automatic Data Processing's overall financial health at a glance.
Looking For More Investment Ideas Beyond Automatic Data Processing?
Once you have a view on Automatic Data Processing, it helps to widen the lens and compare it with other stocks that fit different portfolio roles. The Simply Wall St Screener can surface companies with very different profiles, which gives you more context for judging whether ADP belongs alongside them in your mix.
- If you want potential value opportunities backed by solid fundamentals, scan through 30 high quality undervalued stocks that score well on both quality and price.
- If capital preservation is higher on your priority list, focus on stability first by reviewing a 29 resilient stocks with low risk scores that may help smooth out portfolio swings.
- If balance sheet strength matters most to you, compare ADP with a list of solid balance sheet and fundamentals (24 results) that can better withstand tougher operating conditions.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com