


What Eastman Chemical (EMN)'s Recycling Grant Reinstatement Means For Shareholders
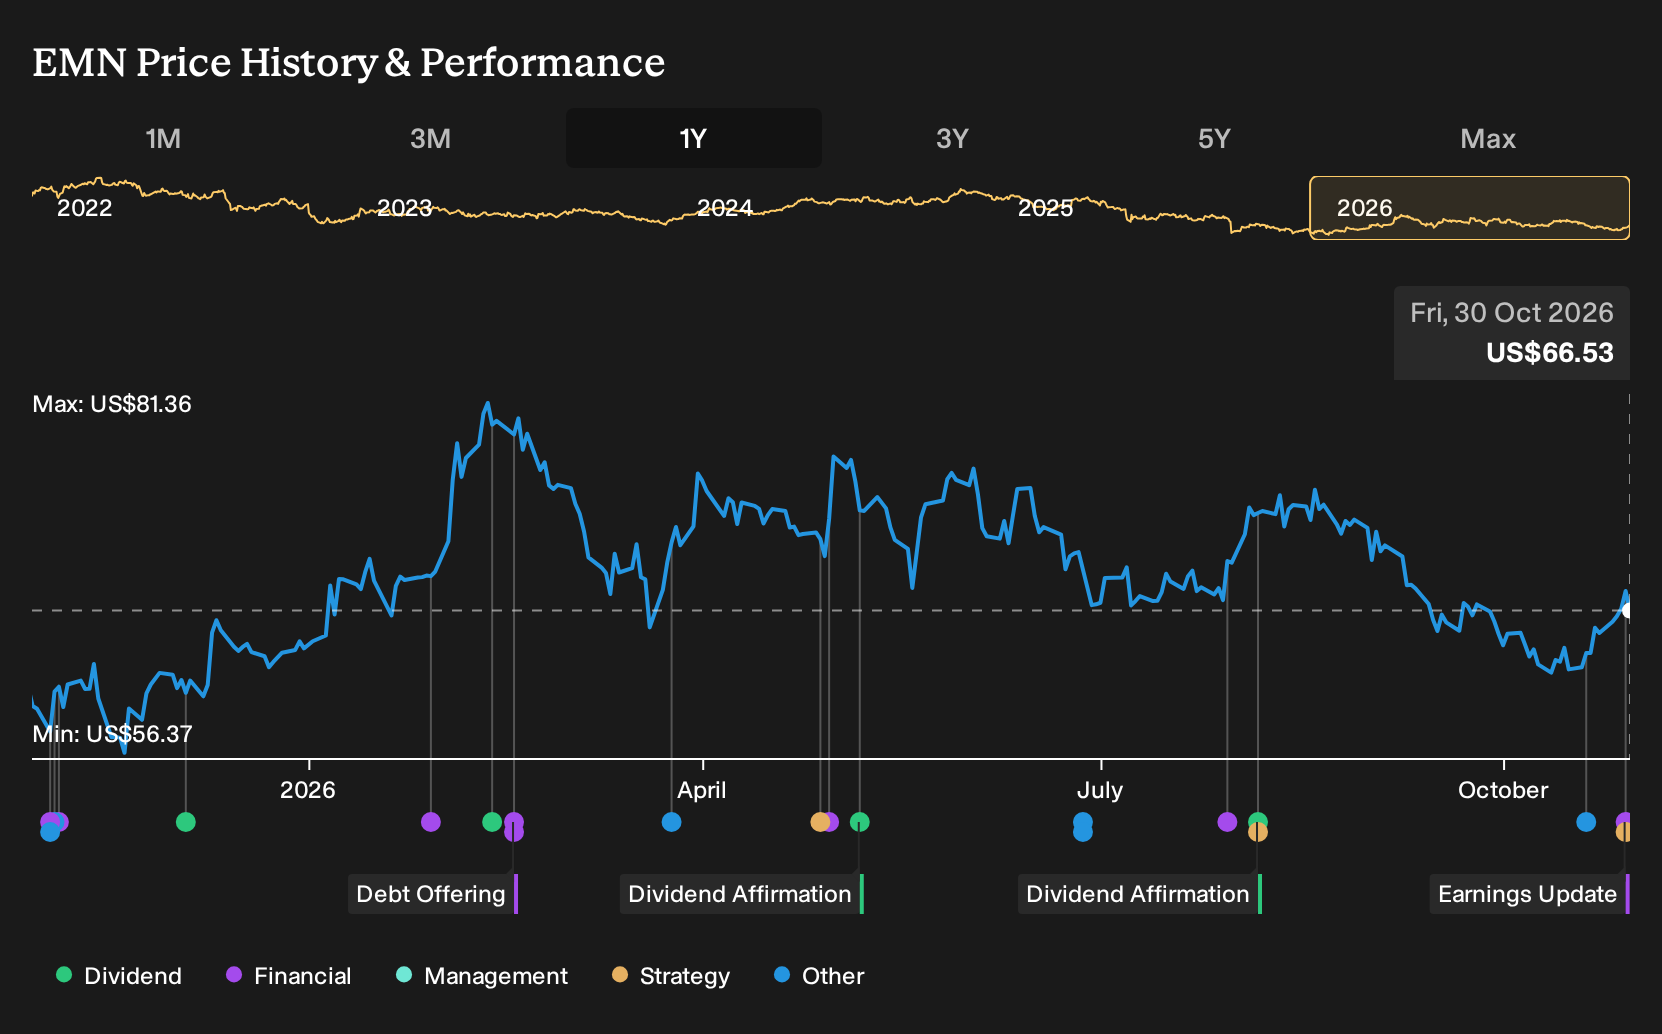
- Eastman Chemical reported Q3 2026 sales of US$2,385 million and net income of US$252 million, while also securing a reinstated US$375 million U.S. Department of Energy award to expand its methanolysis based circular recycling platform and U.S. plastics infrastructure.
- The reinstated federal funding lowers future capital spending needs on Kingsport and potential second site recycling projects. This directly affects how Eastman Chemical balances cash generation, growth investments in circular materials and execution on its broader cost reduction plans.
- We will now assess how Eastman Chemical's reinstated US$375 million recycling grant could reshape the existing investment narrative around circular earnings.
Scan how Eastman Chemical's circular recycling push compares with other potential compounders by checking a curated 30 high quality undervalued stocks that already pair strong cash generation with resilient balance sheets.
Eastman Chemical Investment Narrative Recap
To stay in Eastman Chemical, you need to believe the circular methanolysis push, specialty mix shift and cost programs can support steadier earnings even as older Fibers exposure, trade issues and feedstock swings keep biting. Q3 2026 showed the business can generate US$252 million of quarterly profit and higher EPS while absorbing raw material and distribution cost pressure.
The short term swing factor is execution on pricing and cost savings while Chemical Intermediates benefits from tight feedstock markets. That uplift still looks exposed. Trade friction, potential pushback on further price increases and ongoing Fibers softness remain the biggest operational risks, and the latest news does not remove those.
The reinstated US$375 million U.S. Department of Energy award is the announcement that really matters for this circular story. It directly supports Eastman Chemical’s plan to expand methanolysis capacity in Kingsport by about 30%, restart underused recycling assets and map out a disciplined path to a second U.S. facility.
For you as a shareholder, that funding reduces capital intensity for recycling projects and ties future spend to milestones and customer contracts. Execution still needs watching. The key questions are whether the firm can fill that extra capacity with profitable circular volumes, maintain pricing against lower cost producers and keep overall leverage in check while earnings remain sensitive to trade and feedstock conditions.
Analysts currently model Eastman Chemical’s trajectory with revenue growing 2.1% a year, with earnings today of US$442.0 million rising to a forecast consensus of US$841.0 million by 2029. This implies an increase of about US$399.0 million and lines up with projected 2029 revenue of US$9.4b and earnings of US$841.0 million in that same year.
Uncover how Eastman Chemical's fair value indicates a 16% potential upside to its current price before the market closes that gap.
Exploring Other Perspectives
For Eastman Chemical, the real disagreement sits around demand risk rather than circular upside. The most cautious analysts were assuming only 1.4% annual revenue growth and about US$9.2b of sales by 2029, with earnings of US$857.0 million. That is already a more skeptical story, and the new recycling grant plus Q3 earnings could lead to changes in those views. You can treat this spread in expectations as an invitation to compare multiple narratives before deciding what feels reasonable.
Explore 3 other Eastman Chemical fair value estimates, including one that suggests it could be worth just $75.19.
Reach Your Own Conclusion
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Eastman Chemical research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Eastman Chemical. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Eastman Chemical's overall financial health at a glance.
Looking for more investment ideas beyond Eastman Chemical?
Once you have a view on Eastman Chemical, it can help to widen the lens and compare it with other opportunities that share some of the qualities you care about, whether that is value, balance sheet strength or income potential.
- If you lean toward quality at a reasonable price, scan a curated 30 high quality undervalued stocks that can help surface companies with strong fundamentals trading on undemanding valuations.
- If capital protection and staying power matter most to you, focus on resilient businesses through a 29 resilient stocks with low risk scores that filters for companies with lower risk scores.
- If dependable income is a priority, shortlist potential payout candidates by reviewing a 5 dividend fortresses that concentrates on yields of 5% or more.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com