


Bolloré (ENXTPA:BOL) Faces A 45x P/E On Revenue Momentum
Revenue update puts Bolloré in focus
Bolloré (ENXTPA:BOL) has moved back onto investors’ screens after reporting third quarter 2026 group revenue of €937 million compared with €630 million a year earlier, highlighting a clear shift in recent trading activity.
Recent trading tells a mixed story. The share price is €3.77, with a 1-day share price return of 1.56% and a 7-day share price return of 2.61%, suggesting short-term momentum is picking up. At the same time, the year-to-date share price return is down 21.03%, even as the 1-year total shareholder return is 9.28%. This hints that dividends and past distributions have played a meaningful role in long-term outcomes for Bolloré investors.
Scan 197 high quality undervalued stocks that, like Bolloré after this revenue update, combine established operations with pricing that may not fully reflect their current business momentum.
The revenue jump has lifted Bolloré’s share price from its recent lows, but the longer-term return profile still appears uneven. Has most of the easy upside already been realised, or is the recent move simply the opening act for a broader rerating in the company’s valuation?
Price-to-earnings of 45.1x: Is it justified for Bolloré?
Bolloré shares last closed at €3.77, and the stock trades on a P/E of 45.1x, which points to a rich valuation compared with both peers and its own “fair” multiple estimate.
The P/E ratio measures how much investors are paying today for each euro of earnings. For a diversified group like Bolloré, which spans energy distribution, communications and industrial activities, that figure often reflects expectations about how dependable and repeatable those profits are across different business lines.
In this case, the current 45.1x P/E sits well above the French Oil and Gas peer average of 16.2x and the broader European Oil and Gas benchmark of 12.8x. It also exceeds the estimated fair P/E of 17.4x, which is a level the market could move towards if sentiment cools or earnings do not rise in line with this premium.
Explore the SWS fair ratio for Bolloré.
Result: Price-to-earnings of 45.1x (OVERVALUED)
Still, the rich 45.1x P/E leaves Bolloré exposed if earnings growth stalls or if sentiment toward French Oil and Gas stocks cools quickly.
Find out about the key risks to this Bolloré narrative.
Another view on Bolloré’s value
A second lens tells a different story for Bolloré. The SWS DCF model points to a future cash flow value of €2.61 per share, compared with the current price of €3.77. That suggests the stock is priced above modeled cash flows today, which raises a simple question: Is the market paying up for qualities that do not show in this spreadsheet view?
Look into how the SWS DCF model arrives at its fair value.
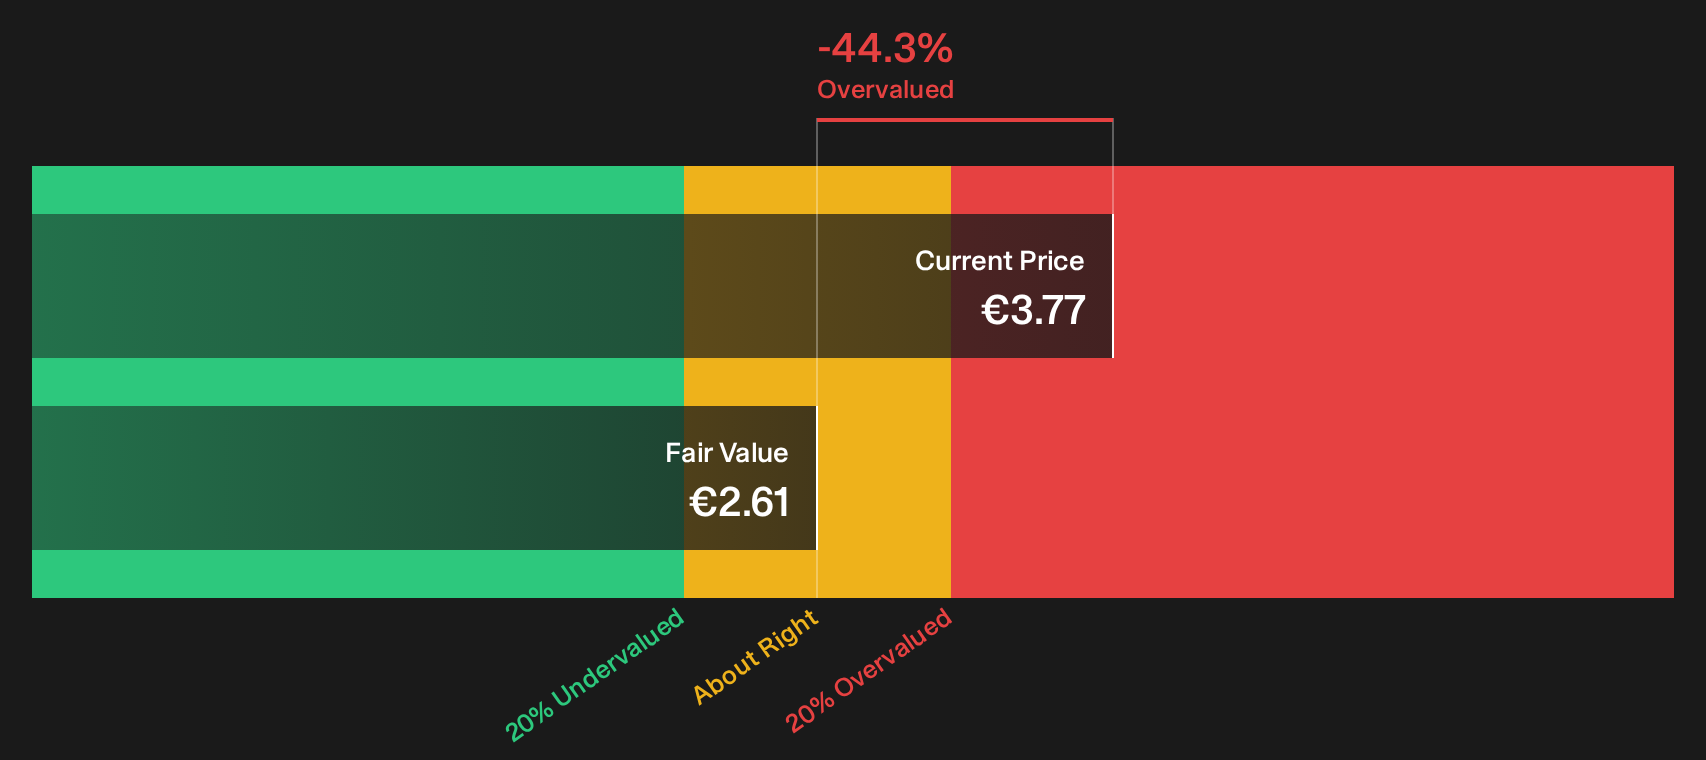
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Bolloré for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 197 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
If this combination of rich valuation and shifting returns around Bolloré leaves you uncertain, review the complete picture and weigh the 1 key reward and 2 important warning signs.
Looking for more investment ideas beyond Bolloré?
If Bolloré has your attention today, do not stop there. The wider opportunity set matters just as much as one impressive headline.
- Target potential mispricings by checking companies on the 197 high quality undervalued stocks that pair solid fundamentals with prices the market may not fully appreciate yet.
- Build a steadier income stream by weighing businesses in the 222 dividend fortresses that aim to combine meaningful yields with resilient payout histories.
- Prioritise resilience by working through the 218 resilient stocks with low risk scores where balance sheets and risk scores help you focus on durability, not just excitement.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com