


Will Record Revenue Change Sonic Automotive's (SAH) Narrative
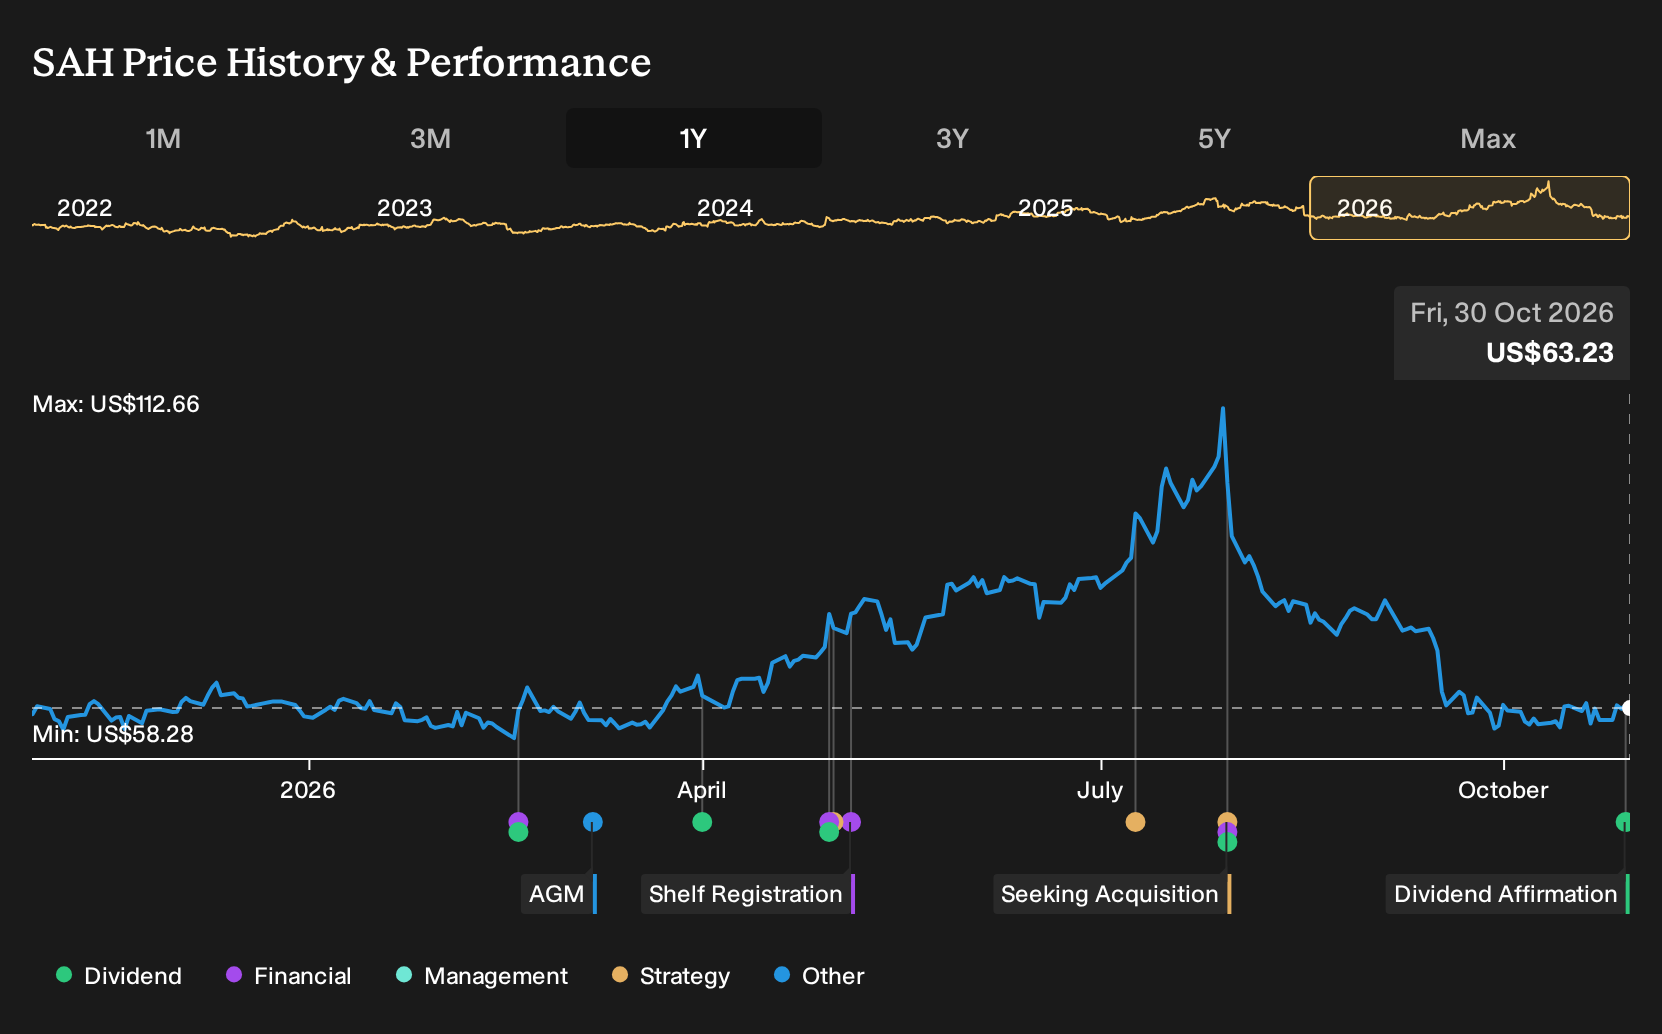
- Sonic Automotive reported record quarterly revenue and gross profit, supported by record fixed-operations gross profit and value pricing aimed at attracting more service customers. The board reaffirmed a quarterly cash dividend of $0.41 per share that was paid on January 15, 2027 to shareholders of record on December 15, 2026.
- The combination of record operating performance, fresh investment plans for the EchoPark brand and AI-supported service-lane pricing, and a steady dividend indicates a management team that is prioritising both reinvestment in the business and ongoing cash returns to shareholders.
- The next step is to examine how Sonic Automotive's record quarterly revenue, combined with continued dividends, could influence the broader investment narrative.
Compare Sonic Automotive's mix of record revenue, AI-supported pricing and a reaffirmed dividend with hand-picked peers by scanning our curated list of 30 high quality undervalued stocks.
What Is Sonic Automotive's Investment Narrative?
Sonic Automotive asks you to believe in a fairly simple story. A large US auto retailer with three segments, it leans on record fixed operations and value pricing in the service lane while pushing EchoPark expansion and AI supported pricing to keep guests flowing through the network. That mix is capital intensive and operationally heavy. It only really works if management keeps executing on disciplined inventory turns, service throughput and used vehicle pricing.
The reaffirmed US$0.41 quarterly dividend fits that story as a signal of confidence more than a new catalyst. Recent results show earnings growth and a P/E of 9.7x that sits below both the US market and Specialty Retail peers. The tension is that interest costs are not comfortably covered and the dividend is not well supported by free cash flow, so funding EchoPark growth, AI initiatives and shareholder payouts all at once depends on careful capital allocation and consistent operating performance.
There's only one way to know the right time to buy, sell or hold Sonic Automotive. Head to Simply Wall St's company report for the latest analysis of Sonic Automotive's Fair Value.
Exploring Other Perspectives
One alternate view focuses on EchoPark margin pressure. The most pessimistic analysts were already pencilling in Sonic Automotive revenue of about US$17.4b and earnings near US$257.3m by 2029, which they saw as only modest progress. That group might interpret the reaffirmed US$0.41 dividend very differently and could update their story from here.
Explore 3 other Sonic Automotive fair value estimates, including one that suggests as much as 32% downside from the current price.
Reach Your Own Conclusion
Disagree with this assessment? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Sonic Automotive research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Sonic Automotive. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Sonic Automotive's overall financial health at a glance.
Looking For More Investment Ideas Beyond Sonic Automotive?
If Sonic Automotive has sharpened your thinking about what you want from a business, it helps to compare that view against a wider field of opportunities. Use the Simply Wall St Screener to line up other companies against the same mix of cash generation, balance sheet strength and income potential that you are weighing here.
- If you care most about durable balance sheets and solid fundamentals, start with this list of solid balance sheet and fundamentals (24 results) and filter for businesses that match your risk tolerance.
- Income focused investors who still want financial resilience can scan a curated set of higher yield opportunities by reviewing these 5 dividend fortresses and checking how each payout is backed by cash flows.
- For those hunting for potential mispricing in quality businesses, use this hand picked collection of 19 high quality undiscovered gems to see which stocks deserve a place on your watchlist.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com