


How Investors May Respond To Wabtec Stock After Earnings Beat
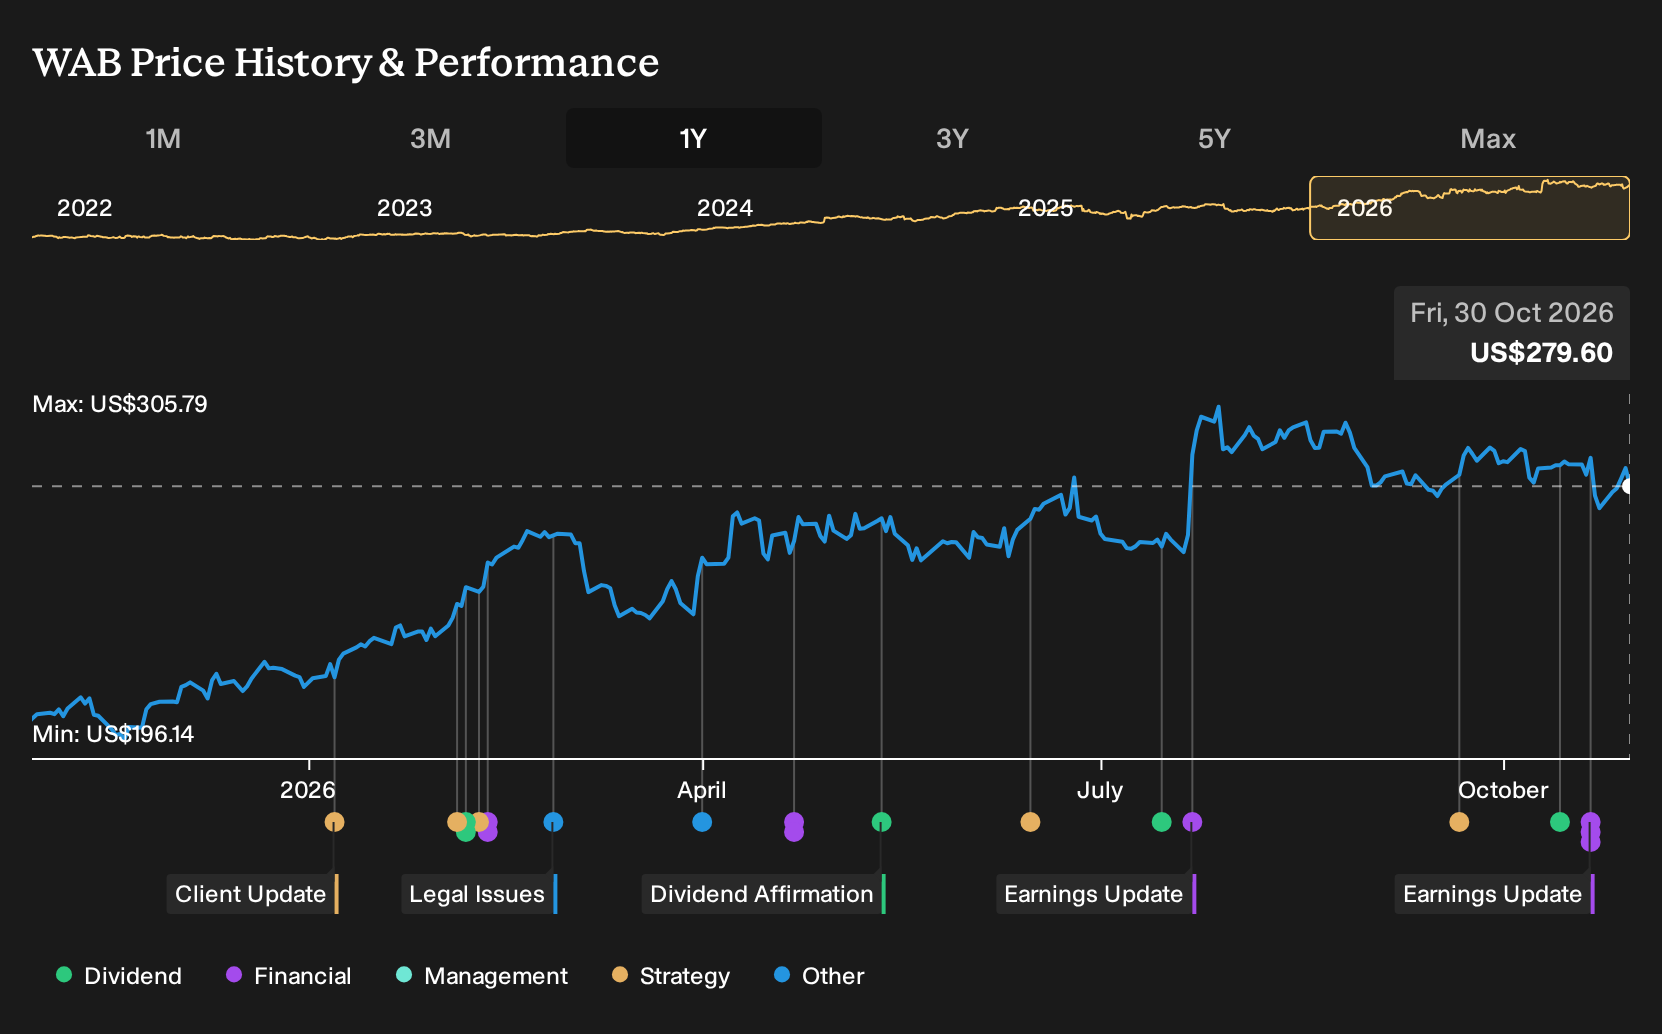
- Westinghouse Air Brake Technologies reported third quarter 2026 revenue of US$3.12b and net income of US$409m, alongside continued full year 2026 revenue guidance of US$12.3b to US$12.6b.
- The combination of higher earnings per share from continuing operations and reaffirmed guidance indicates ongoing demand for Wabtec’s rail equipment and services. In addition, the universal shelf registration adds flexibility for future capital raising or balance sheet moves.
- We will now look at how Westinghouse Air Brake Technologies’ investment narrative is affected by its stronger quarterly earnings and confirmed guidance.
Scan beyond Westinghouse Air Brake Technologies’ reaffirmed guidance and earnings beat by reviewing a curated group of rail and industrial peers, screened for resilient balance sheets and fundamentals via our list of solid balance sheet and fundamentals (24 results).
Westinghouse Air Brake Technologies Investment Narrative Recap
To own Westinghouse Air Brake Technologies, you need to believe its multiyear rail backlog, higher margin Digital Intelligence offerings and acquisition integration efforts can offset tariff pressure, high debt and a softer modernization cycle in services. The latest quarter supports that operating thesis, although it does not fully resolve concern about how much modernization demand recovers.
The key near term swing factor remains services and modernization activity, particularly in North America, because that is where a lot of earnings leverage sits. The biggest risk is that tariffs and input costs keep squeezing margins while insider selling and a premium P/E leave little room for execution missteps.
The most relevant update for that story is the reaffirmed full year 2026 revenue guidance of US$12.3b to US$12.6b, with the midpoint framed as up 11.5% versus the prior year. Combined with third quarter revenue of US$3.12b and net income of US$409m, this points to management seeing enough demand visibility to stick with its plan.
For catalysts, that guidance matters because it interacts directly with tariffs, the weaker first half modernization cycle and efforts to grow higher margin software and services. If rail customers delay upgrade decisions or input costs stay sticky, hitting the guided revenue range may not translate into the same level of earnings quality that recent EPS numbers suggest.
Westinghouse Air Brake Technologies’ current earnings of about US$1.3b are set against analyst expectations for US$2.4b of earnings on US$14.8b of revenue by 2029. This implies forecast revenue growth of 7.3% per year and an earnings increase of roughly US$1.1b by that forecast year.
Uncover why Westinghouse Air Brake Technologies' fair value indicates an 18% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
Fair value estimates for Westinghouse Air Brake Technologies from 2 private investors in the Simply Wall St Community cluster tightly between about US$280 and US$330 per share. That is a narrow range. Set those opinions against tariff pressure, weaker services modernization and insider selling, and you can see why views diverge. Consider several viewpoints before deciding how this fits your portfolio.
Explore another Westinghouse Air Brake Technologies fair value estimate, including one that suggests up to 18% upside from the current price.
Decide For Yourself
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Westinghouse Air Brake Technologies research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Westinghouse Air Brake Technologies. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Westinghouse Air Brake Technologies' overall financial health at a glance.
Looking For More Ideas Beyond Westinghouse Air Brake Technologies?
If you want to round out your view beyond Westinghouse Air Brake Technologies, casting a wider net can help you spot opportunities with different risk and income profiles. The Simply Wall St Screener lets you filter for the traits that matter to you, then compare fundamentals side by side.
- If capital preservation sits high on your list, start with a group of resilient businesses that show lower risk scores through the 29 resilient stocks with low risk scores.
- For readers hunting for potential mispricing, scan a curated set of companies that combine quality fundamentals with valuation support using the 30 high quality undervalued stocks.
- Income focused investors can concentrate on businesses with stronger yields and payout profiles by reviewing a set of potential 5 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com