


Marks and Spencer Group (LSE:MKS), What Is Behind The Fresh Attention?
Marks and Spencer Group: What the recent move could mean
The latest move in Marks and Spencer Group (LSE:MKS) shares comes as investors focus on expectations for improved half year profits and resilience following last year's cyber attack.
Recent discussion around the retailer has centred on the Food division's contribution, the Fashion, Home & Beauty segment's sales trends and upcoming investor updates that may clarify how those themes translate into financial performance.
Over the past year, Marks and Spencer Group has seen a 25.5% year to date share price return and a 1 month share price gain of 8.79%. The 3 year total shareholder return of 91.13% and 5 year total shareholder return of 119.32% point to momentum that investors now appear to be reassessing in light of expectations for stronger half year profits and steady progress after last year's cyber attack.
Scan beyond Marks and Spencer Group and identify other retailers showing similar momentum for your own shortlist with the 14 high quality undervalued stocks.
After this run in Marks and Spencer Group, the debate now turns to price. Is the stronger outlook already in the £4.12 share price, or does the recent momentum still leave headroom?
Most Popular Narrative: 7% Undervalued
On the most followed view, Marks and Spencer Group is worth £4.45 a share versus the £4.12 last close. This puts the focus squarely on whether its heavy investment in stores, automation and technology can convert into the cash flows that view assumes.
The expanded structural cost out programme, which has already delivered about £390m of repeatable savings and now targets £600m between FY 2022/23 and FY 2027/28, is intended to reduce operating expenses and leave more of each pound of sales dropping through to net margins and earnings.
See why 80 investors see Marks and Spencer Group as 7% undervalued.
Result: Fair Value of £4.45 (UNDERVALUED)
Still, the Marks and Spencer Group story can be knocked off course if International keeps shrinking or if heavy spending on store rotation and automation fails to lift profit meaningfully.
Find out about the key risks to this Marks and Spencer Group narrative.
Another View: What Marks and Spencer Group’s P/E Is Telling You
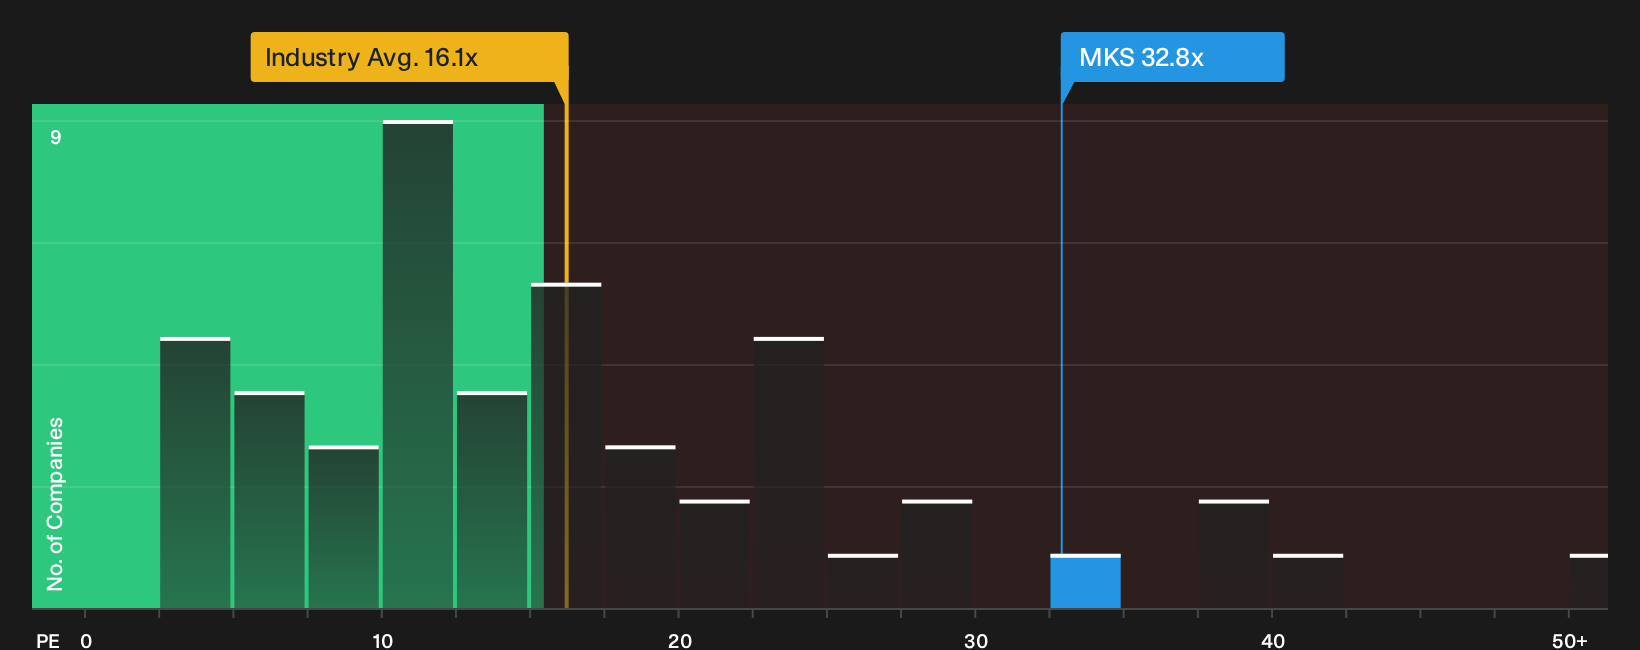
The earlier fair value of £4.45, which framed Marks and Spencer Group as undervalued, leans heavily on future cash flows and margin improvement. The P/E picture is tougher. At 32.8x, the shares trade at roughly double the European Consumer Retailing industry on 16.1x and well above peers on 18x, even if that premium sits closer to the fair ratio of 36.7x. That combination points to a richer entry price and less room for disappointment than the first model suggests. Which scenario feels closer to your own expectations for the business?
See what the numbers say about this price in more detail with the See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Sentiment around Marks and Spencer Group is clearly mixed, with optimism and unease pulling in opposite directions. Consider reviewing the figures independently, then weigh up the 2 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Marks and Spencer Group?
If Marks and Spencer Group has sharpened your focus on opportunity, do not stop here. Use targeted screeners to turn raw data into a focused watchlist fast.
- Target potential value by reviewing the 14 high quality undervalued stocks that combine quality fundamentals with prices that may not fully reflect their financial strength.
- Strengthen your defence by scanning the 5 resilient stocks with low risk scores that score well on resilience so short term volatility is less likely to derail your plan.
- Get ahead of the crowd by checking the 5 high quality undiscovered gems where solid fundamentals have yet to attract broad attention from the wider market.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com