


BNCCORP (OTCPK:BNCC) Stock Shrugs Off Q3 Earnings Momentum
BNCCORP just dropped its Q3 2026 scorecard, and the share price barely flinched. The stock slipped only 0.3% to about US$29.90, even though earnings per share landed at roughly US$0.85 and quarterly net income reached about US$3.0 million. For a regional bank, that profit line is the real story. The market reaction looks muted compared with what the income statement is signaling, which suggests investors are still anchored to BNCCORP’s weak multi year earnings record rather than the firmer profit picture in this latest quarter.
Impressed that BNCCORP is finally printing solid quarterly profit but still uneasy about its uneven multi year earnings history? Use our screening list to compare that pattern against regional banks and financials in the list of solid balance sheet and fundamentals stocks (24 results).
Q3 2026 Earnings Summary
- Revenue (Q3 2026 vs. Q3 2025): US$11.314 million vs. US$10.091 million (up about 12.1%)
- Net Income (Q3 2026 vs. Q3 2025): US$3.02 million vs. US$2.633 million (up about 14.7%)
- Basic EPS (Q3 2026 vs. Q3 2025): US$0.85 vs. US$0.74 (up about 14.6%)
- Net Interest Margin, NIM (Q3 2026 vs. Q3 2025): 3.85% vs. 3.74% (slightly higher NIM)
Accounting profit is one thing, but investors who care about what BNCCORP is really worth often focus on the cash coming through the door and how consistently it shows up. Put BNCCORP's recent cash generation under the microscope and the stock could be a mild 9% undervalued.
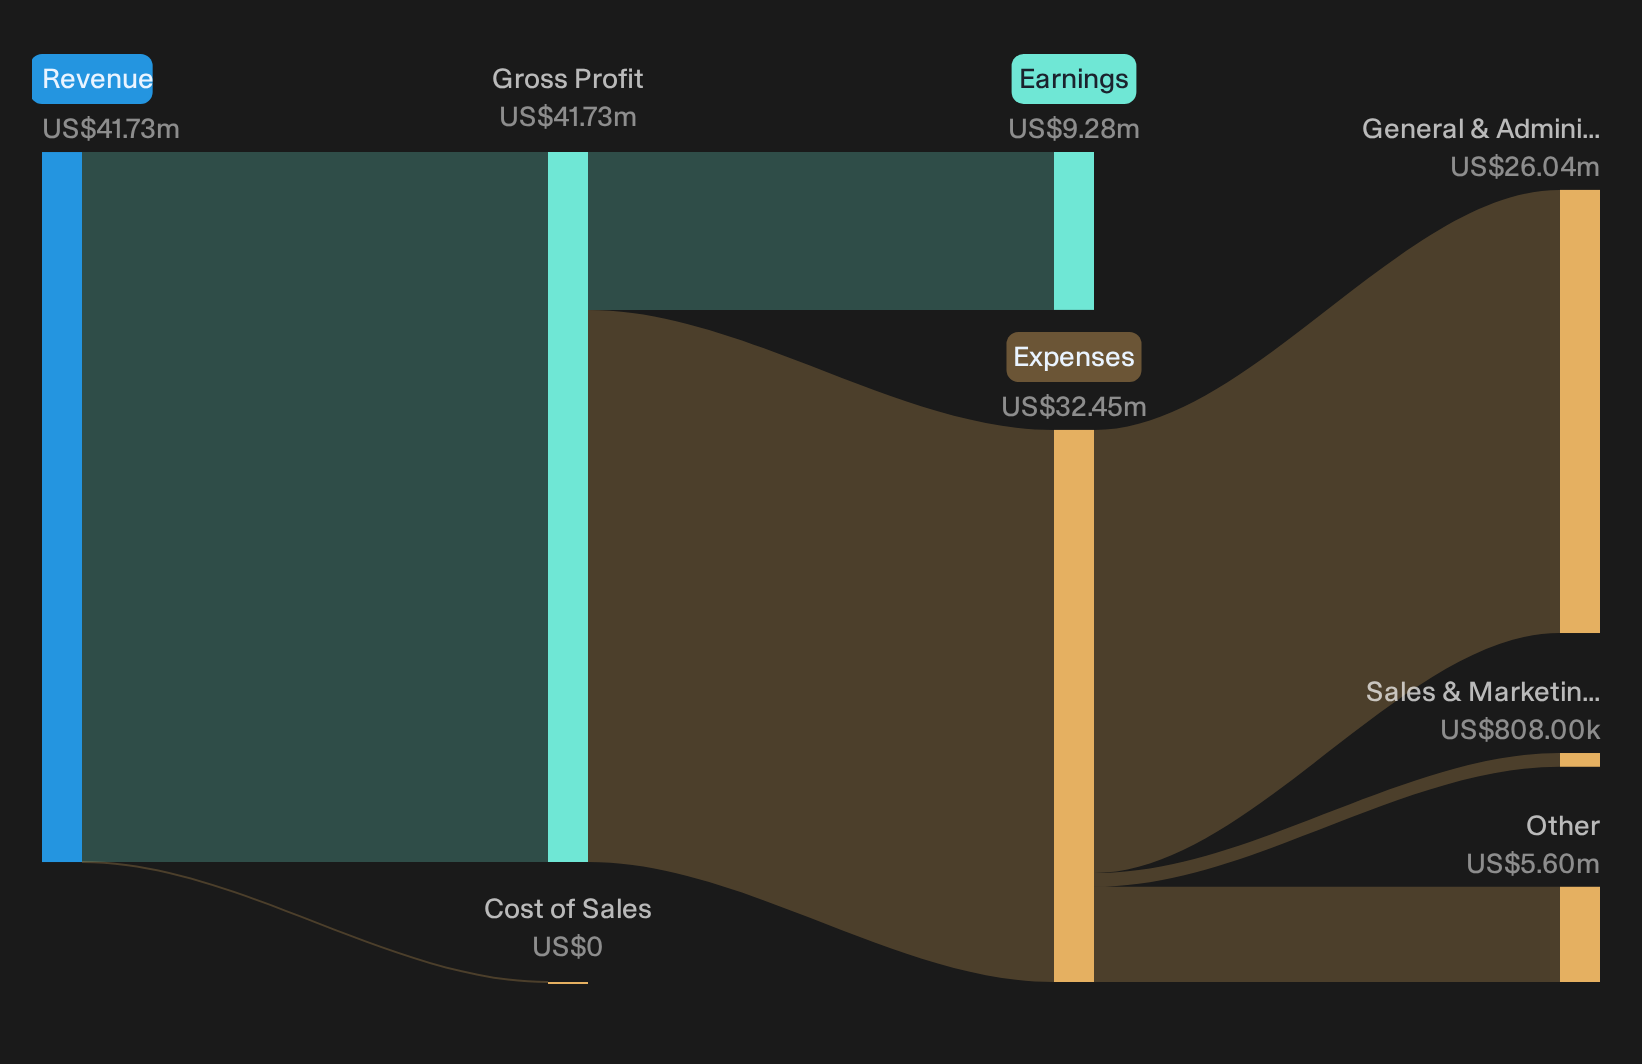
BNCCORP earnings give bulls some footing
For anyone leaning optimistic on BNCCORP as a relationship driven community bank, this quarter offers some backing. Revenue, net income and basic EPS all moved in the same upward direction, which supports the idea that the core franchise can still grind out higher earnings. A slightly higher net interest margin, or NIM, suggests the lending and deposit mix is not slipping under current rate conditions. The share price reaction has been muted so far, so sentiment looks slower than the income statement to recognize the steadier profit trend.
BNCCORP risks remain in focus for skeptics
Bears still have ammunition. The stock is down over the past 90 days even with this profitable quarter, which shows lingering concern about regional bank risk and BNCCORP’s uneven record. A small move in NIM and modest earnings progress do not erase questions about how resilient credit quality and the balance sheet would be if sector stress returns. The long term share price drift suggests investors still treat the bank as vulnerable to swings in confidence, even when the latest quarter reads well on the surface.
After a 5 year stretch where earnings declined about 19% per year, it is fair to ask if BNCCORP’s current stability is fragile. Before assuming this quarter fixes the story, review our independent risk analysis for BNCCORP which shows 1 important warning signHunt For Underappreciated Earnings Power
BNCCORP just showed how a cleaner quarter can coincide with a quiet share price. The real opportunity sits in finding stocks that could be undervalued before the crowd catches up.
- Company 1 - 32% below our estimate - supplies large-scale AI superclusters when single cloud providers approach capacity limits.
- Company 2 - 23% below our estimate - wires and outfits hyperscale data centers as operators secure capacity for future compute demand.
- Company 3 - 28% below our estimate - equips utilities and defense programs with diagnostic and RF testing gear during grid and fleet upgrades.
Those are three of them. See the full list of 30 companies trading below our fair value estimates →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com