


How Raised Revenue Guidance Will Impact Quanta Services Stock Investors
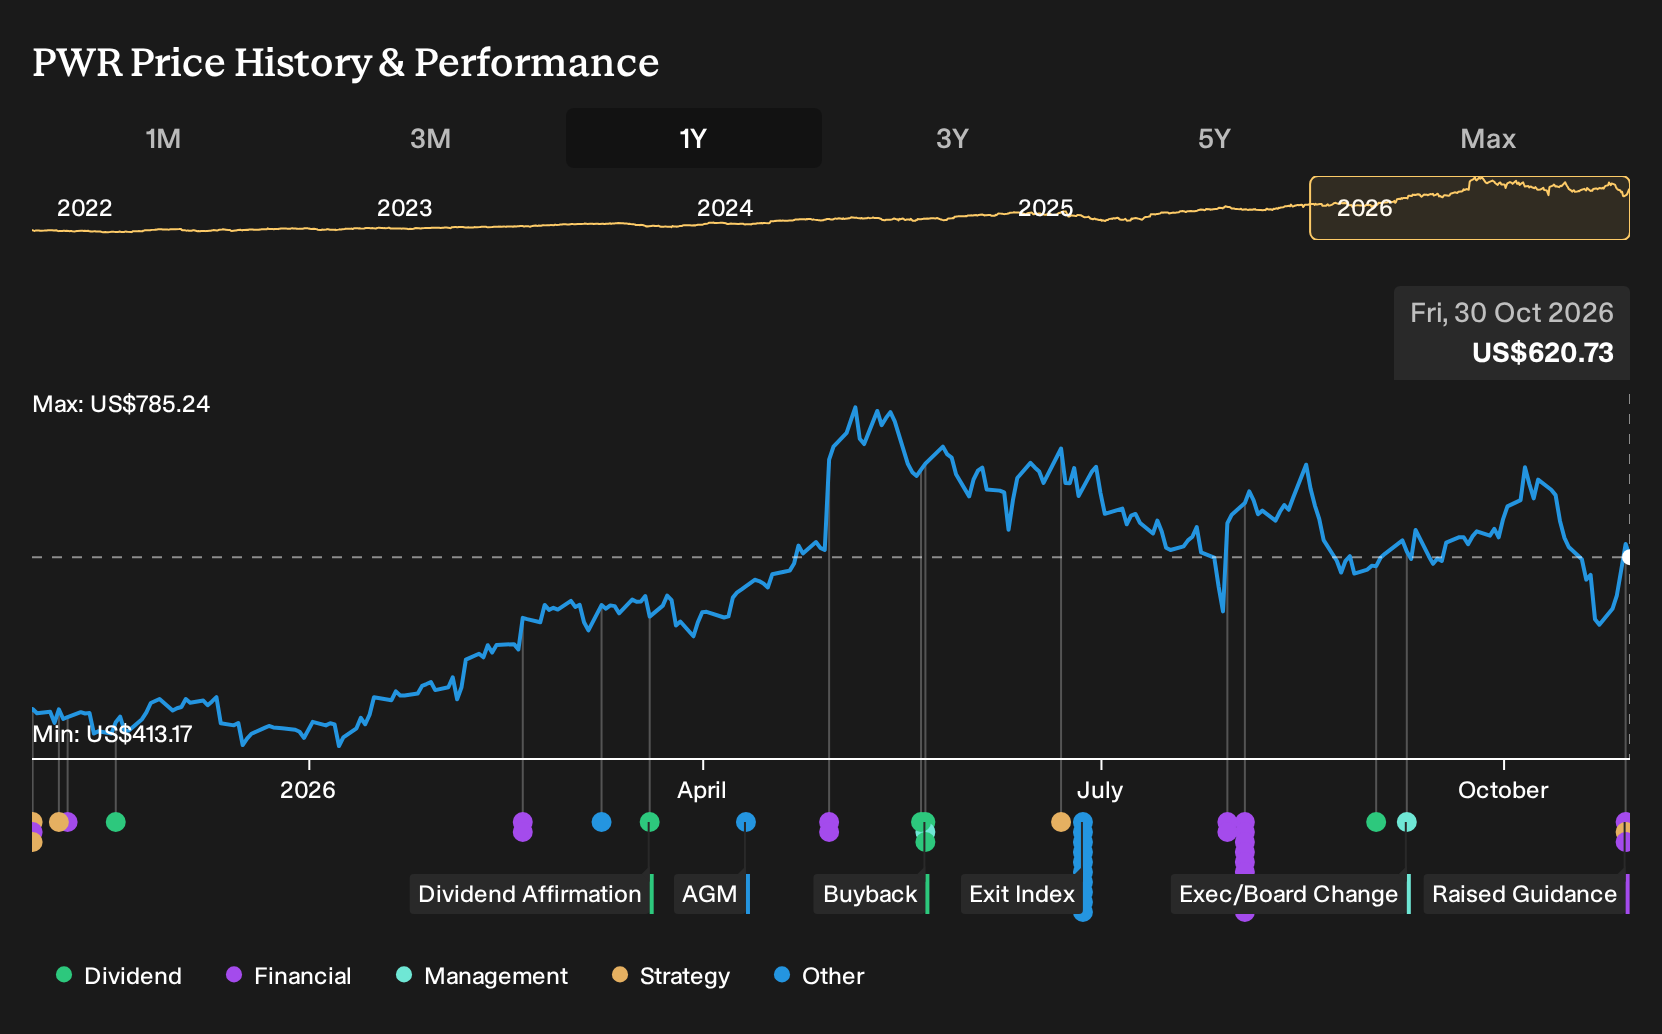
- Quanta Services reported third quarter 2026 sales of US$12,014.88 million and net income of US$694.86 million, and subsequently raised full year 2026 revenue guidance to a range of US$41.3 billion to US$41.6 billion.
- Management highlighted disciplined use of capital for potential acquisitions alongside record earnings, indicating a focus on both organic execution and inorganic growth capacity.
- This review considers how Quanta Services' investment narrative aligns with the raised 2026 revenue guidance and what that may imply for investors.
Scan how Quanta Services fits into the grid build out theme and compare it with a curated group of infrastructure plays in our 41 power grid technology and infrastructure stocks for your next round of ideas.
Quanta Services Investment Narrative Recap
To own Quanta Services, you need to believe the grid build out, data center power and utility upgrade work can support a large, complex backlog without eroding execution quality. The raised 2026 revenue guidance reinforces that demand is strong. The key near term swing factor is whether this higher run rate can be delivered cleanly on large projects already in motion.
The biggest risk has not really shifted. Expectations keep ratcheting up while the stock already trades on a rich P/E and carries meaningful debt. Any stumble in converting backlog into steady, high quality earnings could matter more now that guidance and investor focus sit at a higher bar.
The most relevant update here is the higher 2026 revenue outlook to US$41.3b to US$41.6b, which is about US$1.9b above the prior midpoint. That move effectively locks in a tougher execution hurdle, since investors will now track whether Quanta Services can sustain recent Q3 scale across the full year without sacrificing profitability or cash conversion.
This sharper revenue bar feeds directly into existing catalysts. Data center and high voltage work, transformer capacity expansion and prior acquisitions all need to keep contributing reliably to hit those numbers. If grid modernization or renewables projects slow, or integration work around deals proves bumpy, the raised guidance could shift from support to a pressure point for the stock.
Quanta Services' current analyst framework points to revenues of US$54.6b and earnings of US$2.7b by 2029, based on expectations for 18.4% yearly revenue growth and an earnings increase of about US$1.4b from US$1.3b today.
Uncover why Quanta Services' fair value indicates a 24% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
One alternate view focuses on acquisition risk. Before this guidance hike, the most cautious analysts were penciling in about US$50.9b of 2029 revenue and US$2.5b of earnings, and arguing that Quanta Services might struggle to keep deal heavy growth from diluting margins. That is a much harsher story. Use it as a prompt to explore multiple narratives before you decide how this new outlook could reshape your own view.
Explore 4 other Quanta Services fair value estimates, including one that suggests as much as 19% downside from the current price.
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Quanta Services research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Quanta Services. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Quanta Services' overall financial health at a glance.
Looking for more Quanta Services style investment ideas?
If the Quanta Services story has you thinking about where else the market might be mispricing risk and reward, it makes sense to widen the lens. The Simply Wall St Screener can help you quickly surface other opportunities that match the type of financial profile you prefer.
- For investors who care most about valuation and business quality, run a fresh search through 30 high quality undervalued stocks and see which candidates line up with your checklist.
- If capital preservation and balance sheet strength come first for you, filter the market using our list of solid balance sheet and fundamentals (24 results) to spot companies with sturdier financial footing.
- For those building an income oriented portfolio, scan the 5 dividend fortresses and compare yields, coverage, and consistency before committing new cash.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com