


What Raised Guidance Means For PayPal Shares
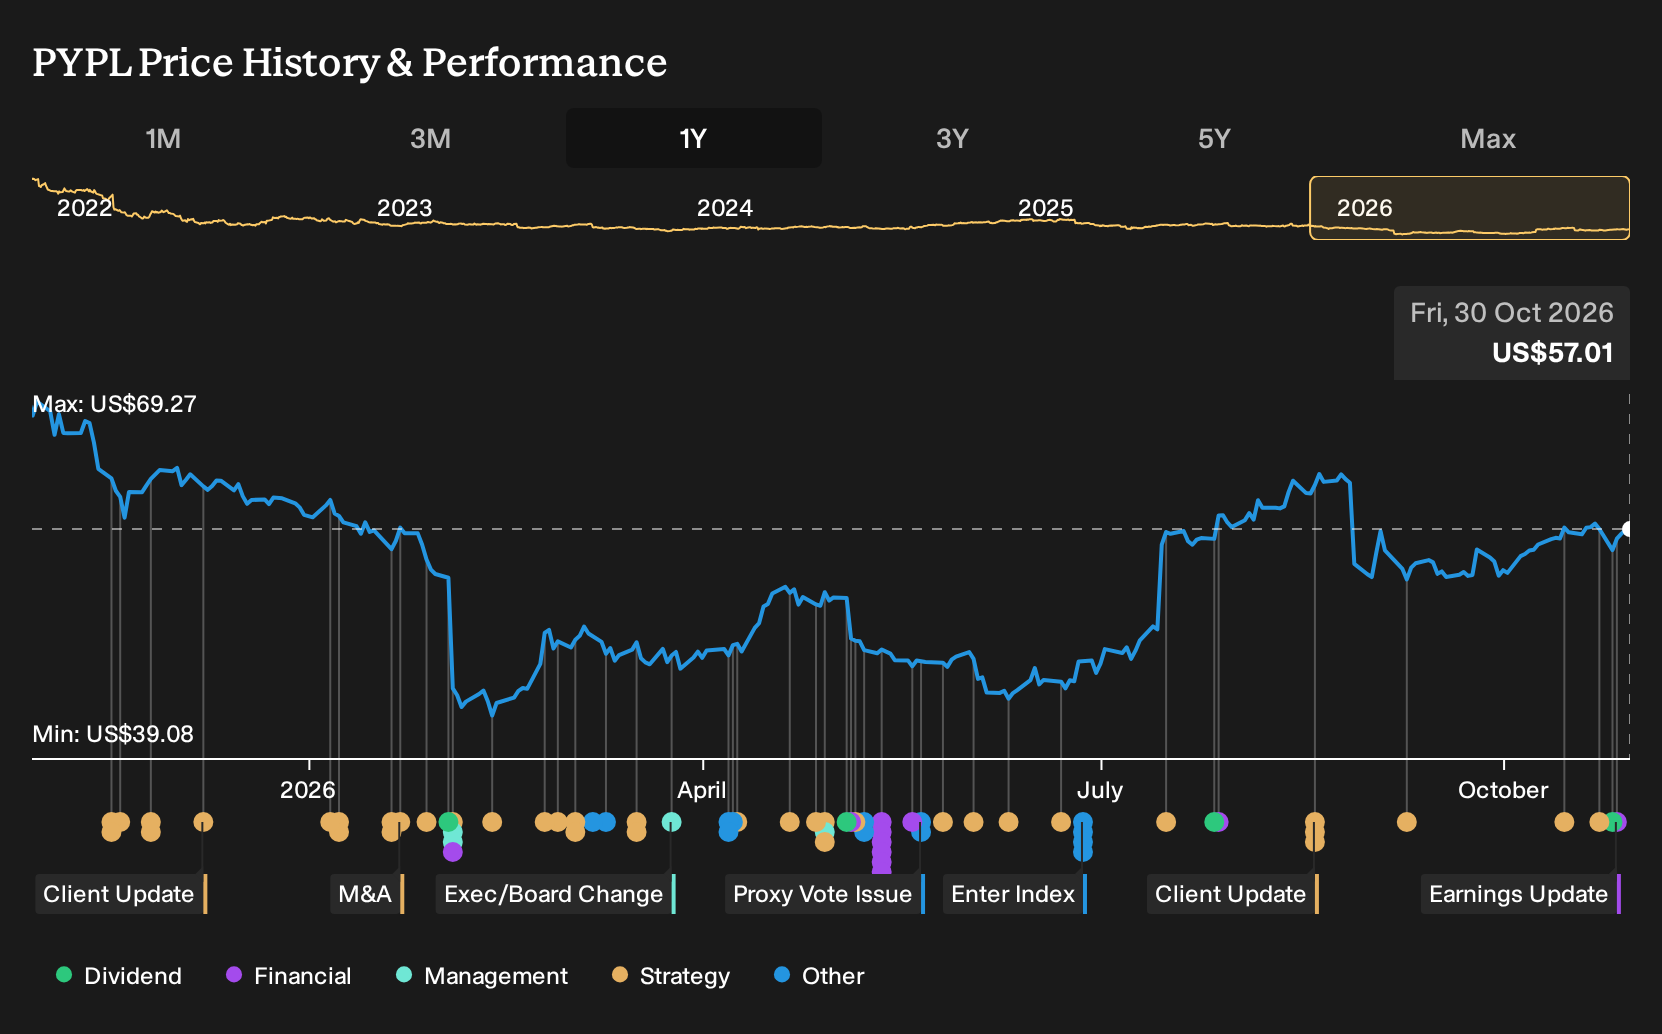
- PayPal Holdings reported Q3 2026 basic EPS from continuing operations of US$1.26, slightly below US$1.31 a year earlier, and affirmed a US$0.14 quarterly dividend payable in December 2026.
- The new payout collaboration announced by LianLian Global extends PayPal and Venmo into global creator and contractor payouts. This aligns with management’s focus on new payment flows and deeper Venmo engagement.
- We will look at how PayPal's raised full year earnings guidance shapes the investment narrative and long term execution priorities.
Scan how PayPal Holdings fits within the broader payments story by sizing it up against hand-picked peers in our 30 high quality undervalued stocks with solid cash generation and balance sheets.
PayPal Holdings Investment Narrative Recap
To own PayPal Holdings, you need to believe the payment platform can keep shifting activity into higher engagement areas like financial services, Venmo and Braintree, while holding the line on profitability. Q3 2026 EPS from continuing operations of US$1.26, slightly below last year, and nine month EPS easing, point to pressure on margins even as management raised adjusted earnings guidance.
The key near term swing factor is execution on cost savings and product rollout without slowing growth in branded checkout or newer flows such as BNPL and creator payouts. The main operational risk remains mix shift into lower take rate products, which could squeeze transaction margins if efficiency gains or new services do not offset that drag.
The LianLian Global partnership looks most relevant for understanding catalysts after this earnings update. It plugs PayPal and Venmo into global creator and contractor payouts, tying directly into management’s push on new payment flows and deeper Venmo engagement, and widening how the wallets can be used beyond peer to peer transfers.
For you as an investor, the operational question is whether these new routes for PayPal Holdings can scale fast enough to matter for total payment volume and transaction margin dollars, while cross border and tariff related headwinds linger. If execution is slow or payout economics are thin, the mix shift risk toward lower take rate volumes stays front of mind despite the raised earnings guidance.
PayPal Holdings' narrative projects US$38.7b revenue and US$4.7b earnings by 2029. This assumes 4.3% yearly revenue growth and an earnings decline of US$0.2b from US$4.9b today.
Uncover why PayPal Holdings' fair value appears to be broadly aligned with its current price.
Exploring Other Perspectives
One alternate view on PayPal Holdings puts far more weight on pressure from lower take rate flows such as Venmo and Braintree. The most cautious analysts were penciling in only 3.1% annual revenue growth and earnings of about US$4.0b by 2029 before this news. That is a much harsher story. Use this earnings update, the dividend affirmation and the LianLian Global deal as a prompt to compare those assumptions with your own and explore how opinions can shift as new data arrives.
Explore 23 other PayPal Holdings fair value estimates, including one that suggests it could be worth just $56.92.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your PayPal Holdings research is our analysis highlighting 2 key rewards that could impact your investment decision.
- See our latest analysis for PayPal Holdings. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate PayPal Holdings' overall financial health at a glance.
Looking For More Investment Ideas Beyond PayPal Holdings?
If this earnings story has you rethinking where PayPal Holdings fits in your portfolio, it can help to weigh it up against other businesses with very different risk and return profiles. The Simply Wall St Screener gives you a structured way to search for stocks that match your preferences on quality, valuation, income and resilience.
- If you want income to be a bigger part of your returns, scan a shortlist of higher yielding companies that our tools flag as potential 5 dividend fortresses.
- If capital preservation matters most to you right now, filter for steadier businesses through a 29 resilient stocks with low risk scores that focuses on resilience scores first and excitement second.
- If you prefer to hunt earlier in the story, look for businesses with strong fundamentals that are not widely followed yet by checking out a curated 19 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com