


Preformed Line Products (PLPC) Stock Looks Expensive After Strong Earnings Growth
Preformed Line Products has seen its share price climb sharply over recent years, yet the stock has pulled back in recent weeks, which puts fresh focus on whether the current valuation is supported by its earnings power. With investors weighing that swing against strong reported profit growth, the question now is how much of that earnings story is already reflected in today's price.
- Over the past 5 years, Preformed Line Products has delivered a share price gain of about 321.3%. This means a lot of past success is already on the line when you assess what its earnings can justify from here.
- Recent reports of an 18% rise in sales together with 70% earnings per share growth suggest the business may support expectations for stronger profitability. This matters directly for any earnings based valuation.
- There is a second opinion on Preformed Line Products worth weighing. See what analysts think Preformed Line Products's shares could be worth.
The issue now is whether the stock's current price, after a long run and a recent pullback, is justified by the earnings investors are paying for today.
If you are weighing Preformed Line Products against other opportunities with similar quality filters, it can help to compare it with companies in our our screener containing 19 high quality undiscovered gems.
Has Preformed Line Products Run Too Far on Earnings?
The P/E ratio is a useful anchor for Preformed Line Products because earnings currently sit at the center of the story investors are paying for. On this measure, the stock trades around 24.3x earnings, which is below both the Electrical industry average near 31.2x and a peer group closer to 32.1x. That gap suggests the market is assigning a lower earnings multiple to PLPC than to many similar businesses in its sector.
Despite the recent report of 18% sales growth and 70% EPS growth in Q3 2026, the share price still carries a P/E above what a tailored model would expect given Preformed Line Products' financial profile. As a result, the stock screens as overvalued on this framework. Investors weighing that premium against the lower multiple versus the broader Electrical group need to decide whether the recent profitability strength justifies paying above what the Fair Ratio implies. Explore the numbers behind Preformed Line Products's P/E valuation.
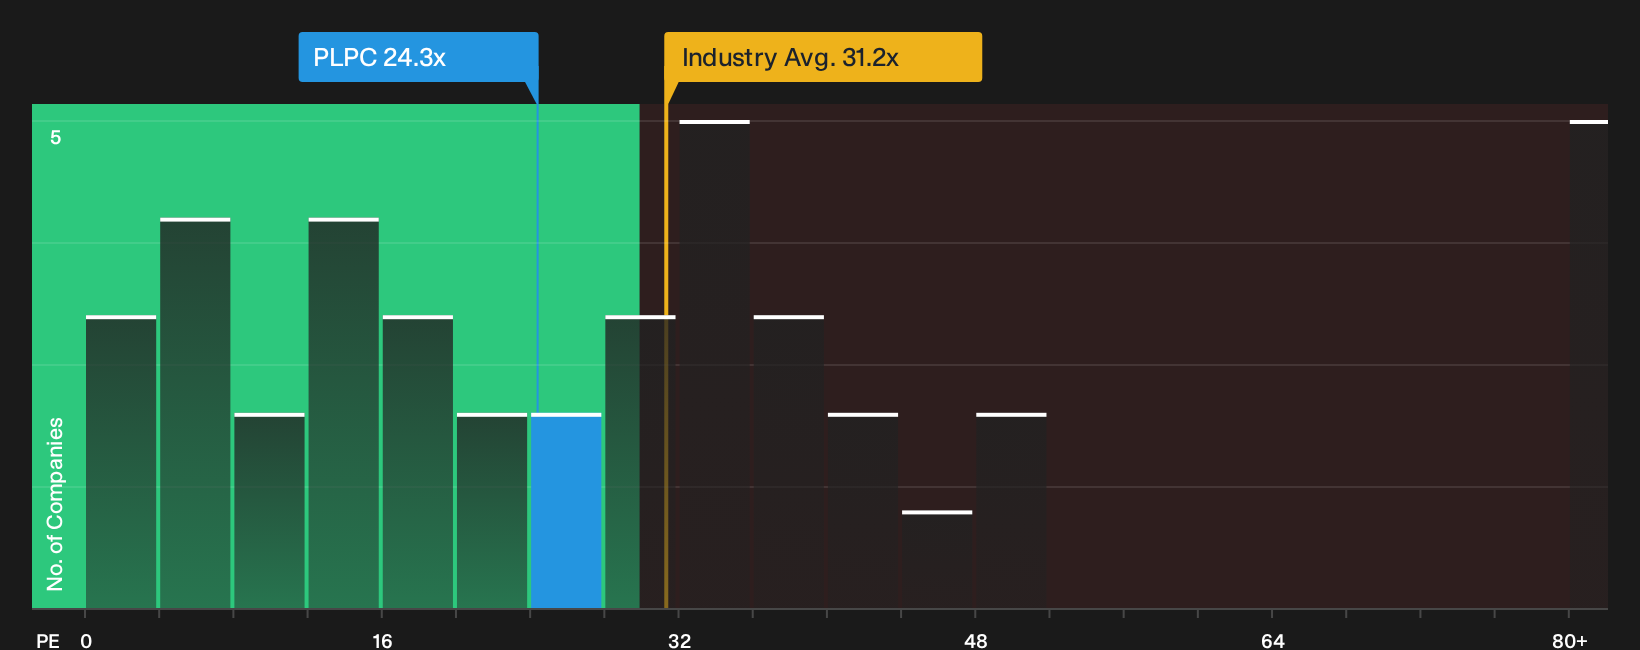
The Preformed Line Products Narrative: What Would Justify Today's Price?
Narratives pick up where the P/E question for Preformed Line Products' valuation leaves off by spelling out which paths for growth, margins and earnings would need to hold for the shares to be worth significantly more or less than today. Each scenario is framed as a thesis about the business that can be revisited over time, so you can see how the underlying assumption set holds up as new information comes through on Simply Wall St's Community page.
A clear, number driven Narrative on Preformed Line Products helps you spell out whether the recent 18% sales rise and 70% EPS growth plausibly support the current P/E, so your expectations for profitability and valuation are on record before the next set of results. With those assumptions written down, you can later compare the story you had in mind with how Preformed Line Products' actual execution on growth, margins and cash generation unfolds.
Share your own Narrative for Preformed Line Products and set out the assumptions behind your valuation.
One more open question on Preformed Line Products
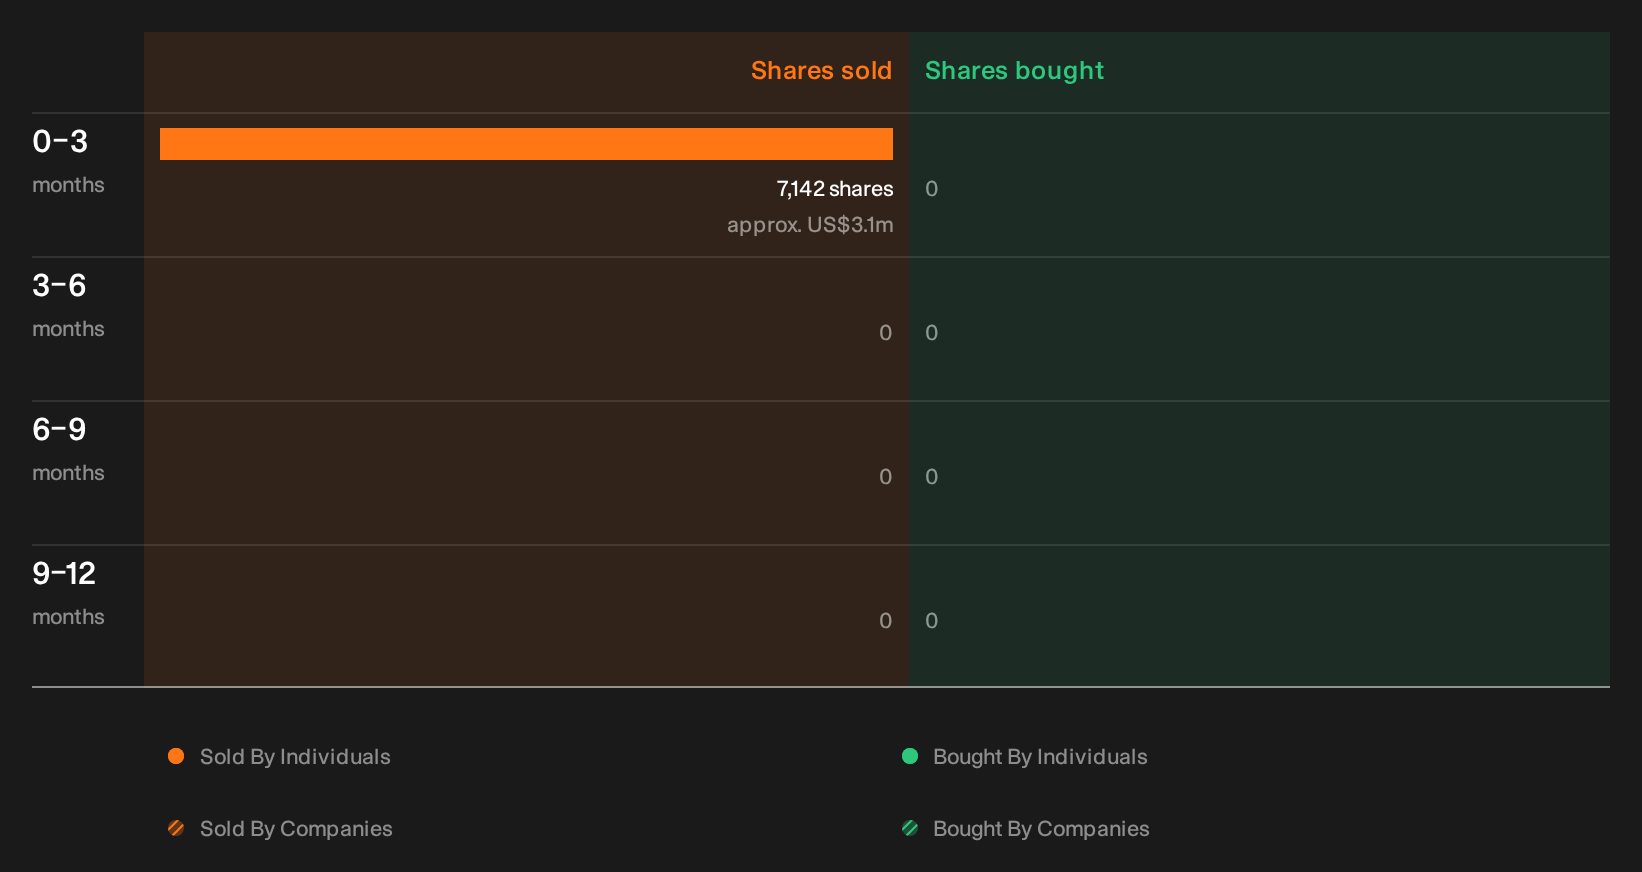
Valuation only goes so far when recent share disposals by people inside Preformed Line Products have been flagged, and the who, how much and why still need closer inspection from you. See the recent insider selling flagged for Preformed Line Products.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com