


Wix.com (WIX) Stock May Be A Bargain Following New AI Health Push
Wix.com has seen its share price under pressure in recent years, and that raises a straightforward question for you as an investor. Is the current US$77.03 price tag reasonably lined up with what the business is generating in sales today?
- Over the past 5 years, the stock has fallen 60.4%. This puts the focus squarely on whether the current valuation still fits the underlying revenue base.
- A new partnership with K Health to embed PatientGPT into personalized web experiences may support expectations that Wix.com can deepen its role with larger enterprises and potentially influence how investors think about future sales growth and customer mix.
- There is a second opinion on Wix.com worth weighing. See what analysts think Wix.com's shares could be worth.
The issue now is whether Wix.com’s current share price is adequately supported by its sales when set against the Fair Ratio benchmark.
If this question about Wix.com has you rethinking how you look at revenue based pricing, it can help to compare it with companies surfaced by 30 high quality undervalued stocks.
Is Wix.com a Bargain on Sales?
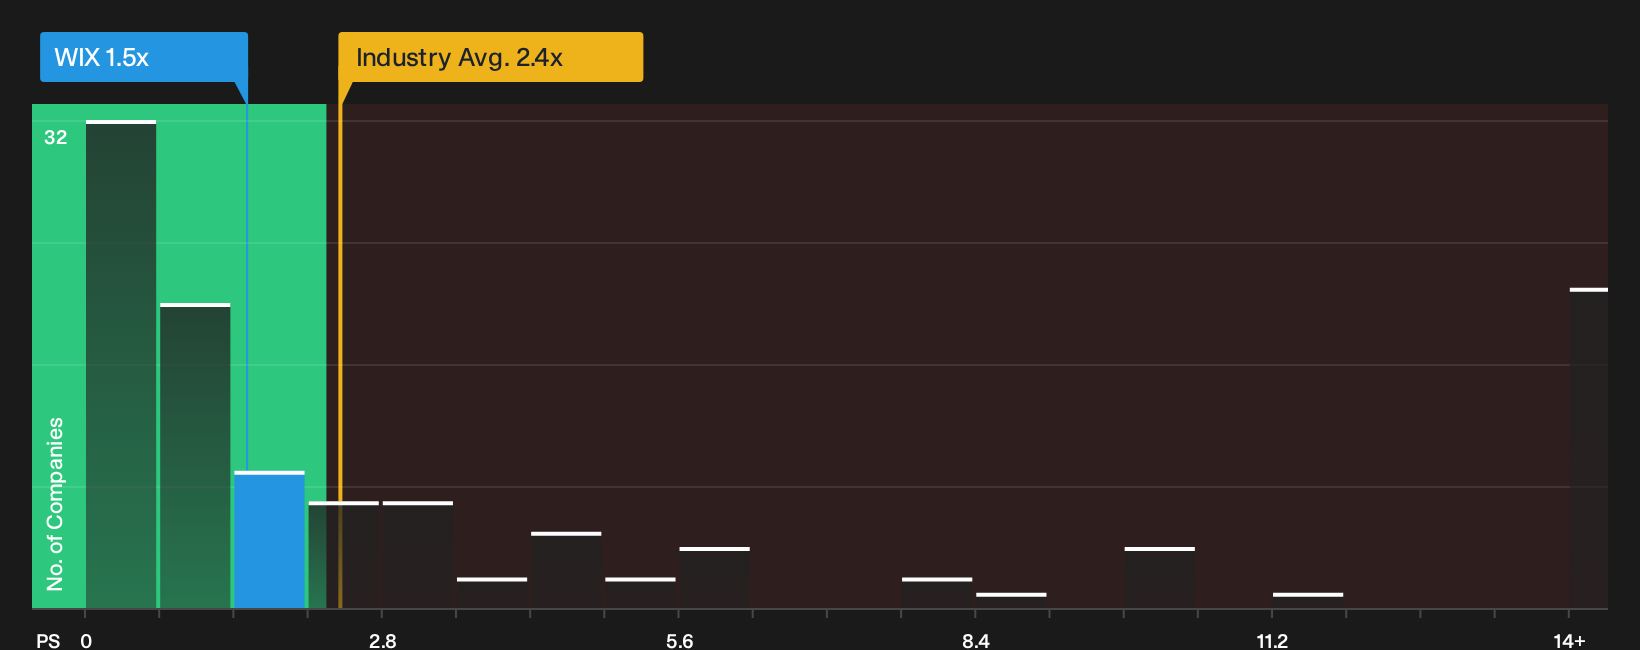
The P/S ratio fits Wix.com well because investors often look at revenue first for a business that has focused heavily on product and platform scale. At a current P/S of 1.5x, the stock changes hands at a lower sales multiple than the broader IT industry average of 2.4x and the peer group at 2.8x.
Despite the recent K Health partnership putting fresh attention on Wix.com and its enterprise ambitions, the present 1.5x P/S also sits below the level you might expect given its profile on growth, margins, size and risk. That spread against the Fair Ratio benchmark signals that investors are pricing Wix.com at a discount on sales and leaves room for you to weigh whether its business quality justifies that gap. Explore the numbers behind Wix.com's P/S valuation.
The Wix.com Narrative: What Would Justify Today's Price?
Narratives for Wix.com pick up where that P/S puzzle leaves off. They spell out which combinations of future growth, profitability and earnings power would need to play out for the share price to look materially higher or lower than today. They sit on Simply Wall St’s Community page so you can see the story behind a single valuation output and then watch, over time, whether real results keep matching that script.
Community views on Wix.com split around how much credit to give its AI stack and BASE44 unit economics compared with legal and cost pressure.
Bull case: 34% undervalued
"The numbers and current valuation suggest that the market assigns limited value to Wix.com’s AI stack, Base44 growth and capital return program..."
Discover why this Narrative puts Wix.com at 34% undervalued.
Bear case: 54% overvalued
"Bearish analysts expect Wix.com to struggle to translate higher AI-related operating expenses and legal or regulatory scrutiny into durable margin expansion..."
Explore why this Narrative puts Wix.com at 54% overvalued.
One more angle on Wix.com that deserves your attention
Before you focus only on what Wix.com looks like on sales and community views, it helps to know that Simply Wall St’s broader checks have flagged specific areas of concern that some investors may want to unpack. Take a closer look at 3 warning signs before settling on a valuation.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com