


Updated 2026 Outlook Could Be A Game Changer For American Tower Stock (AMT)
- American Tower reported third quarter 2026 results with basic earnings per share from continuing operations of US$1.65 compared with US$1.82 a year earlier, while year to date basic EPS from continuing operations reached US$5.35 versus US$3.65 in the prior year period.
- The company also updated its 2026 full year outlook, projecting total property revenue between US$10.785b and US$10.865b and net income attributable to common stockholders between US$3.183b and US$3.238b, which gives investors clearer visibility into how tower and data center operations are currently feeding through to the income line.
- We will look at how American Tower's updated 2026 net income guidance reframes the longer term investment narrative around towers and AI infrastructure.
Use American Tower's earnings and AI infrastructure story as a starting point to scout similar tower and data center plays through our hand picked 54 AI infrastructure stocks built for this theme.
American Tower Investment Narrative Recap
To hold American Tower, you need to believe its mix of global towers and CoreSite data centers can keep turning rising data usage and AI workloads into resilient tenant billings and rent. The recent quarter showed lower quarterly EPS than a year ago but much higher EPS year to date, which keeps the core thesis tied to assets and contracts rather than one three month period.
The key near term swing factor is still carrier spending and amendment activity on existing towers, along with leasing in AI oriented data halls. The biggest risk remains higher interest costs and refinancing needs. The updated 2026 outlook gives more clarity on property revenue and net income but does not remove that funding pressure.
The most relevant update for this story is the new 2026 guidance, with American Tower now expecting total property revenue between US$10.785b and US$10.865b and net income attributable to common stockholders of US$3.183b to US$3.238b. Those figures frame what the current tower portfolio and CoreSite footprint might deliver as 5G densification and AI traffic evolve.
For you, that guidance sits against known pressure points such as churn events, slower carrier upgrades or any cooling in AI related demand for CoreSite. It also needs to be weighed against higher interest expense, since debt is not well covered by operating cash flow. In the short term, execution on leasing and disciplined capital allocation remain practical catalysts to watch.
Analysts expect American Tower’s revenue to reach US$12.5b and earnings to come to US$3.8b by 2029. This assumes revenue growth of 4.4% per year and an earnings increase of about US$0.4b from US$3.4b today.
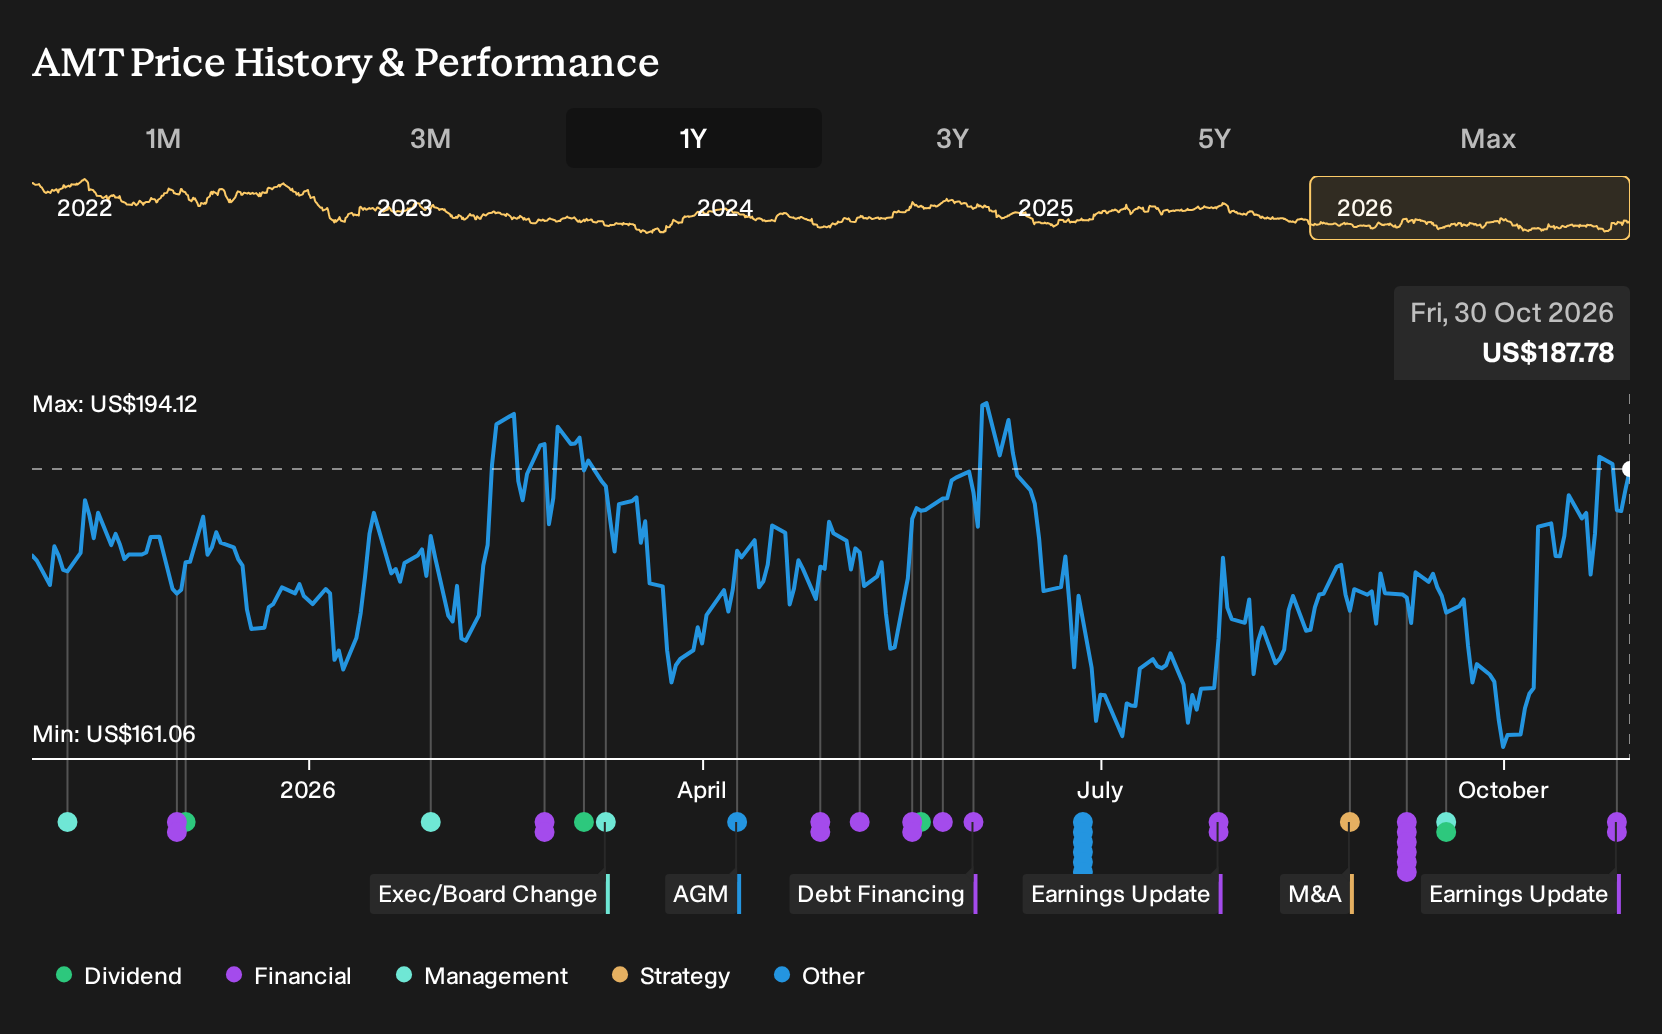
Uncover why American Tower's fair value indicates a 15% potential upside to its current price that could narrow quickly as sentiment around towers and AI infrastructure improves.
Exploring Other Perspectives
Four fair value estimates from the Simply Wall St Community cluster between about US$215.70 and US$304.34 per share, so you see both cautious and very optimistic takes on American Tower. Compare those views with refinancing risk and AI related data center demand, then explore how sharply opinions can diverge before you commit fresh capital.
Explore 3 other American Tower fair value estimates, including one that suggests it could be worth just $215.70.
Form Your Own Verdict
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your American Tower research is our analysis highlighting 5 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for American Tower. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate American Tower's overall financial health at a glance.
Looking For More Investment Ideas Beyond American Tower?
Once you have formed a view on American Tower, it can help to widen the lens and compare it with other opportunities that match your risk tolerance, income goals, and balance sheet preferences. Use the Simply Wall St Screener to line up similar profiles side by side so you can see where American Tower fits in your broader watchlist.
- If you want potential upside but still care about quality, scan a curated set of attractively priced businesses with resilient fundamentals through our 30 high quality undervalued stocks.
- For investors who prize income stability, focus on companies that pair robust cash generation with substantial payouts using this curated group of 5 dividend fortresses.
- If capital preservation comes first for you, start with sturdier balance sheets and steadier risk profiles by filtering through a focused 29 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com