


How Investors Are Reacting To Autoliv (ALV) Softer Third Quarter Earnings
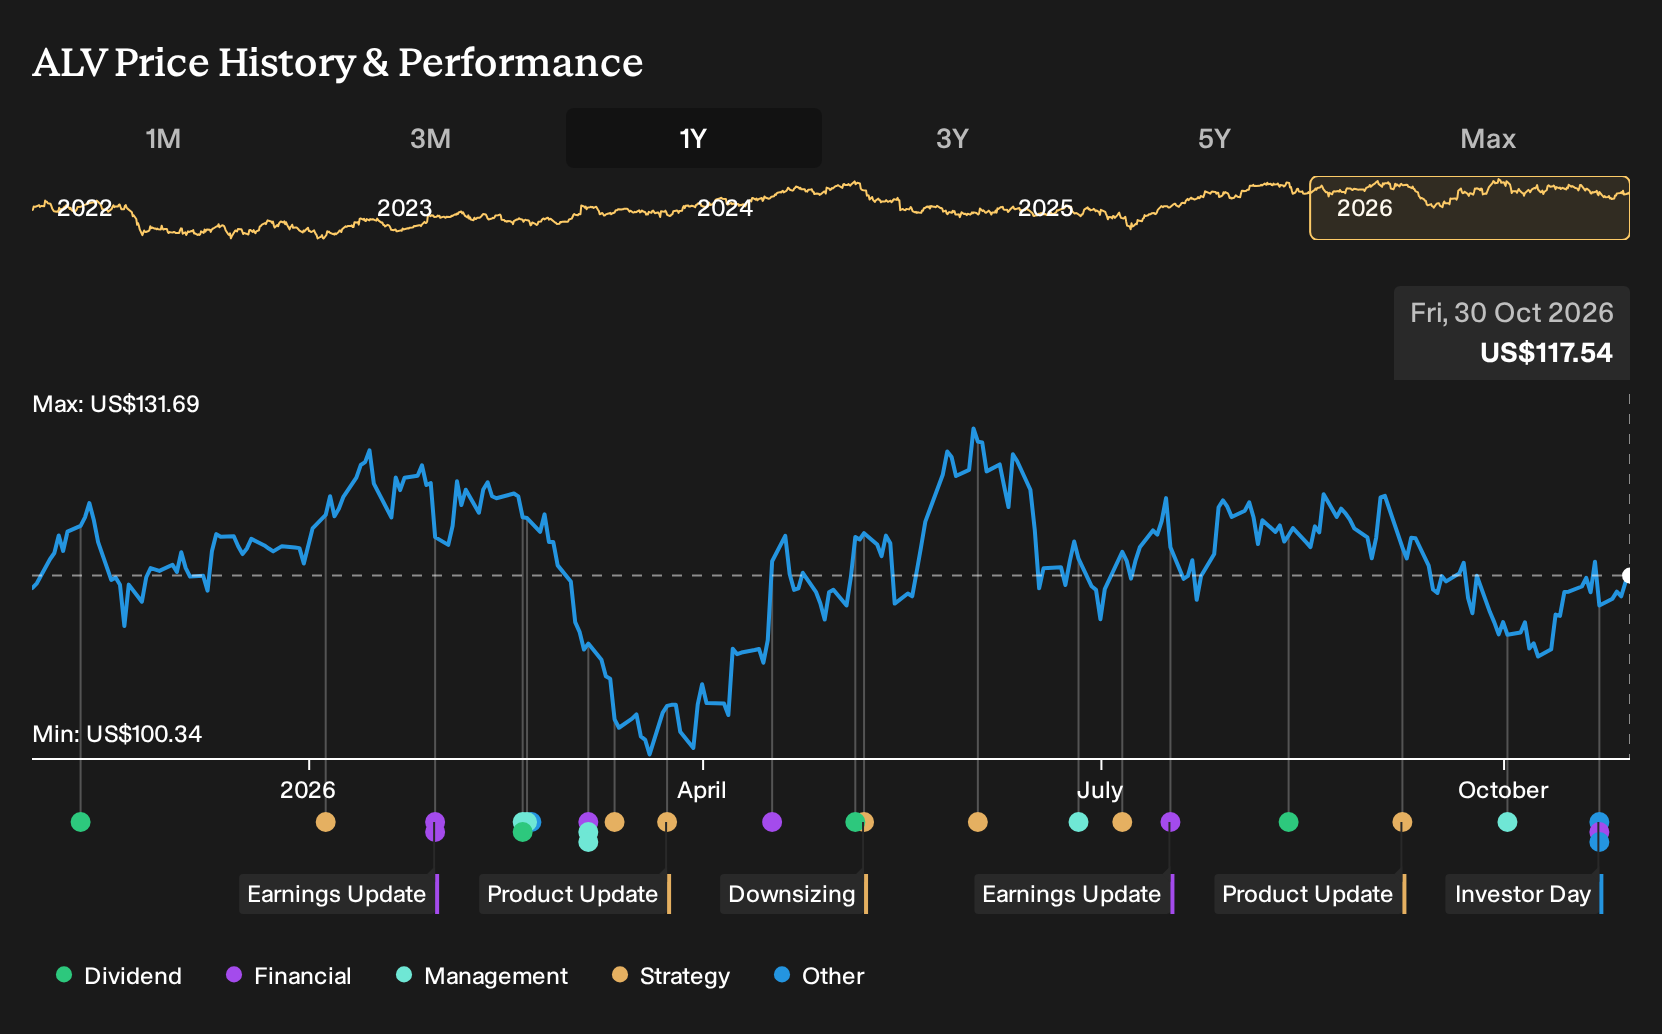
- Autoliv reported third quarter 2026 revenue of US$2,693 million, with net income of US$155 million and diluted EPS from continuing operations of US$2.13, compared with the same period in 2025.
- For the first nine months of 2026, Autoliv generated US$8,249 million in revenue. Net income and EPS trailed the prior year, indicating ongoing profit pressure despite higher year-to-date sales.
- We now examine how Autoliv's investment narrative is affected by softer earnings per share despite slightly higher nine-month revenue.
Autoliv Investment Narrative Recap
To own Autoliv, you need to believe that demand for vehicle safety content in regions like China and India, along with new mobility products, can support a healthier earnings profile over time. The latest quarter complicates that story a bit. Revenue for both the quarter and nine months stayed solid, but earnings per share softened, which keeps the focus firmly on execution.
Right now the key short term swing factor is whether Autoliv can offset raw material cost pressure and protect margins while still funding growth projects. The biggest risk is that higher input costs and a weaker mix in key markets persist into upcoming quarters. If that happens, the latest earnings trend could prove more than a temporary bump.
The third quarter 2026 earnings release is the central data point to weigh here. Autoliv reported quarterly revenue of US$2,693 million and net income of US$155 million, with diluted EPS from continuing operations of US$2.13. For the first nine months, revenue reached US$8,249 million, but net income and EPS lagged the prior year despite higher sales.
This pattern ties directly back to the main catalysts and risks. Softer EPS alongside higher turnover suggests that raw material headwinds, product mix, or pricing are affecting profitability, which matters for the thesis that cost savings and efficiency can lift margins. Until there is a cleaner conversion from revenue to earnings, that pressure on profitability remains the central execution watchpoint.
Autoliv's current analyst blueprint points to revenue of US$11.9b and earnings of US$1.0b by 2029. This projection lines up with a forecast annual top line growth rate of 2.4% and an earnings increase of about US$357m from US$643.0m today.
Uncover why Autoliv's fair value indicates a 15% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
Four fair value views from the Simply Wall St Community cluster between US$103 and about US$228, which signals a wide span of expectations around Autoliv. You are seeing that gap before the latest earnings data. When you add in raw material cost pressure and execution on safety content growth, the case clearly benefits from multiple viewpoints.
Explore 3 other Autoliv fair value estimates, including one that suggests potential upside of up to 94% from the current price.
The Verdict Is Yours
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Autoliv research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Autoliv. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Autoliv's overall financial health at a glance.
Looking For More Investment Ideas Beyond Autoliv?
If the Autoliv story has sharpened your thinking and you want to line it up against other opportunities, a quick pass through the Simply Wall St Screener can help you compare different types of stocks side by side.
- If income stability matters to you, consider high yield options screened as 5 dividend fortresses that may suit a more cash focused portfolio.
- If resilience and downside protection are higher on your checklist, review companies highlighted as 29 resilient stocks with low risk scores to see which profiles better fit your risk tolerance.
- If financial strength is the priority, focus on businesses filtered as a list of solid balance sheet and fundamentals (24 results) and compare their fundamentals with what you see at Autoliv.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com