


United Bancorporation Of Alabama (UBAB) Q3 Results Raise Margin Reset Questions
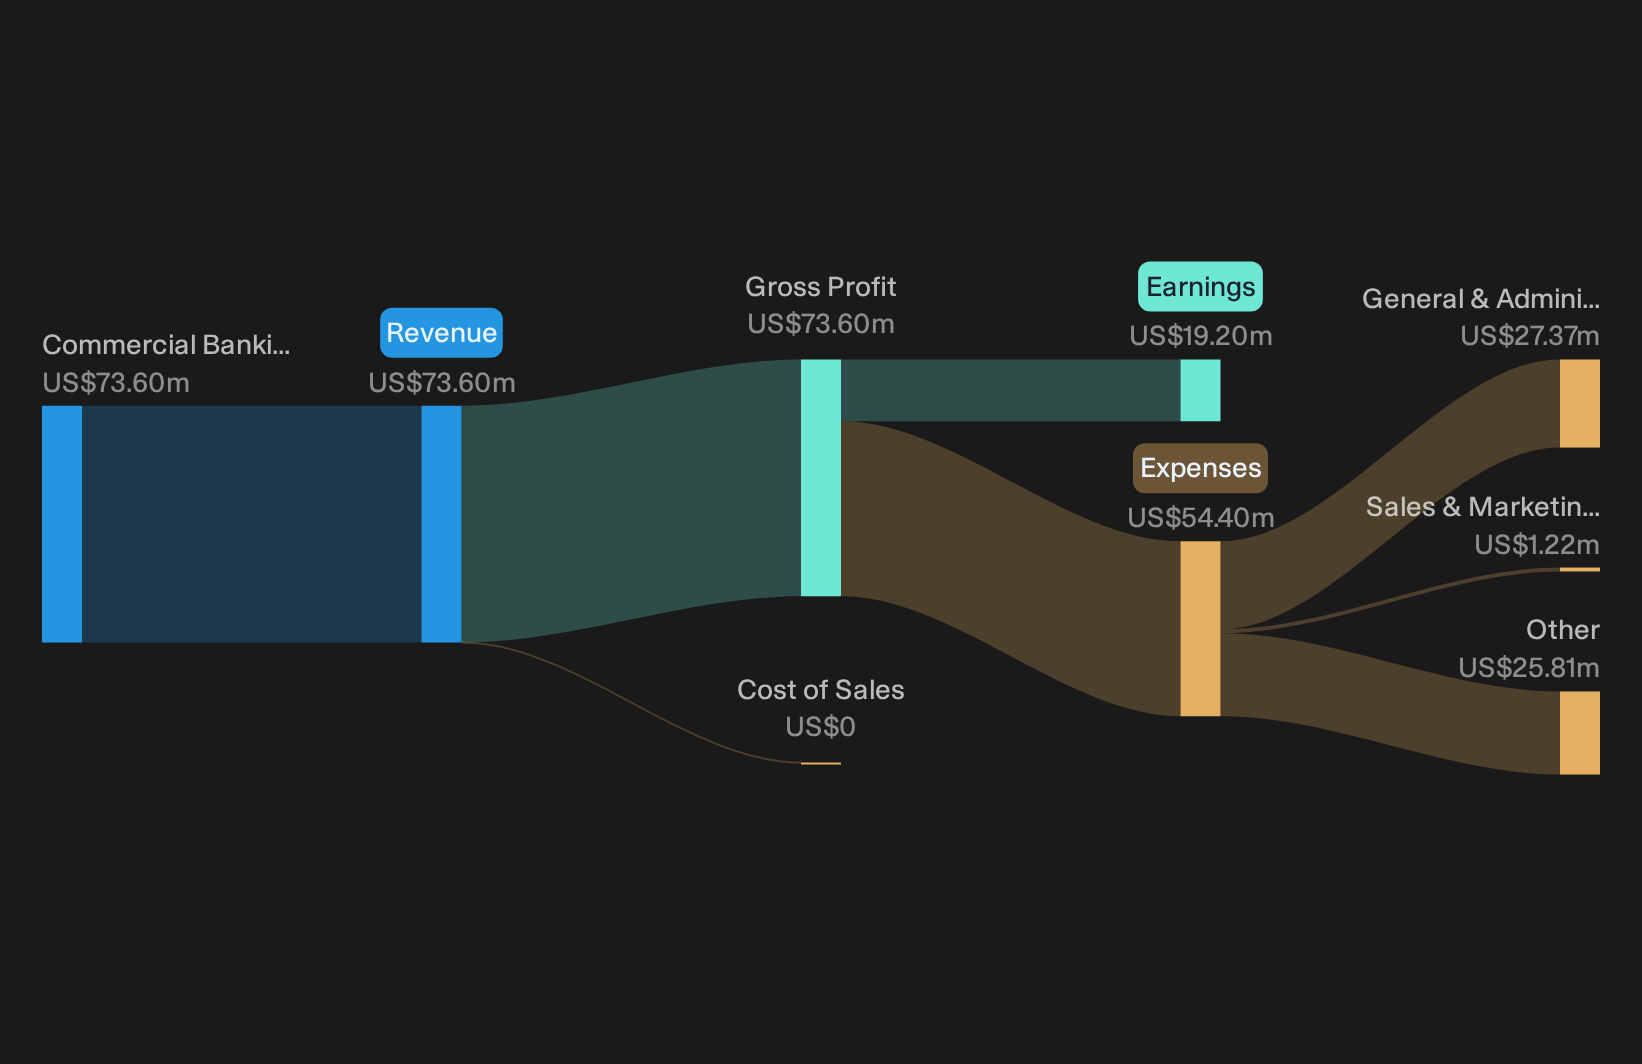
United Bancorporation of Alabama stock went into the Q3 2026 report flat on the day and only modestly positive over the past quarter. However, the latest numbers carry more weight than the quiet tape suggests. The headline is a clear profit squeeze. Quarterly earnings per share of US$1.53 landed well below the prior quarter’s US$1.91, while net income stepped down to US$4.67 million on revenue of US$18.53 million. In the short term, that points to pressure. Over a multi year view, the key question is whether this margin compression is temporary or a reset in how this bank now earns.
Concerned that United Bancorporation of Alabama’s softer Q3 earnings signal a deeper profitability reset rather than a blip? Compare this bank’s profile against our screener of list of solid balance sheet and fundamentals stocks (24 results).
Q3 2026 Earnings Summary
- Revenue (Q3 2026 vs. Q3 2025): US$18.53 million vs. US$17.95 million (modest top line increase)
- Net Income (Excl. Extra Items, Q3 2026 vs. Q3 2025): US$4.67 million vs. US$4.21 million (higher quarterly profit in dollar terms)
- Basic EPS (Q3 2026 vs. Q3 2025): US$1.53 vs. US$1.29 (earnings per share moved higher year on year)
- Net Interest Margin, or NIM (Q3 2026 vs. Q3 2025): 4.59% vs. 4.58% (essential lending spread remained essentially unchanged)
UBAB’s share price sits well below one DCF estimate. Ask Charlie what makes United Bancorporation of Alabama look undervalued.
United Bancorporation of Alabama, bullish signals under the surface
For investors leaning positive on United Bancorporation of Alabama, the story starts with resilience. Q3 net income of US$4.67 million and EPS of US$1.53 both sit above last year’s quarter, and revenue of US$18.53 million is higher than Q3 2025. Net interest margin, or NIM, at 4.59% is effectively flat year on year, which hints at a stable core lending spread. Nine month earnings of US$16.0 million versus US$13.5 million last year reinforce the idea that this traditional community banking model is still generating higher profit in aggregate.
Short term profit squeeze keeps the bear case alive
The cautious view on United Bancorporation of Alabama focuses on the more recent squeeze. EPS stepped down from US$1.91 in Q2 to US$1.53 in Q3, and net income followed the same direction on a sequential basis, even with slightly higher revenue. That points to pressure on costs, mix, or credit that is not visible in headline NIM, which stayed around 4.6%. A flat share price into the Q3 release and a slightly weaker 30 day return suggest investors are not treating this as a clean upward trend.
With earnings negative over the most recent year, yet the P/E still anchored to trailing profits, the real question is whether United Bancorporation of Alabama’s balance sheet can comfortably support this profile. Check the full financial health analysis of United Bancorporation of Alabama stockHunt For Quiet Mispricings
United Bancorporation of Alabama’s mixed quarter highlights how far the market rates its earnings power. The real opportunity sits in stocks that could be undervalued before sentiment aligns with their fundamentals.
- Company 1 - 46% below our estimate - targets larger LED display upgrades for sports venues, commercial signage, and transit hubs.
- Company 2 - 23% below our estimate - captures growing orders to build power and wiring infrastructure for hyperscale data centers without using long term debt.
- Company 3 - 38% below our estimate - expands coconut based drinks from niche shelves into mainstream while adding private label contracts and new distribution partnerships.
Three companies from the same screener. Open the full list of 30 companies trading below our fair value estimates →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com