


Why Comfort Systems USA Stock Is In Focus For US Fab Construction
A potential US$45b Solidigm NAND mega fab in Upstate New York has turned chip infrastructure from background noise into front-page capital spending. That kind of buildout can reshape order books for contractors, equipment specialists, and industrial suppliers, and missing the right exposure can feel costly. This article walks through three US Semiconductor Fab Construction & Infrastructure Beneficiaries stocks that look especially exposed to this news and explains what investors should watch.
The three stocks covered next are only a small slice of the opportunity set, as the full screen surfaced 91 more US Semiconductor Fab Construction & Infrastructure Beneficiaries with equally detailed stories that are not covered in this article. To see the broader field and identify which contractors and industrial players best fit your own criteria, head straight into the US Semiconductor Fab Construction & Infrastructure Beneficiaries screener
Comfort Systems USA (FIX)
Comfort Systems USA appears closely tied to the semiconductor buildout theme because its mechanical, electrical and plumbing expertise aligns with the highly technical systems required by fabs and advanced data centers.
Comfort Systems USA provides mechanical and electrical installation, renovation and maintenance for complex buildings across the US. Mechanical Services generate about US$8.8b of revenue and Electrical Services around US$3.8b. The business, valued at roughly US$43.1b, is positioned for fab related MEP work.
"Record backlog of US$14.1b, up strongly year over year and sequentially, points to continued conversion of contracted work into future revenue and earnings as Comfort Systems USA executes higher value mechanical and electrical projects."
It is important to consider how that earnings path might change if a single pressure on high tech project demand and pricing starts to shift.
If that single pressure point on high tech work proves less fragile than it looks, the full narrative for Comfort Systems USA shows how backlog, pricing and risk could be decoupling in Comfort Systems USA's favor.
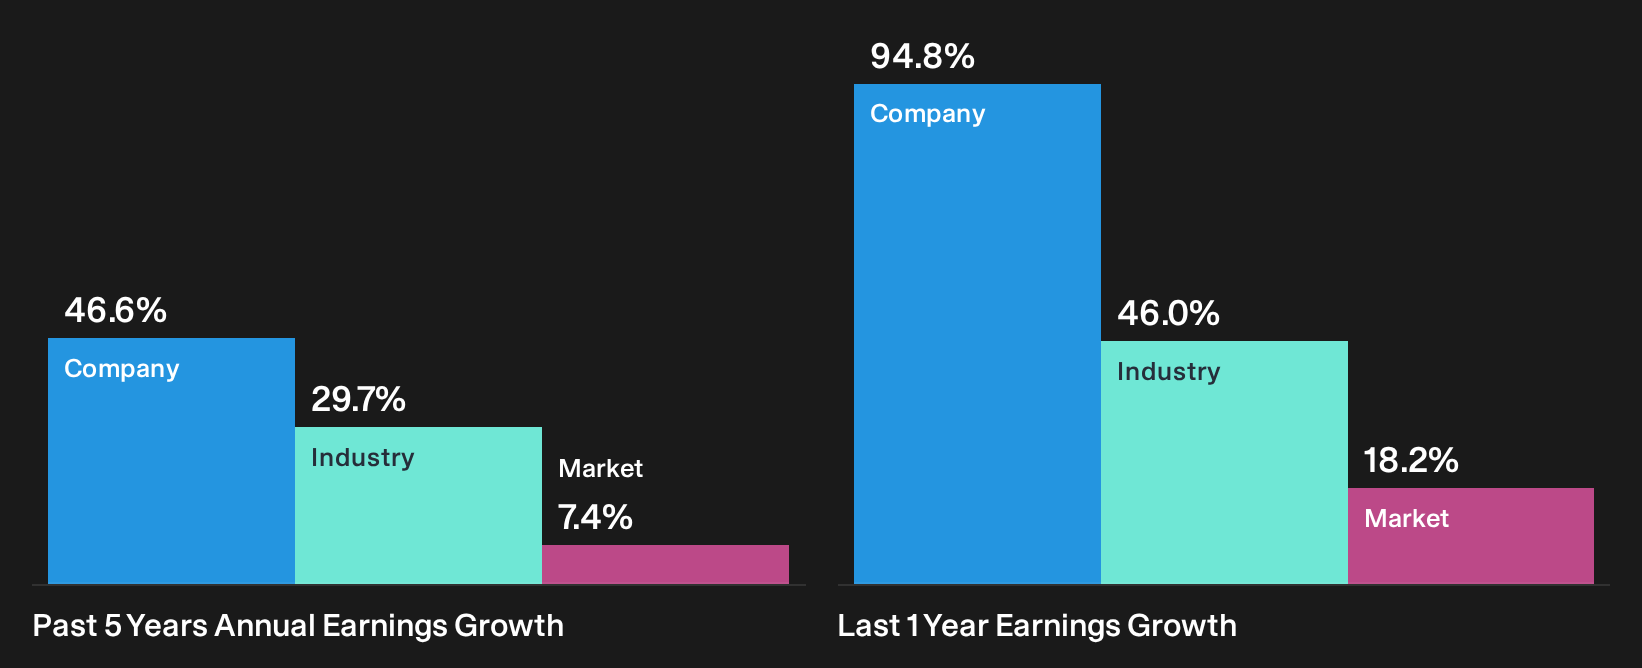
MasTec (MTZ)
MasTec plugs directly into the semiconductor fab buildout story through the less glamorous but essential pieces: the power lines, pipes, roads and fiber that let a multi billion dollar site actually run. This is where the company’s scale and backlog come into focus.
"Rapid acceleration in utility grid modernization, data center build outs and renewable energy investment continues to support MasTec’s record backlog of about US$21.4b and raised 2026 guidance."
What happens to MasTec’s earnings power if a single assumption about how that backlog converts into high quality margins starts to move?
MasTec is a US$14.8b infrastructure contractor focused on communications, power delivery, pipelines and clean energy projects that align with fab related site prep and utilities. Clean Energy and Infrastructure brings in about US$6.1b, Power Delivery US$5.2b, Communications US$3.4b and Pipeline Infrastructure US$2.7b.
If that conversion risk is what you keep circling, the full narrative for MasTec explains how MasTec’s backlog, margins and execution quality could be quietly accelerating.

Generac Holdings (GNRC)
Generac Holdings looks relevant to the semiconductor fab construction theme because fabs and AI heavy data centers need dependable on site and backup power, and this energy technology specialist sells exactly those systems across residential, commercial, industrial and data center markets. The stock is valued at about US$11.7b.
For investors watching how power reliability could become the tightest bottleneck for new fabs and AI data centers, Generac Holdings is worth attention because its scale in backup generation and energy storage directly touches that problem.
"Accelerating AI driven build outs of hyperscale and colocated data centers are now supported by Generac Holdings having about US$450m of expected 2026 data center revenue, a US$1.6b dedicated backlog, and multiple multiyear hyperscale agreements including an Amazon deal projected at about US$2.4b of deliveries in 2027 to 2028."
What matters next is how one unseen pressure on that data center opportunity shapes the balance between higher capacity, pricing power and actual earnings quality.
If that unseen pressure on data center demand is what you are trying to size, the full narrative for Generac Holdings explains in detail how Generac Holdings’ agreements and backlog might really interact.

Seeking Fresh Alternatives Before They Fly
New ideas often move first and move fast. By the time momentum reaches the headlines, the most attractive entry points can be gone. Review these fresh lists before the broader crowd and consider your options early.
- Spot income workhorses geared for staying power and use the 5 dividend fortresses to see which yields may still look interesting while prices have not fully caught up.
- Focus on real earnings momentum instead of stories and run through the 40 profitable AI stocks that aren't just burning cash to find AI players already turning hype into measurable cash flow.
- Track potential future grid winners early and review the 41 power grid technology and infrastructure stocks to narrow in on businesses connected to long term electricity and transmission upgrades.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com