


United States Lime & Minerals (USLM) Stock Slips As Q3 Results Face Margin Pressure
United States Lime & Minerals just posted Q3 2026 results that kept the profit engine humming while the share price flinched. The stock fell 2% on the first trading day after the release, even as basic earnings per share reached about US$1.33 on revenue of roughly US$106.2 million. That wobble looks more like investors reacting to a premium P/E of 23.9x than to any sudden crack in the limestone producer’s fundamentals. This sets up a clear sentiment versus numbers clash for you to judge.
Love that United States Lime & Minerals is still churning out earnings while revenue holds steady, but uneasy about paying a premium P/E for that consistency? Benchmark this setup against our 30 high quality undervalued stocks to see how other profitable stocks with stronger value credentials stack up.
Q3 2026 Earnings Summary
- Revenue (Q3 2026 vs Q3 2025): US$106.2 million vs. US$102.0 million (up about 4.1%)
- Net Income, Excl. Extra Items (Q3 2026 vs Q3 2025): US$38.0 million vs. US$38.8 million (down about 1.9%)
- Basic EPS (Q3 2026 vs Q3 2025): US$1.33 vs. US$1.35 (down about 2.1%)
- Net Profit Margin, Trailing 12 Months (Latest vs Prior Year): 35.1% vs. 35.8% (a modest compression of about 0.7 percentage points)
Earnings look healthy, yet cash generation tells you more about what you are really paying for United States Lime & Minerals' future potential than a single quarter of profit ever can. If you focus on United States Lime & Minerals' cash flows instead of the headline EPS, the stock could be a slight 6% overvalued.
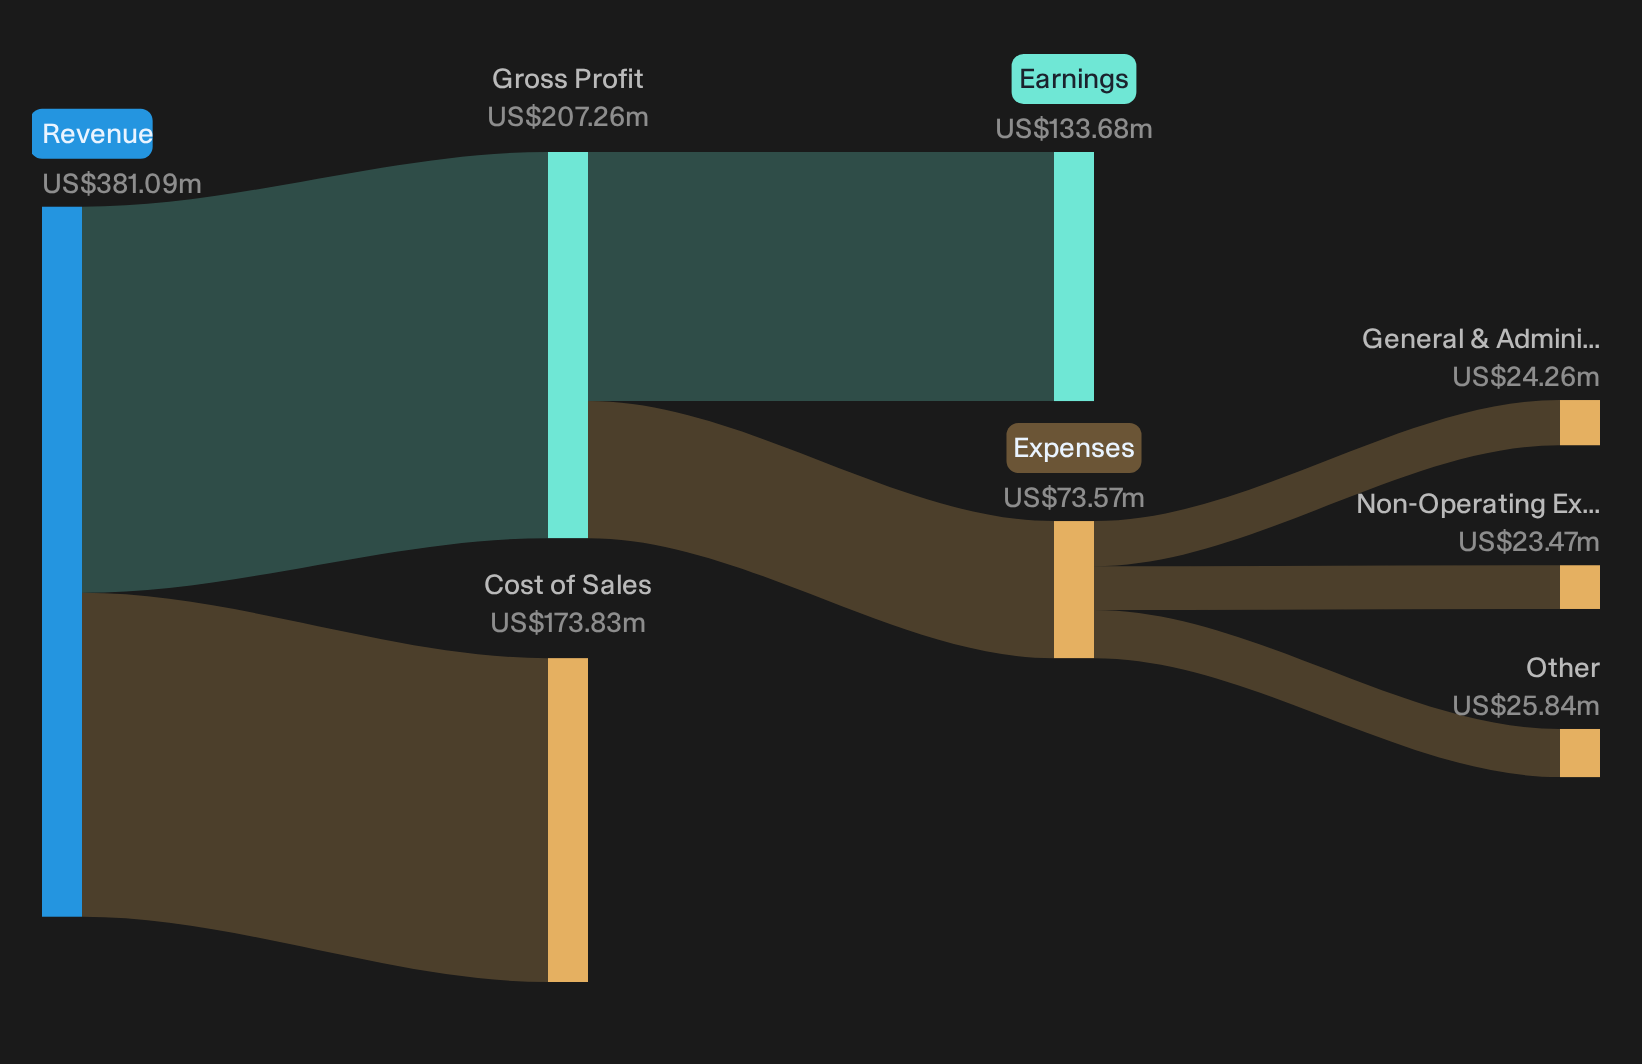
United States Lime & Minerals: Earnings Still Support the Optimists
For the bullish story, the latest quarter mostly holds up. United States Lime & Minerals lifted revenue about 4.1%, helped by steel demand, which fits the idea of an essential supplier tied to multiple end markets. Earnings per share softened slightly, yet profit margins on a trailing 12 month view remain above 35%, and the regular US$0.06 dividend stayed in place. For investors who view this as a steady industrial linked to infrastructure and environmental needs, the numbers still look consistent with a resilient, if not explosive, earnings profile.
Cost Pressures and Cyclicality Keep the Bear Case Alive
The cautious angle gets some support as well. Net income excluding extra items dipped about 1.9% and net margin compressed, reflecting higher diesel costs and production hiccups from the new Texas kiln. Those issues show how an asset heavy business can feel operating and integration friction even when demand is decent. Short term share performance has been choppy, with 7 day and 90 day returns both slightly negative, which fits a narrative that investors are still testing how much cost pressure this model can comfortably absorb.
After production setbacks at the new Texas kiln and significant insider selling, it is worth asking what else might be lurking. Review our risk analysis for United States Lime & Minerals which shows 1 important warning signHunt For Quiet Mispricings
United States Lime & Minerals just showed how resilient earnings can diverge from recent share price moves. The real opportunity sits in finding stocks that could be undervalued before the crowd catches up.
- Company 1 - 38% below our estimate - leverages trade-in subsidies and eco-focused policies to route used devices into higher margin refurbishment channels.
- Company 2 - 48% below our estimate - converts a backlog of large, higher margin contracts into cash while resolving costly legacy disputes.
- Company 3 - 40% below our estimate - uses long duration optical and solar supply agreements to secure demand from energy and data infrastructure builders.
That is three of the list. See all 30 potentially undervalued companies →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com