


Ameren (AEE) Could Be 5% Undervalued Following DOE Backed Grid Upgrade Win
Ameren’s SPARK-backed grid project sets the stage
Ameren (AEE) just moved into the spotlight after the U.S. Department of Energy picked Ameren Missouri, Ameren Illinois, and Pitch Aeronautics for SPARK-funded grid upgrades in Missouri and Illinois.
The project centers on higher capacity conductors and weather-based line ratings, with real-time sensors and software aimed at easing congestion, supporting demand growth, and improving the efficiency of Ameren’s existing transmission network.
On the market side, Ameren’s recent SPARK win lands at a time when momentum is already building. The company has a 30-day share price return of 11.23% and a year-to-date share price gain of 9.60%, backed by a 1-year total shareholder return of 11.43% and a 3-year total shareholder return of 54.32%.
Scan how Ameren’s grid push compares with other regulated utilities upgrading infrastructure by reviewing the hand picked 39 power grid technology and infrastructure stocks that are now riding similar transmission and power technology themes.
Ameren looks like a solid regulated utility with fresh SPARK-backed momentum in its grid plans. The real tension for investors now sits in the share price. How does that recent move stack up against the fundamentals?
Most Popular Narrative: 5% Undervalued
Ameren’s most followed valuation story points to a fair value of $116.81 versus the last close at $110.54, which frames the recent SPARK driven share move against a modest implied discount and puts the focus squarely on whether the long build program and load growth can keep earning their way into that gap.
Ameren's multi year generation build program, including more than 5 gigawatts of new solar, simple cycle gas, battery storage and the 2.1 gigawatt West Alton combined cycle facility expected in 2031, together with procurement of key turbines and long lead components, points to sustained regulated capital deployment that can expand rate base and, once in service, feed into revenue and earnings.
See why 3 investors see Ameren as 5% undervalued.
Result: Fair Value of $116.81 (UNDERVALUED)
Still, the Ameren narrative leans heavily on data center demand and more than US$71b of planned grid and generation projects that rely on consistent regulatory and capital market support.
Find out about the key risks to this Ameren narrative.
Another View: Ameren’s valuation through earnings multiples
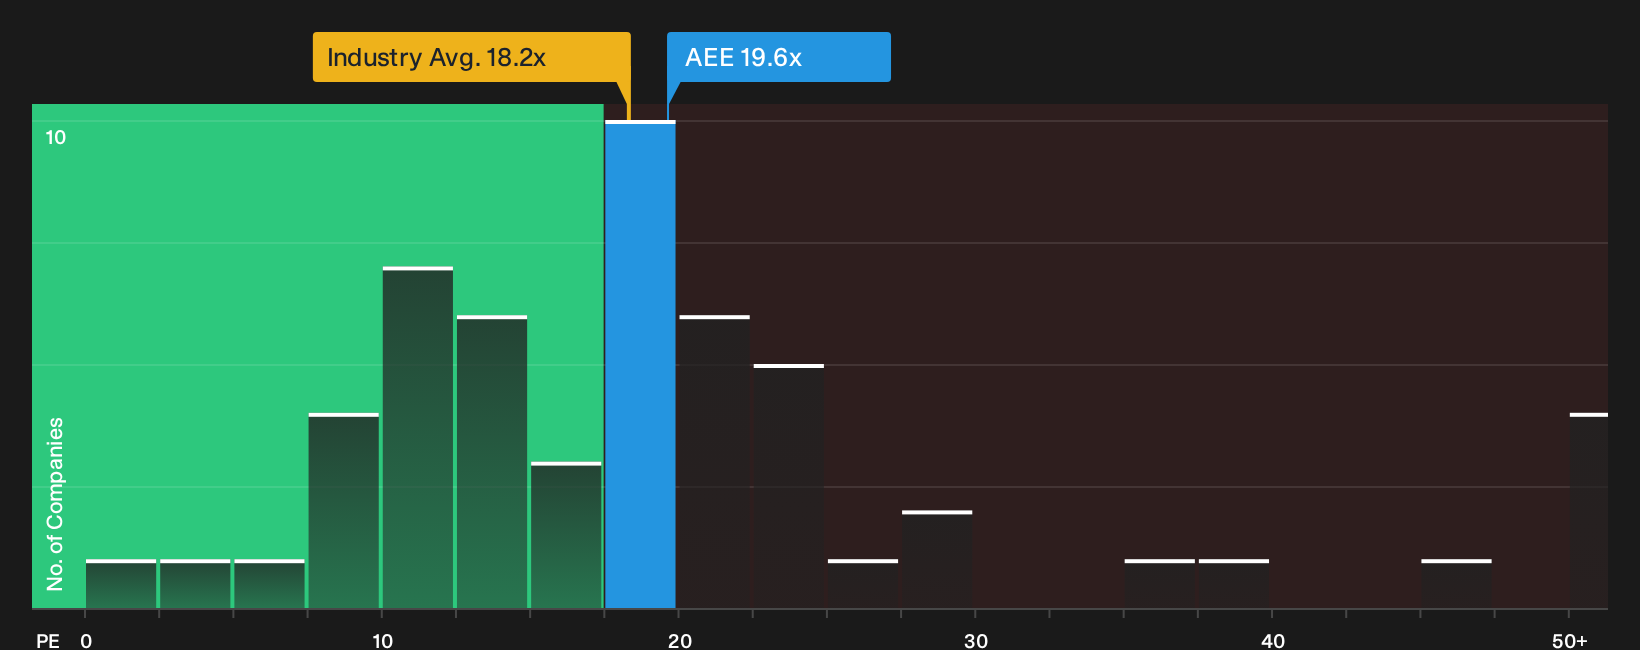
The fair value story for Ameren leans on analyst targets, yet the current P/E of 19.6x tells a slightly different story. It sits below the US Integrated Utilities average of 22.1x and the peer average of 21.3x, and it is also under the 20.3x fair ratio that our model suggests the market could move toward. That mix points to some room for upside re rating, but also signals that a lot already rides on earnings holding up. Which version of Ameren’s valuation do you trust most when real money is on the line?
For a cleaner read on how this earnings based view lines up against sector and peer pricing, and what that might mean for future valuation swings, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed on Ameren after all that, or already leaning one way? Act quickly, review the data for yourself, and weigh the 3 key rewards and 2 important warning signs.
Looking for more Ameren-sized investment ideas?
If Ameren’s story has sharpened your thinking, do not stop here. Broaden your watchlist, pressure test your assumptions, and let fresh ideas challenge your current holdings.
- Target quality at a discount and stress test your value thesis against the 29 high quality undervalued stocks hiding in plain sight.
- Build a portfolio that punches through noise by anchoring it to a list of solid balance sheet and fundamentals (25 results) before the crowd catches on.
- Spot future leaders early and scout the 18 high quality undiscovered gems before they attract wider market attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com