


How Investors Are Reacting To ATCO (TSX:ACO.X) Grimsby Plant Expansion
- ATCO recently expanded its Grimsby modular manufacturing facility and committed capital to 17 community-led energy projects in Alberta, using existing cash resources instead of relying solely on new borrowing.
- These moves tighten the link between ATCO's modular housing capabilities and energy infrastructure work and could reshape how its capital allocation and operating mix are viewed across its different business segments.
- We will now look at how ATCO's expanded Grimsby modular capacity could influence the existing investment narrative around growth and risk.
Scan how ATCO’s grid and modular push compares with peers by reviewing the hand picked 39 power grid technology and infrastructure stocks that are also leaning into power infrastructure and energy efficiency themes.
ATCO Investment Narrative Recap
To own ATCO, you need to be comfortable with a utility and infrastructure group that leans into long lived assets and capital heavy projects while still trying to grow its modular structures and rental platform. The near term story remains about execution on regulated energy spending and keeping earnings growth on track despite recent margin compression and a relatively high P/E multiple.
The expanded Grimsby plant and Alberta community energy spend look incremental rather than thesis changing. They slightly ease near term balance sheet concerns because management used existing cash instead of fresh debt, but the bigger risk still sits in interest coverage and dividend sustainability while profit margins remain well below last year’s level.
The expansion of the Grimsby modular facility is the cleanest operational link to the current grid and housing theme. Extra capacity matters most if ATCO can lift utilization and rental penetration in Canada, Australia and the early stage U.S. footprint, since analyst expectations already assume earnings growth of about 29.1% a year over the next few years.
Those same forecasts sit against pressure points that have not gone away. Interest costs are flagged as thinly covered by earnings, the dividend coverage is weak, and profit margins have moved from 8.7% to 3.4%. The pay off from Grimsby and related modular projects will be judged on whether they help that earnings and cash flow gap close over time without stretching the balance sheet further.
ATCO's narrative projects CA$6.5b revenue and CA$764.2m earnings by 2029. That profile implies 6.9% yearly revenue growth and an earnings increase of about four times from CA$182.0m today.
Uncover why ATCO's fair value indicates a 9% potential upside to its current price that may not last much longer.
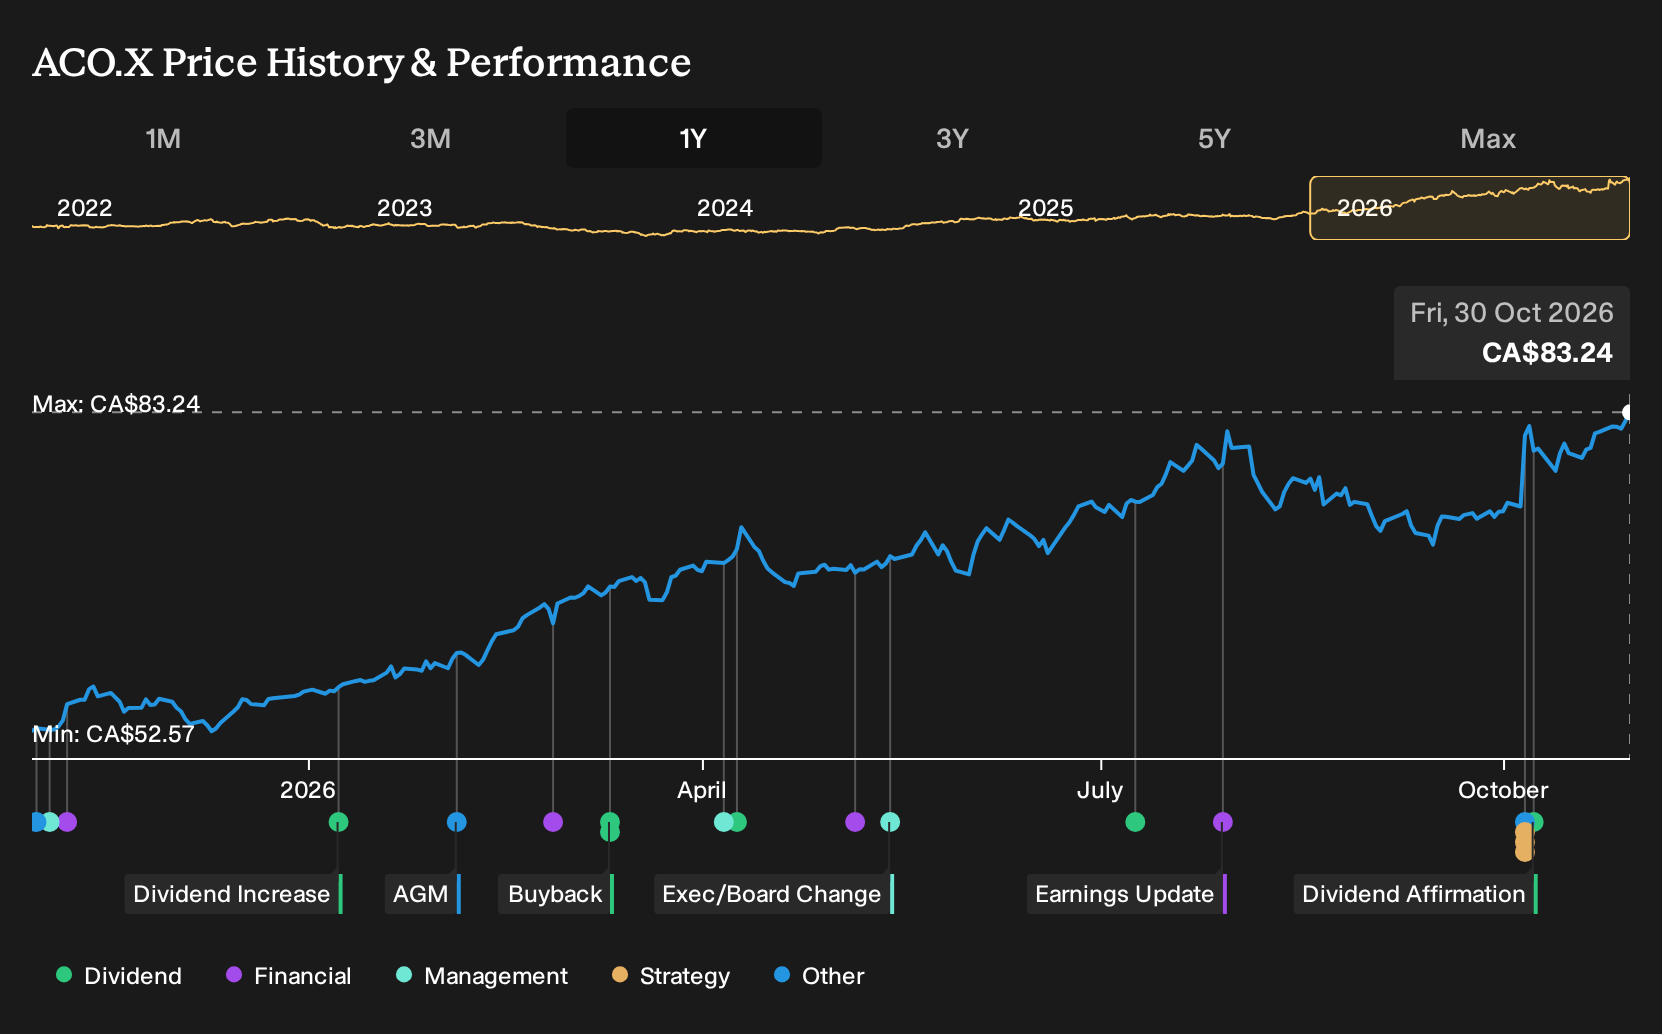
Exploring Other Perspectives
Two fair value estimates from the Simply Wall St Community cluster between about CA$83.38 and CA$91 per share, so even a small sample already shows that views on ATCO can diverge. When you set that beside the capital intensive grid and modular build out, it serves as a reminder to weigh multiple viewpoints before deciding how ATCO fits your portfolio.
Explore another ATCO fair value estimate, including one that suggests as much as 9% upside from the current price.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider forming your own view.
- A great starting point for your ATCO research is our analysis highlighting 2 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for ATCO. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate ATCO's overall financial health at a glance.
Looking for more investment ideas beyond ATCO?
If ATCO has sharpened your focus on utilities, infrastructure and income, it can be useful to line it up against other candidates that match your priorities on value, resilience and balance sheet strength. The Simply Wall St Screener lets you filter for exactly that mix so you can build a watchlist that fits your own risk and return preferences.
- If you want potential value with quality behind it, scan our 3 high quality undervalued stocks that already clear basic cash flow and balance sheet checks.
- If capital preservation matters just as much as upside, narrow your universe to a 7 resilient stocks with low risk scores that score well on stability and financial strength.
- If you prefer sturdier finances at the core of your research process, start with a list of solid balance sheet and fundamentals (6 results) and work from there based on your own return targets.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com