


Energy Transfer (ET) Stock May Still Be A Bargain Despite Distribution Hike
Energy Transfer has delivered a powerful run over the past few years, and the current unit price now invites a sharper question about what its earnings really justify. With that history in the rear-view mirror and new developments coming through, you need to know whether the recent quote lines up with the profit engine underneath.
- Over the past 5 years, Energy Transfer has returned 227.9%, which puts real pressure on the question of whether the current valuation is still grounded in its earnings power.
- The partnership has highlighted a twentieth consecutive increase in its quarterly cash distribution, which can shape how investors think about the durability of its cash generation and the earnings base used to support that payout.
- There is a second opinion on Energy Transfer worth weighing. See what analysts think Energy Transfer's shares could be worth.
The issue now is whether Energy Transfer's current price is adequately supported by the earnings profile that investors can see today.
If you want to test the same earnings question that surrounds Energy Transfer against a wider set of infrastructure focused businesses, scan through 39 power grid technology and infrastructure stocks
Does Energy Transfer Look Undervalued on Earnings?
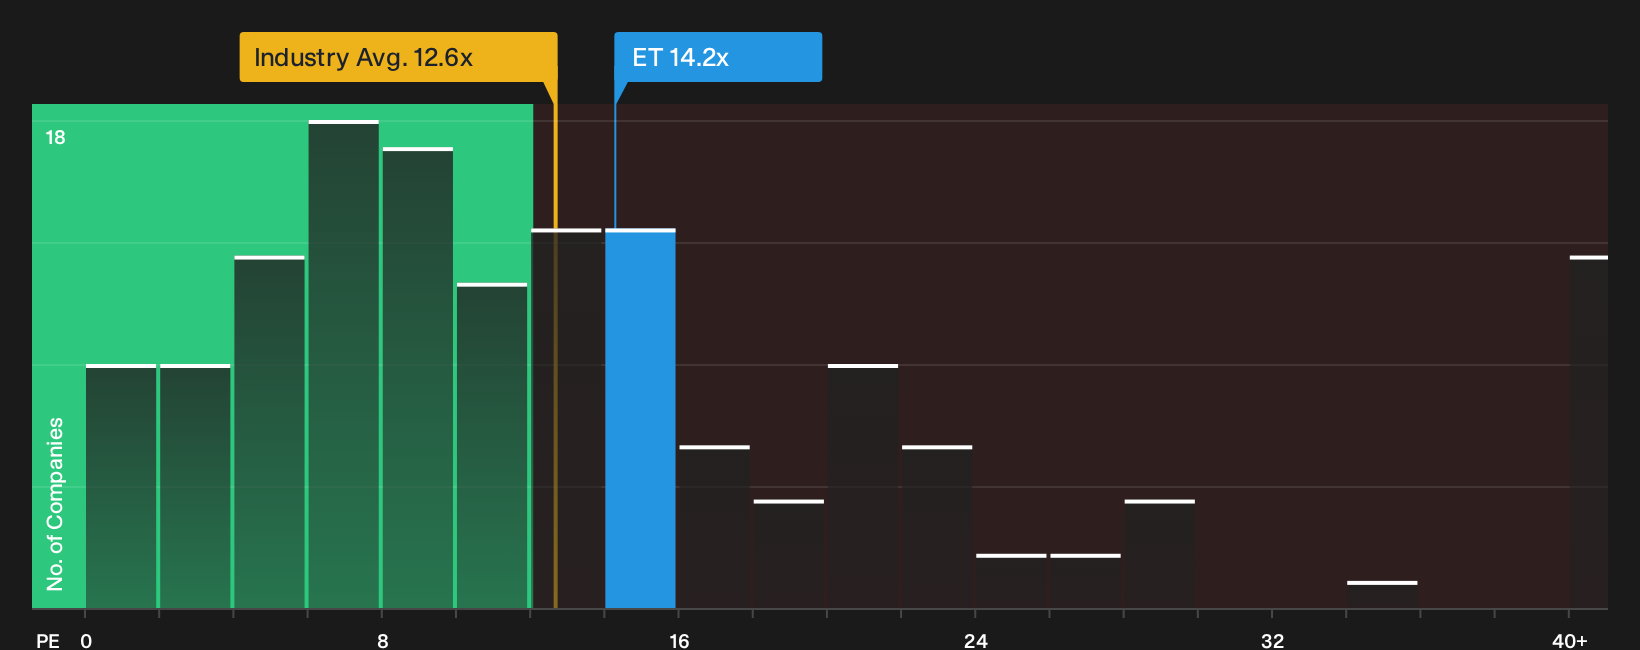
The P/E ratio fits Energy Transfer because earnings are a primary anchor for how investors look at this partnership. On this lens, the stock trades on a P/E of 14.2x, which is above both the Oil and Gas sector average of 12.6x and a peer mark of 19.3x. That mix means the units change hands at a higher multiple than the broad industry but at a lower level than similar businesses followed in the peer group.
Because the current P/E sits below the tailored fair multiple that would be expected given Energy Transfer's profile, the units screen as undervalued on this earnings yardstick. Despite the ongoing lift in its quarterly cash distribution drawing attention to the income story, the present ratio still prices the partnership at a discount to what the model implies on this metric. Explore the numbers behind Energy Transfer's P/E valuation.
The Energy Transfer Narrative: What Would Justify Today's Price?
Narratives take that valuation puzzle around Energy Transfer and spell out which future paths for growth, margins and earnings would need to play out for the units to look materially cheaper or more expensive than today based on those assumptions. Each scenario sets out the moving parts that sit behind its view of fair value, so you can compare those expectations with Energy Transfer's reported numbers as new results arrive.
One of the top community narratives on Energy Transfer: 15% undervalued
Recent long term customer commitments on multi billion dollar projects are now supported by more than 6 Bcf/d of contracted pipeline capacity...
Discover why this Narrative puts Energy Transfer at 15% undervalued.
Energy Transfer’s valuation still leaves one crucial angle unexplored
Price and earnings only tell part of the story for Energy Transfer, because the people steering the partnership and the way they are rewarded can shape every decision that follows. See who runs Energy Transfer and how they are paid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com