


Earnings Beat Altering The Investment Case For Kesko Oyj (HLSE:KESKOB)?
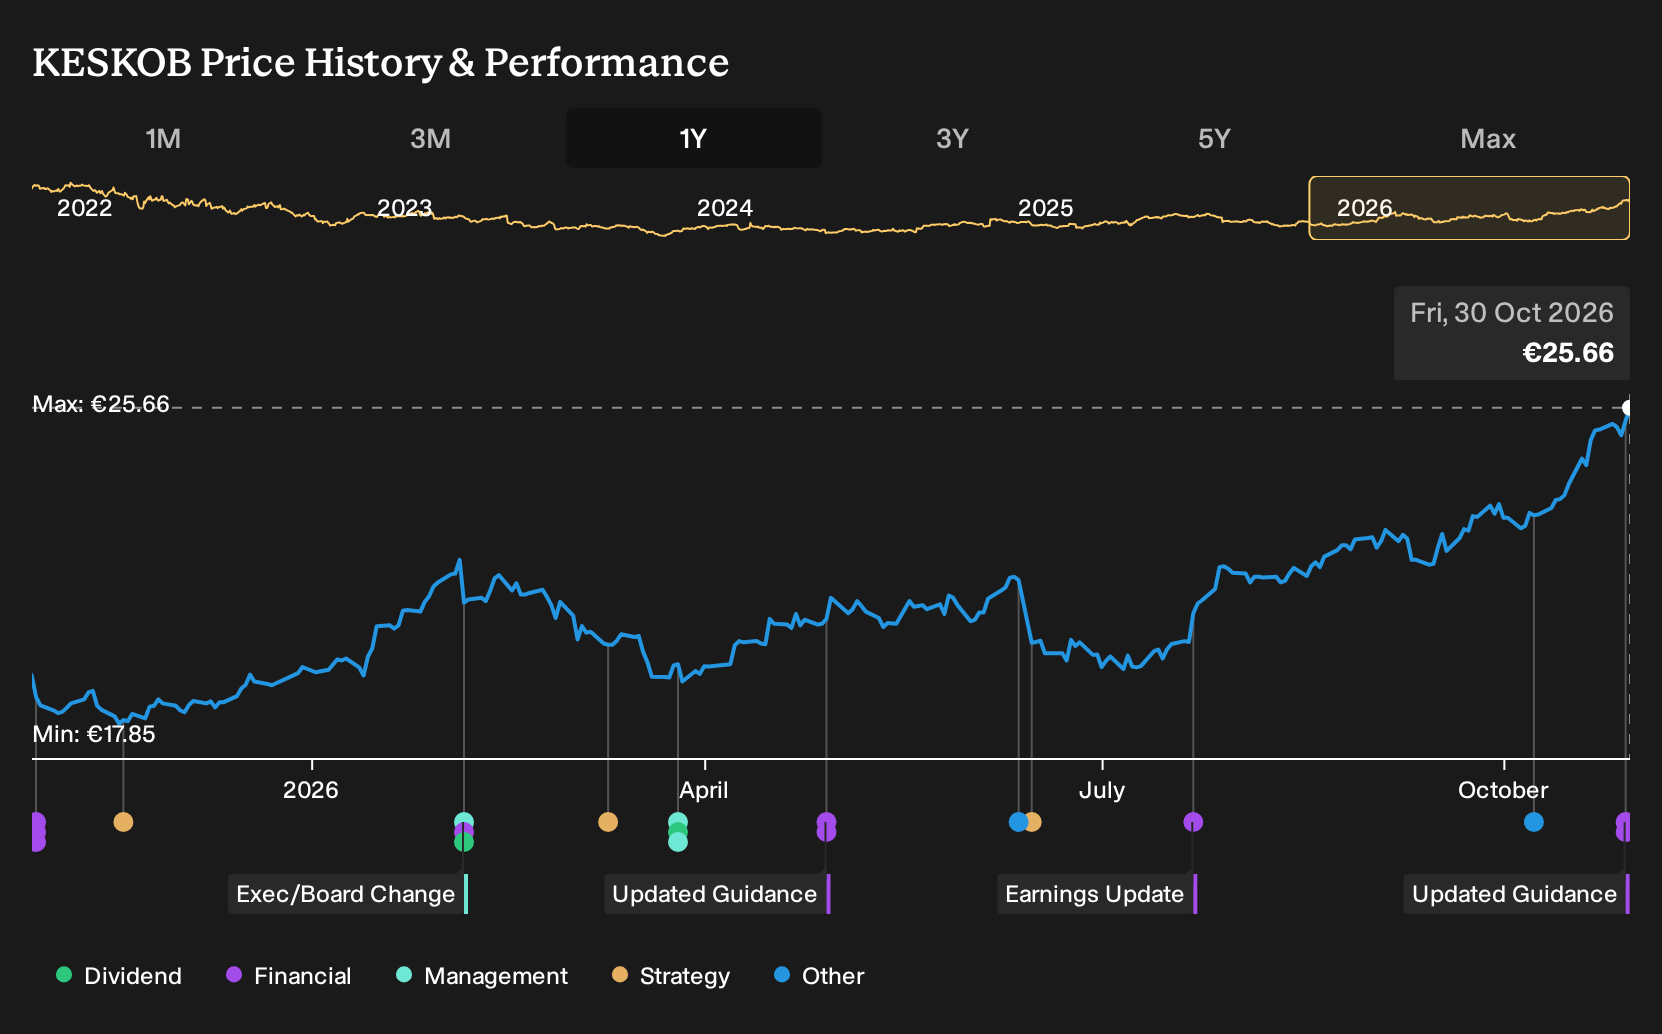
- Kesko Oyj reported third quarter 2026 sales of €3,394.5 million and net income of €162.9 million, with earnings per share from continuing operations at €0.41, and guided for 2027 net sales to improve across every division and operating country.
- The combination of higher year to date sales and net income through September 2026 and management’s expectation of broader sales improvement in 2027 indicates that Kesko Oyj is leaning into existing business momentum rather than resetting its outlook lower.
- We will now explore how Kesko Oyj’s stronger third quarter earnings performance might reshape the investment narrative that investors have been using.
Compare Kesko Oyj’s momentum with other quality opportunities by running the handpicked 194 high quality undervalued stocks that screens for strong fundamentals and potential mispricing.
Kesko Oyj Investment Narrative Recap
To own Kesko Oyj, you need to believe that its grocery, building and technical trade, and car operations can keep turning steady Nordic demand into consistent earnings, even when volume growth is modest. The recent 2026 figures show the group operating with some momentum, so the latest update reinforces, rather than changes, that core thesis.
The key short term catalyst is execution on store investments and logistics projects that aim to lift traffic and efficiency. The main risk is still operational. Heavy grocery CapEx and exposure to construction and housing cycles could pressure returns if consumer demand or building activity stays weak for longer.
The most relevant update for that thesis is Kesko Oyj’s 2027 guidance that net sales should improve in every division and operating country. That is directly tied to the execution question. It sets a clear yardstick for whether the store investments, B2B repositioning in building trade and car portfolio work are translating into broader customer activity.
This guidance also frames the near term risk reward trade off. If grocery traffic, European construction orders or Finnish car demand soften, the company may find it harder to reach those higher sales ambitions without leaning more on pricing and campaigns, which could pressure margins. Analyst models and valuation debates sit in the background. The operational delivery against this multi segment sales goal is what now matters most.
What The Analyst Scenario Implies For Kesko Oyj
Kesko Oyj's narrative projects €14.6b revenue and €589.7 million earnings by 2029. This assumes 4.4% yearly revenue growth and an earnings increase of about €171.5 million from €418.2 million today.
Uncover why Kesko Oyj's fair value indicates a 9% potential downside to its current price, which leaves little room for error.
Exploring Other Perspectives
Three fair value estimates from the Simply Wall St Community span roughly €23 to above €51, so retail views on Kesko Oyj already stretch from deep discount to clear premium. When you set that beside 2027 sales guidance across all divisions and the ongoing CapEx and construction cycle risks, you get a wide decision set that rewards comparing several viewpoints.
Explore 2 other Kesko Oyj fair value estimates, including one that suggests there may be as much as 9% downside from the current price.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Kesko Oyj research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Kesko Oyj. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Kesko Oyj's overall financial health at a glance.
Looking For More Investment Ideas Beyond Kesko Oyj?
If Kesko Oyj is only one piece of your watchlist, it helps to line it up against other businesses with different strengths, income profiles, and risk levels. The Simply Wall St Screener can help you quickly surface candidates that fit the kind of portfolio you want to build.
- If you want potential mispricing with solid business quality, scan through the 194 high quality undervalued stocks and see which companies line up with your return and risk expectations.
- If reliability matters more than excitement, focus on cash rich balance sheets and steady operations by checking the 216 resilient stocks with low risk scores for ideas that aim to keep drawdowns contained.
- If you prefer stronger fundamentals that markets may not fully appreciate yet, broaden your search with the 602 high quality undiscovered gems and see which lesser known stocks deserve a closer look.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com