


Hokuriku Electric Power (TSE:9505) Stock Cools As Q2 Earnings Thin
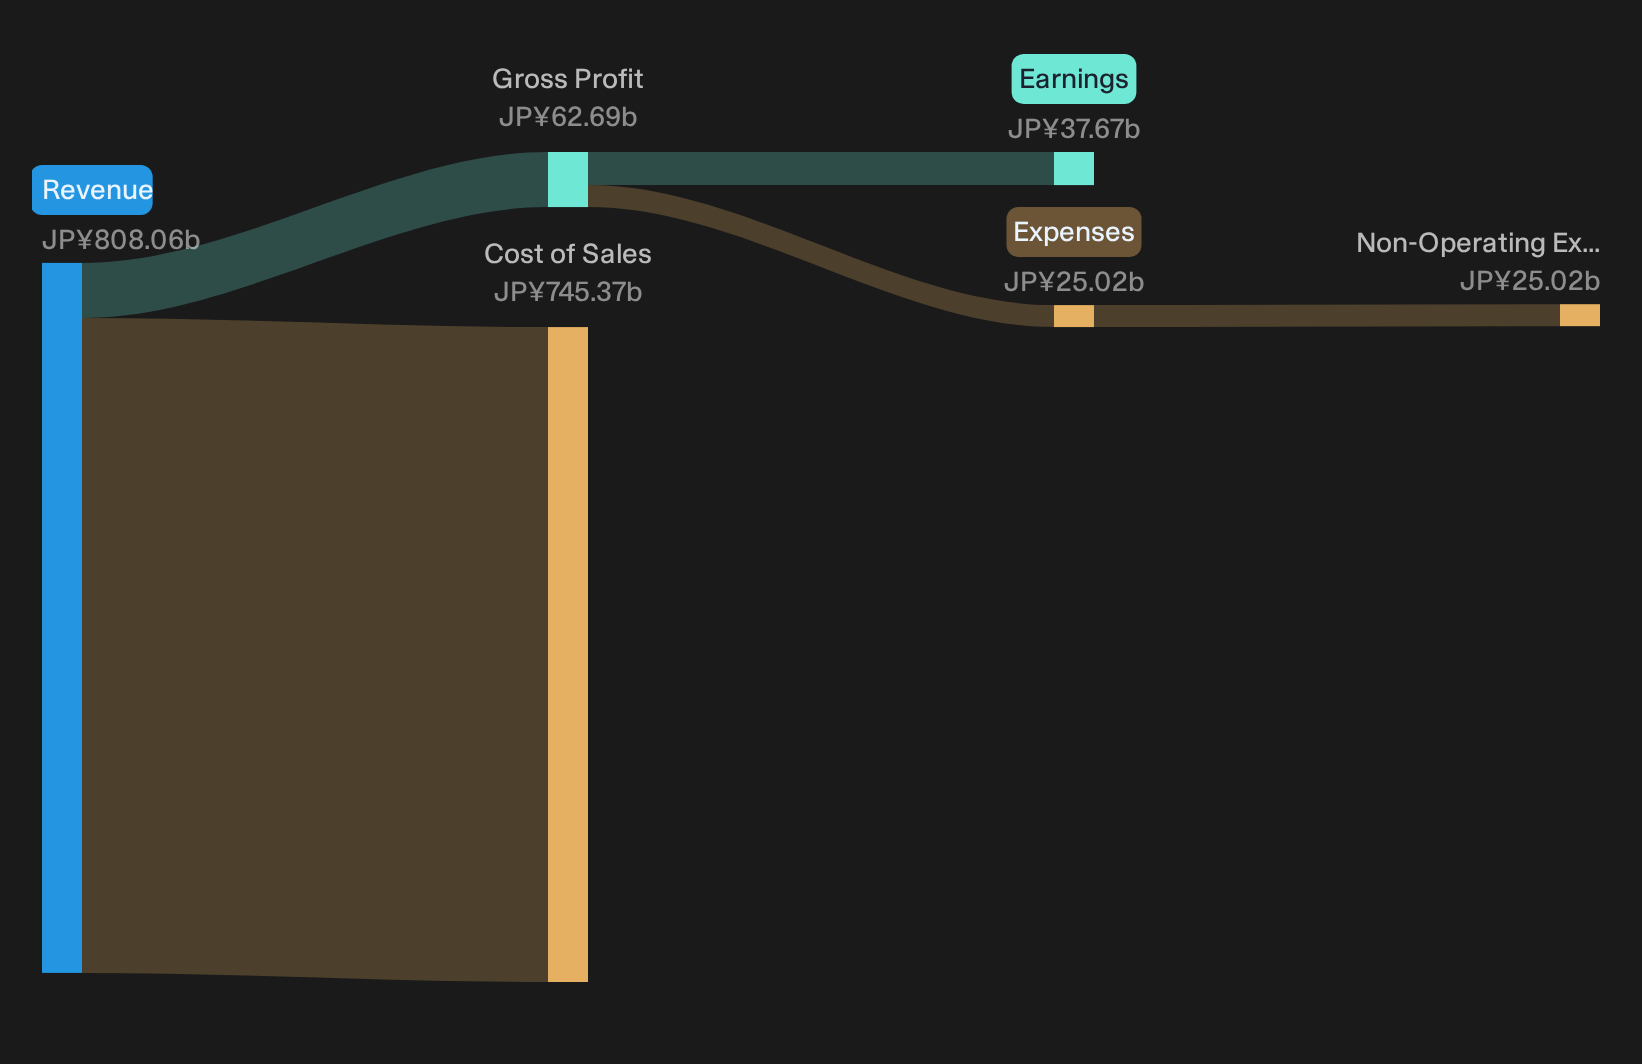
Hokuriku Electric Power just dropped its Q2 2027 scorecard, and the share price barely budged over the past week, rising about 1.5% into the release. The headline is simple. Profitability looks squeezed. Basic earnings per share for the quarter came in at ¥43.75 on revenue of ¥225,666 million, well below the much stronger Q1 print.
For a stock trading on a low P/E and already flagged for thinner net margins and balance sheet strain, that kind of earnings compression can spook short term traders. The question now is whether this muted reaction reflects discipline or complacency.
Concerned that Hokuriku Electric Power's thin margins and earnings squeeze could signal a value trap rather than a recovery story? Benchmark it against a list of solid balance sheet and fundamentals stocks (21 results) to see options with sturdier finances and more room to absorb pressure.
Q2 2027 Earnings Summary
- Revenue (Q2 2027 vs. Q2 2026): ¥225,666 million vs. ¥217,100 million (top line slightly higher year on year)
- Net Income (Excl. Extra Items, Q2 2027 vs. Q2 2026): ¥9,142 million vs. ¥20,152 million (profit more than halved year on year)
- Basic EPS (Q2 2027 vs. Q2 2026): ¥43.75 vs. ¥96.47 (earnings per share declined by about 55%)
- Trailing 12M Net Profit Margin (latest vs. prior year): 4.7% vs. 8.2% (profitability ratio roughly cut in half over the past year)
Ask Charlie which risk matters most for Hokuriku Electric Power.
Hokuriku Electric Power and the Bullish Stability Story
For anyone leaning on Hokuriku Electric Power as a steady regional utility, the latest figures send a mixed but readable message. Revenue in Q2 2027 sits above the prior year, which supports the idea that the core electricity and related services engine still turns over. Profit tells a different story. Net income and EPS have dropped sharply and the trailing margin has almost halved. The diversified model still brings cash in the door, yet the earnings squeeze shows that stability on the top line is not automatically flowing through to shareholders.
Margin Compression and the Hokuriku Bearish Narrative
Concerns about Hokuriku Electric Power as a complex, pressured utility find real backing in these results. Profit more than halved year on year while the trailing net margin slipped from 8.2% to 4.7%. That is a big hit to earnings power for a regulated operator that usually leans on predictable cost recovery. The share price has been roughly flat over the past month after a stronger 90 day run, which suggests the immediate risk is being absorbed for now, but the pressure on profitability fits the more cautious story around this stock.
After profit margins compressed and debt coverage looks tight, you might ask whether this is just early surface damage. Review our independent risk analysis for Hokuriku Electric Power which shows 3 important warning signsHunt Quiet Value Stories Now
Hokuriku Electric Power recently highlighted how compressing margins can leave a share price stalled. The real opportunity is finding stocks that could be undervalued before the market corrects them.
- Company 1 - 39% below our estimate - run virtual entertainers whose fan demand then pulls through higher margin digital goods and events.
- Company 2 - 27% below our estimate - supply precision grinding tools and ceramics that manufacturers adopt when tightening tolerances on advanced components.
- Company 3 - 24% below our estimate - sell data and document platforms firms turn to once manual reporting and invoicing start to bottleneck operations.
Those are three of them. See all 15 potentially undervalued companies →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com