


Broadmedia (TSE:4347) Stock Faces Q2 Results Profitability Squeeze
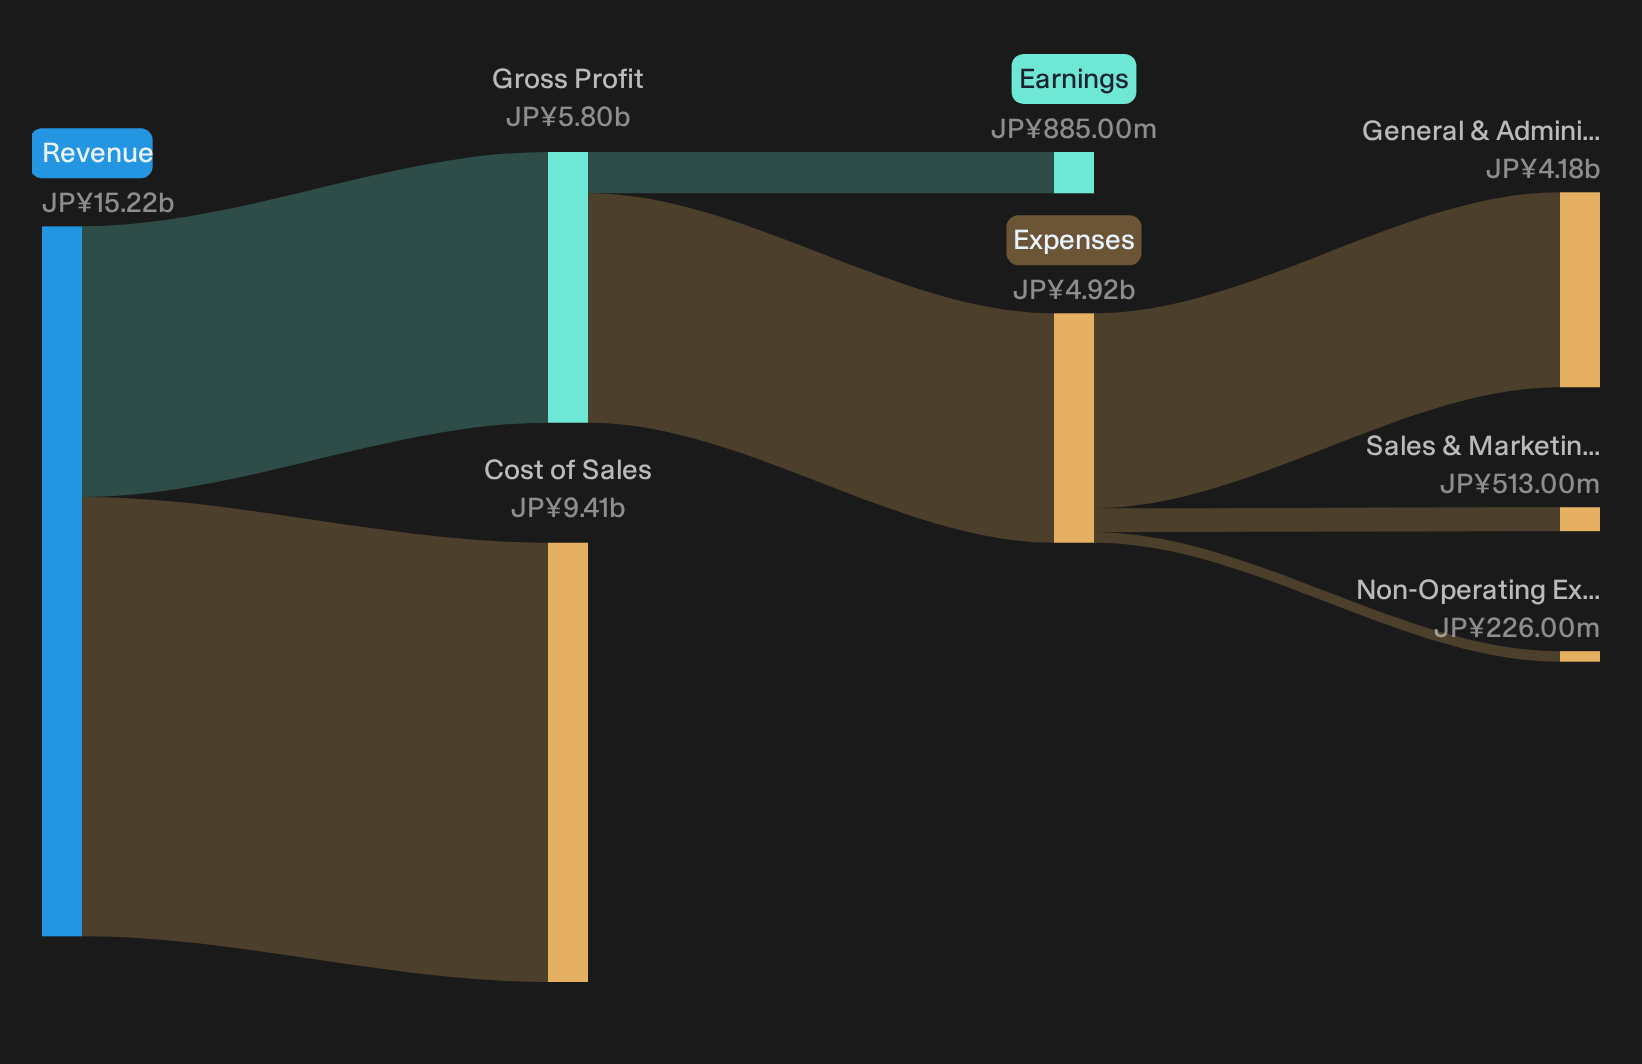
Broadmedia just reported Q2 2027 results and the real story is not the headline earnings figure. The stock closed at ¥2,489 on 30 October after a stretch of strong recent returns, yet the latest quarter shows profit pressure as Basic EPS came in at ¥22.31 on net income of ¥159 million. For a telecom operator, that squeeze on profitability is the key tension. Short term traders are treating recent share momentum as validation, while the income statement is flashing a more cautious reading on how much earnings power is actually sticking.
Love the recent Broadmedia share price strength but concerned that pressured earnings might not keep up. Compare that setup with our list of solid balance sheet and fundamentals stocks (21 results).
Q2 2027 Earnings Summary
- Revenue (Q2 2027 vs Q2 2026): ¥3,472 million vs. ¥3,627 million (decline of 4.3%)
- Net Income (Excl. Extra Items, Q2 2027 vs Q2 2026): ¥159 million vs. ¥135 million (increase of 17.8%)
- Basic EPS (Q2 2027 vs Q2 2026): ¥22.31 vs. ¥18.94 (increase of 17.8%)
- Trailing 12-Month Net Margin (Q2 2027 vs Q2 2026): 5.8% vs. 3.7% (improvement of 2.1 percentage points)
Earnings are up sharply, but the valuation signals are mixed. Ask Charlie what makes Broadmedia look undervalued despite its P/E.
Broadmedia bullish story meets mixed earnings support
For anyone leaning positive on Broadmedia, the appeal is that a digital infrastructure and education platform can translate into steadier earnings. The latest quarter partly leans that way. Net income excluding one offs reached ¥159 million and Basic EPS was ¥22.31, both above Q2 2026. Trailing 12 month net margin at 5.8% versus 3.7% a year earlier points to better earnings quality, even as revenue moved from ¥3,627 million to ¥3,472 million. Profitability looks more resilient than the flat telecom headline suggests.
Bearish concerns on focus and growth still in play
Some investors may be concerned about Broadmedia spreading itself thin across content, tech services and education. The latest figures do not completely clear that up. Revenue slipped 4.3% year on year, which challenges any simple growth label for this mix of businesses. Margin improvement to 5.8% helps, yet it comes alongside top line pressure. That aligns with a more cautious view that cost control and business mix are currently the main drivers. With an acquisition proposal on the table as of 29 October 2026, execution risk around all these segments remains a live issue.
After a 3 month period where the Broadmedia share price has been more volatile than the JP market, it is fair to ask whether earnings pressure and business complexity are early warning signs or just noise. Review the independent risk analysis for Broadmedia which shows 1 important warning signHunt For Quiet Earnings Power
Broadmedia just reminded investors that reported profit and recent price action do not always move in lockstep. The real opportunity is finding stocks that could be undervalued before the market corrects them.
- Company 1 - 37% below our estimate - directs advanced air and water handling for data centers and specialized medical environments.
- Company 2 - 39% below our estimate - runs virtual performer pipelines for corporate marketing, live events, and branded digital campaigns.
- Company 3 - 44% below our estimate - coordinates large-scale software and IT deployment projects that enterprises choose to outsource.
That is three of the list. See all 15 potentially undervalued companies →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com