


Is Johnson & Johnson (JNJ) Cheap On Pipeline Wins Or Is The Upside Priced In?
Johnson & Johnson (JNJ) is back in focus after a string of clinical and MedTech updates that collectively reshape how investors may think about its oncology, immunology and device pipeline strength.
Recent trial readouts and device launches have arrived against the backdrop of a strong run in Johnson & Johnson’s shares, with a year to date share price return of 31.76% at a last close of US$273.20 and a 1-year total shareholder return of 47.91%, indicating firm momentum despite a small 1-day share price pullback of 0.73%.
Scan how Johnson & Johnson’s clinical momentum compares with other healthcare groups that are pushing late stage trials and fresh product launches through our hand picked 18 high quality undiscovered gems
After a 1 year total return of 47.91% and a share price sitting just below analyst targets yet at a steep intrinsic value discount, is the market correctly pricing Johnson & Johnson’s caution, or leaning too hard on old worries?
Most Popular Narrative: 13.5% Overvalued
Against a last close of $273.20, the most followed narrative on Johnson & Johnson anchors on a fair value of $240.69 and frames the recent share price strength as ahead of that reference point, not behind it.
The executive who carried ICOTYDE, INLEXZO, and TREMFYA through the entire prior call is gone. Her successor opens his first answer on this one by thanking her for her leadership. No further explanation is offered, and none is asked for, which is itself worth noting: a change in the single most prominent spokesperson for the Innovative Medicine franchise drew zero analyst follow-up.
See why 4 investors see Johnson & Johnson as 14% overvalued.
Result: Fair Value of $240.69 (OVERVALUED)
Still, Johnson & Johnson’s own admission that MedTech performance fell short, together with softer support for Abiomed and robotics, could unsettle the overvaluation story.
Find out about the key risks to this Johnson & Johnson narrative.
Another View: Johnson & Johnson Through A Cash Flow Lens
The narrative calling Johnson & Johnson 13.5% overvalued on a $240.69 fair value runs into a very different picture when looking at our DCF model. On that framework, JNJ at $273.20 screens as undervalued against an estimated future cash flow value of $471.87. Which story do you trust more, pricing or cash flows?
Look into how the SWS DCF model arrives at its fair value.
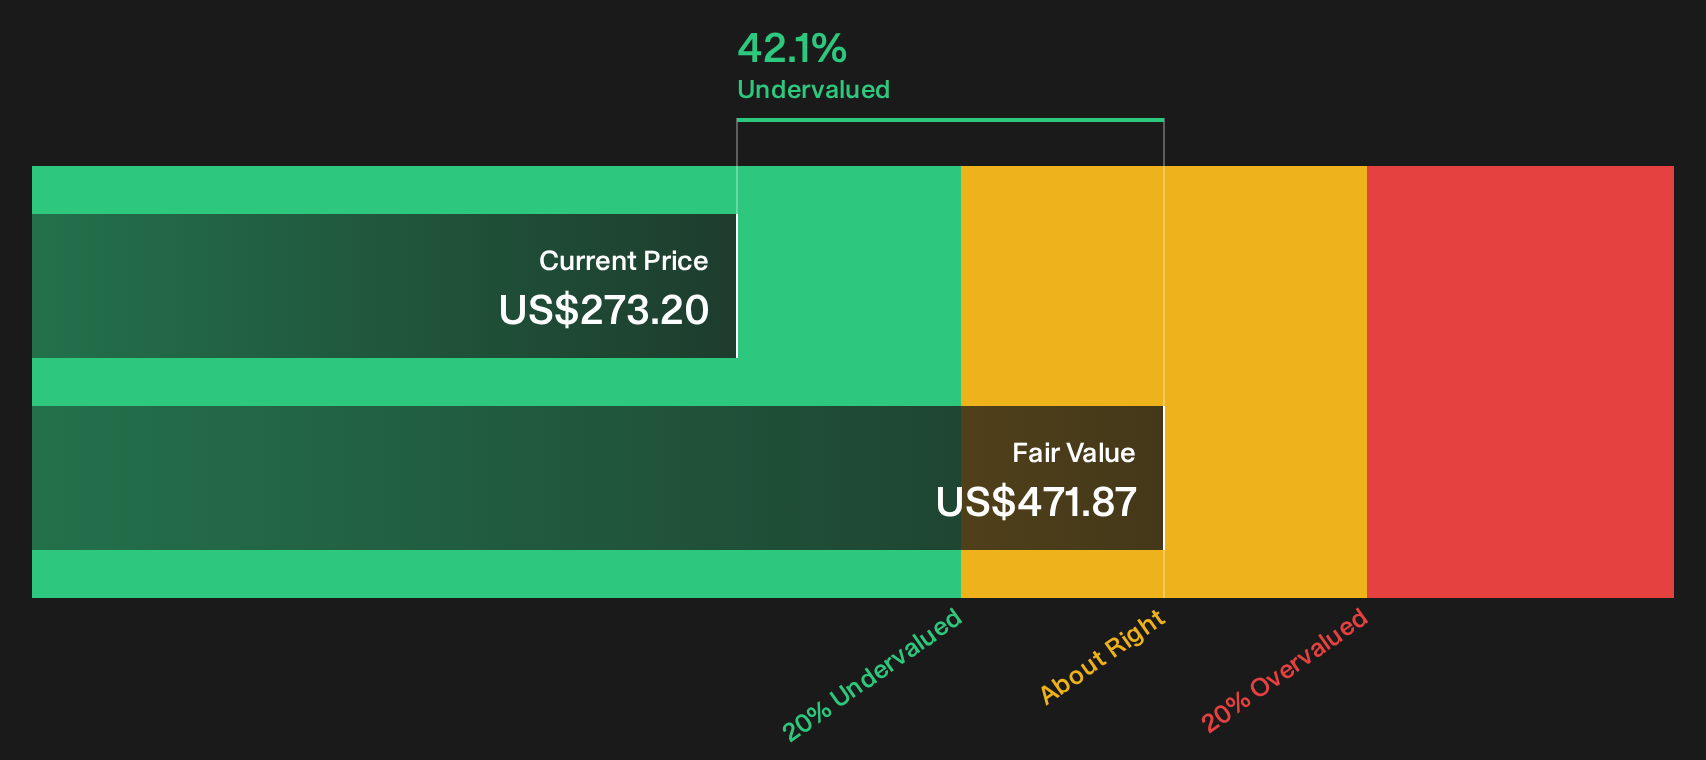
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Johnson & Johnson for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 29 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages run through Johnson & Johnson right now. Move quickly, review the data independently, and then weigh the 3 key rewards and 3 important warning signs.
Looking for more investment ideas beyond Johnson & Johnson?
If Johnson & Johnson has sharpened your focus, do not stop here. Broaden your watchlist now and let high quality filters point you toward your next opportunity.
- Target resilient candidates that aim to limit downside by starting with a 30 resilient stocks with low risk scores to keep risk scores in check while fundamentals do the heavy lifting.
- Hunt for mispriced quality and let a 29 high quality undervalued stocks surface companies that pair solid cash generation with valuations that still look reasonable.
- Anchor your shortlist in financial strength first and use a list of solid balance sheet and fundamentals (25 results) to highlight businesses built on sturdier foundations.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com