


Earnings And Buybacks Might Change The Case For Investing In Fulton Financial (FULT)
- Fulton Financial reported third quarter 2026 net interest income of US$290.04 million and net income of US$116.66 million, with basic earnings per share from continuing operations at US$0.60.
- Net loan charge offs for the quarter were US$9.46 million, and Fulton Financial completed repurchases of 4,062,650 shares for US$91.73 million under its existing buyback plan.
- Next, the focus shifts to how Fulton Financial's reported earnings and completed buybacks could influence the existing investment narrative.
Fulton Financial Investment Narrative Recap
To own Fulton Financial, you need to believe the bank can keep turning a relatively modest growth profile into steady earnings while holding credit quality and funding costs in check. The latest quarter shows net interest income and net income at levels that line up with that story, so the core operating thesis looks intact rather than reset.
The short term swing factor is still how loan growth and margin trends track against management’s 2026 guidance. Credit costs remain a key risk. Net loan charge offs of US$9.46 million do not materially change that risk, but any sustained shift in those figures would matter for Fulton Financial’s earnings path.
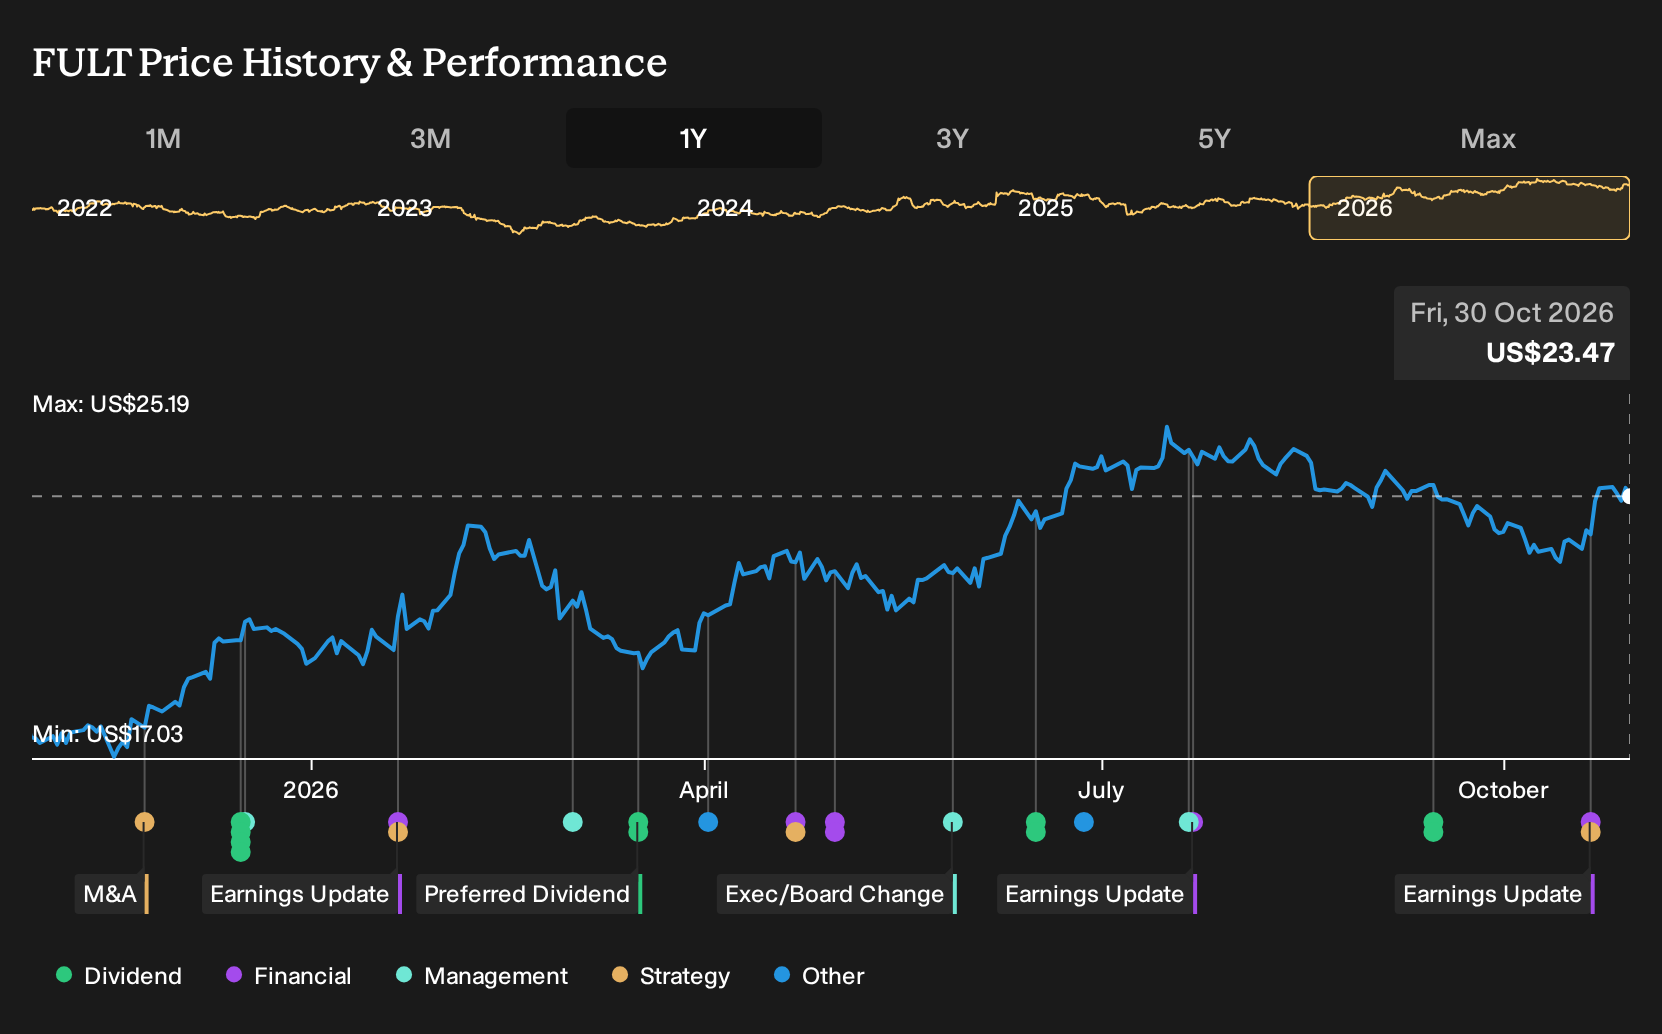
The most relevant update for this earnings print is the completed share repurchase of 4,062,650 shares for US$91.73 million under the existing plan. That buyback, equal to 2.18% of outstanding shares, now sits alongside higher reported earnings per share and provides a clearer view of per share performance.
In terms of catalysts, the finished buyback matters because it interacts directly with Fulton Financial’s guidance focus on operating leverage and margin discipline. With repurchases complete for now, more of the near term story shifts back to what happens with loan growth, fee income mix, and any change in provision expense if credit metrics soften from current levels.
Fulton Financial's current analyst narrative points to revenues of US$1.7b and earnings of US$489.1 million by 2029, based on an assumed 8.3% yearly increase in revenue and an earnings uplift of about US$102.7 million from US$386.4 million today.
Explore why Fulton Financial's fair value reflects a 13% potential upside to its current price before that difference begins to narrow.
Exploring Other Perspectives
Two fair value estimates from the Simply Wall St Community span roughly US$26.42 to US$48.14 per share, so you are looking at a wide gap between the most cautious and most optimistic views. When you set those opinions against loan growth guidance trimmed to low single digits, you can see why investors might want to compare several competing outlooks on Fulton Financial before deciding how much weight to give this quarter’s buybacks and earnings detail.
Explore another Fulton Financial fair value estimate, including one that suggests potential upside of up to 105% from the current price.
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Fulton Financial research is our analysis highlighting 5 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Fulton Financial. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Fulton Financial's overall financial health at a glance.
Looking For More Ideas Beyond Fulton Financial?
If you want to cross check Fulton Financial against other opportunities, the Simply Wall St Screener can help you filter for different types of stocks that match your risk tolerance and income goals.
- For investors who want potential income plus resilience, review companies in the 5 dividend fortresses that aim to combine yield with balance sheet strength.
- If capital preservation is a priority, narrow your search to businesses in the 30 resilient stocks with low risk scores that score well on financial stability and volatility measures.
- For those hunting for under followed opportunities, scan the 18 high quality undiscovered gems that pair solid fundamentals with limited current market attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com