


Is SL Green Realty (SLG) A Bargain As Higher 2026 Guidance Lifts Valuation Hopes?
SL Green Realty (SLG) paired a higher full year 2026 net income outlook of US$0.40 to US$0.60 per share with a third quarter that showed stronger revenue and profit versus a year earlier.
Recent moves in SL Green Realty’s share price have been more muted than the earnings headlines suggest, with the stock slipping around 1.1% on the day to US$50.36 but still showing a 7.2% year to date share price return and a 3 year total shareholder return above 70%. This points to earlier momentum that now looks more measured as investors weigh stronger quarterly results, higher 2026 net income guidance and the recent US$2.0b refinancing of 245 Park Avenue against ongoing questions about long term office demand and balance sheet risk.
Scan how SL Green Realty compares with other office and real estate landlords by reviewing the hand picked list of solid balance sheet and fundamentals (25 results).
For SL Green Realty, that muted share price reaction can read either as investors already baking in better earnings or as early doubt creeping back in. To sort sentiment from fundamentals, the next step is valuation.
Most Popular Narrative: 10.6% Undervalued
Against Friday’s close at $50.36, the most widely followed narrative on SL Green Realty puts fair value at $56.32. This frames the recent guidance upgrade and refinancing work as only partly reflected in the share price.
Portfolio optimization and disciplined capital recycling, including strategic dispositions and realizing significant gains on debt and preferred equity investments, are strengthening liquidity, setting the stage for new accretive investments, and reducing interest expense to enhance future earnings growth.
Value-add developments and transformative projects (such as One Vanderbilt and the potential Caesars Palace Times Square casino) have the potential to unlock new high-margin revenue streams, increase portfolio valuation, and materially expand SL Green's income base in the medium to long term.
See why 24 investors see SL Green Realty as 11% undervalued.
Result: Fair Value of $56.32 (UNDERVALUED)
Still, higher interest expenses from delayed property sales, along with the risk of weaker leasing or unexpected tenant move outs, could quickly challenge that 10.6% undervaluation story for SL Green Realty.
Find out about the key risks to this SL Green Realty narrative.
Another View: What Multiples Say About SL Green Realty
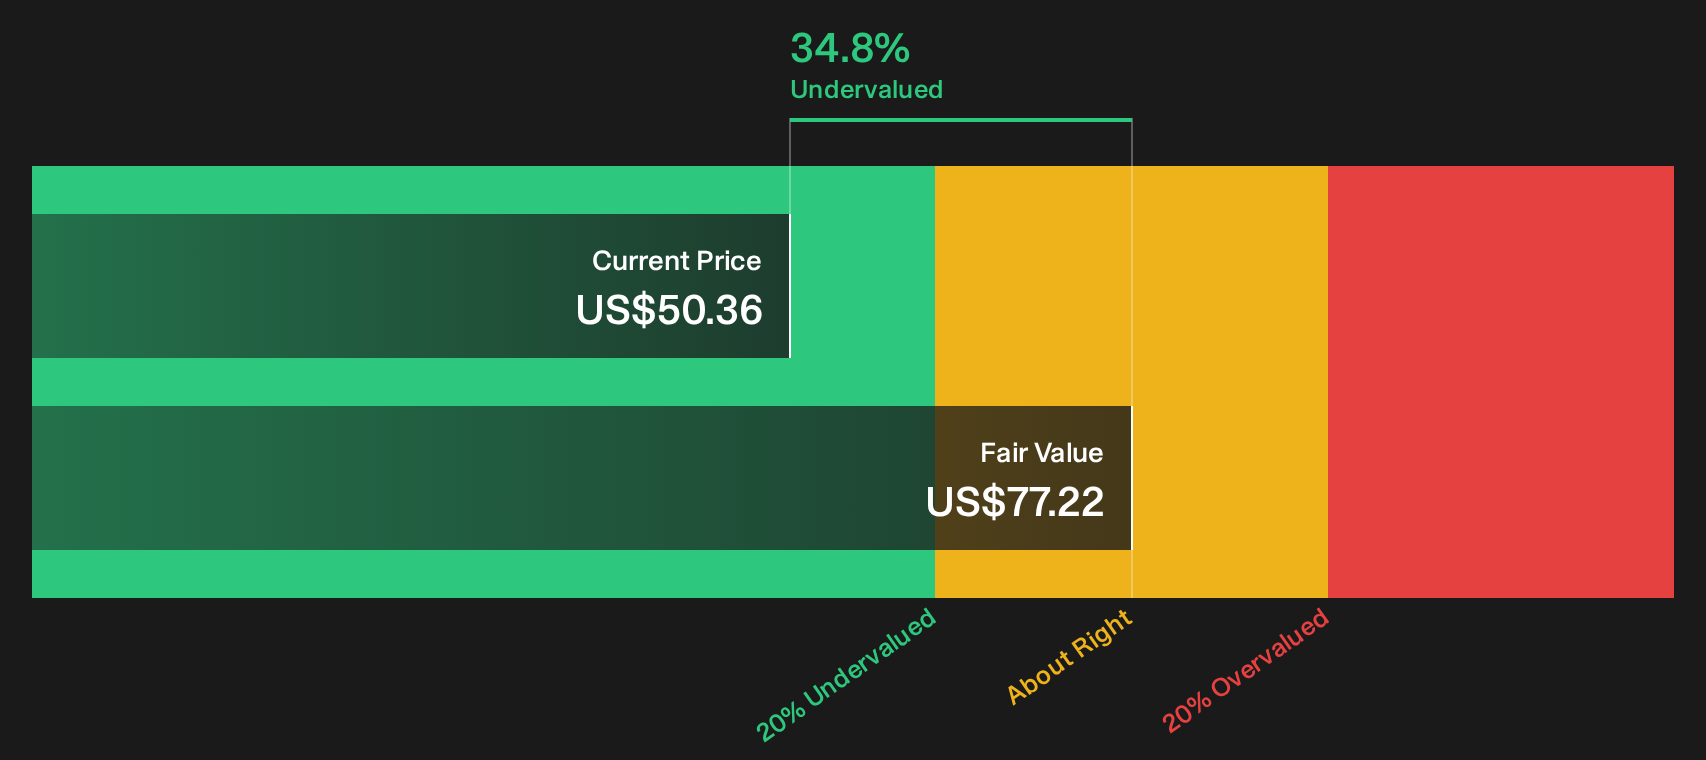
The DCF driven fair value of $77.22 presents SL Green Realty as attractively priced. A different perspective tells a less generous story. On a P/S of 3.4x, the stock trades above the US Office REITs average of 2.0x and above its own fair ratio of 2.9x, which suggests valuation risk if sentiment cools.
Investors who want to see how that earnings based model is built can review the Look into how the SWS DCF model arrives at its fair value..
Next Steps
The mixed mood across SL Green Realty’s guidance, refinancing progress and valuation signals leaves the next move up to you. Weigh the upside and downside data points carefully, then anchor your own view with the 1 key reward and 3 important warning signs.
Looking for more investment ideas beyond SL Green Realty?
Do not stop your research with SL Green Realty. Use the Simply Wall St screener to spot fresh opportunities that fit your risk tolerance and return goals.
- Target potential mispricing by reviewing companies that appear attractively priced on fundamentals through the 29 high quality undervalued stocks.
- Strengthen your income stream by focusing on businesses with robust payouts using the 5 dividend fortresses.
- Dial back risk without stepping out of the market by scanning resilient companies via the 30 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com