


Did Industrial Demand Strength Just Shift Stanley Black And Decker's (SWK) Investment Narrative?
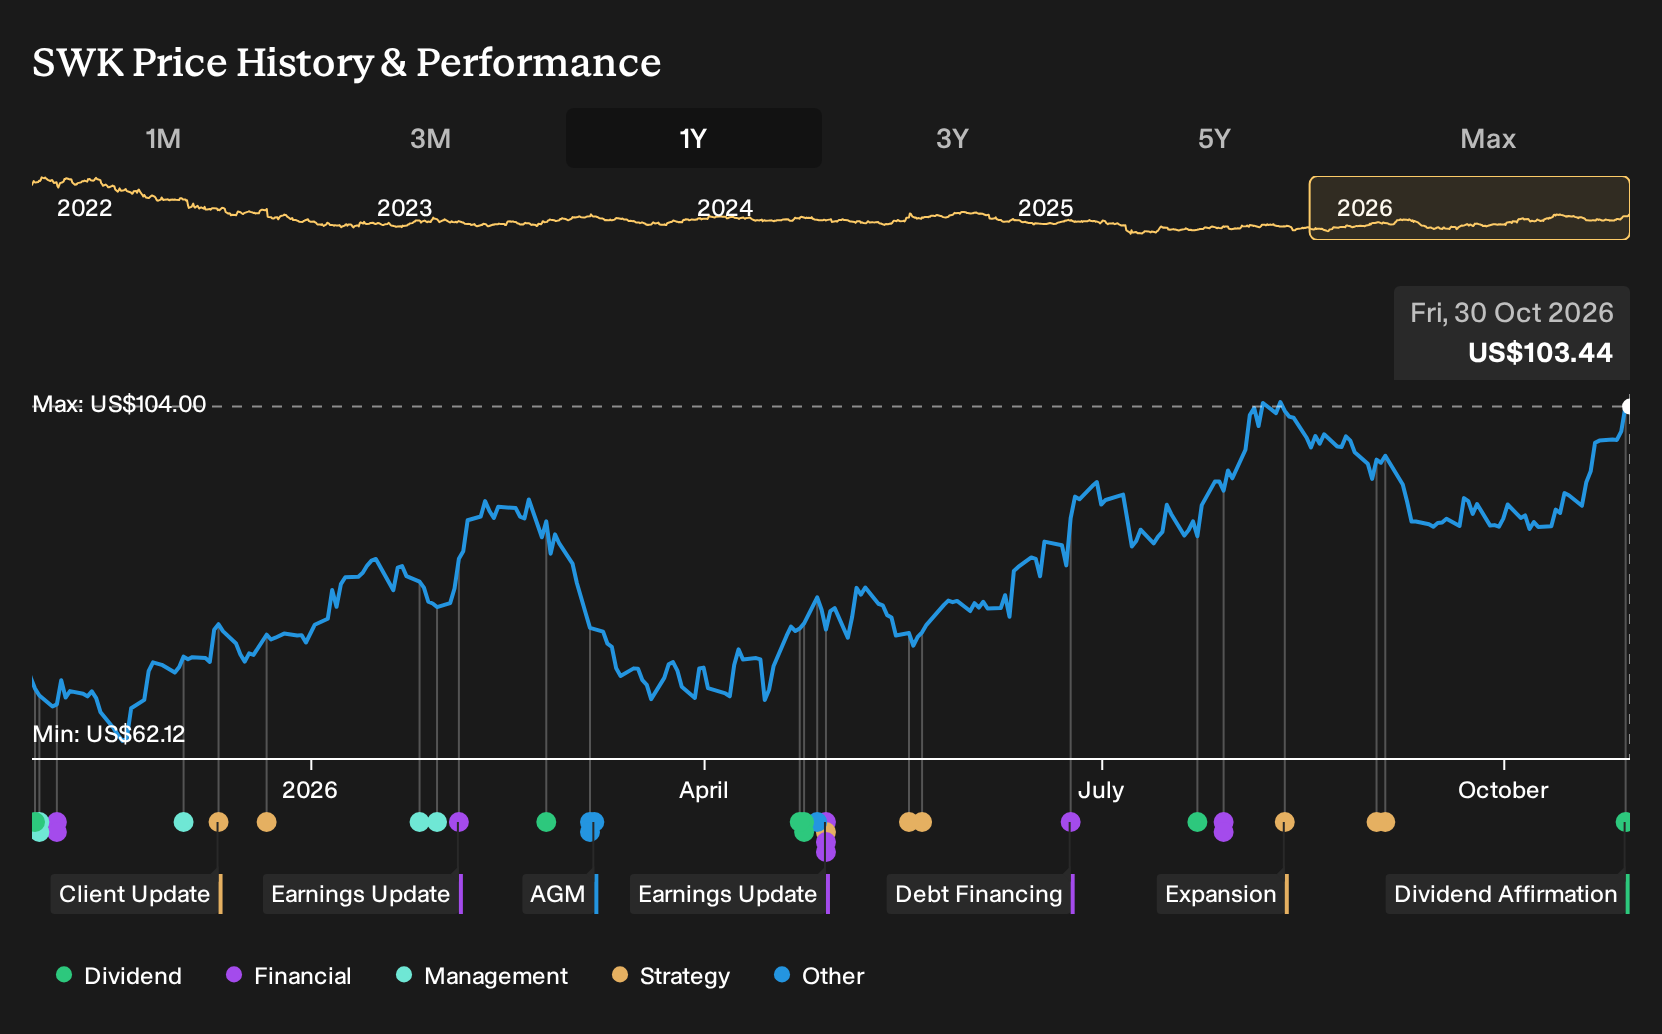
- Stanley Black & Decker declared a regular fourth quarter cash dividend of $0.84 per share, payable on December 22, 2026, to shareholders of record on December 1, underscoring continued cash returns to investors.
- The dividend decision arrives as Stanley Black & Decker is highlighted in industrial demand commentary, with earnings supported by global tool and fastening exposure.
- We will look at how Stanley Black & Decker's investment narrative is shaped by the affirmed dividend alongside industrial earnings.
Scan for more income ideas by comparing Stanley Black & Decker's dividend story with a curated group of 5 dividend fortresses on the Simply Wall St screener.
Stanley Black & Decker Investment Narrative Recap
To own Stanley Black & Decker, you need to believe its tools, outdoor equipment and fastening products can keep earning a solid place in both retail and industrial channels, despite soft DIY trends and tariff pressure. In the near term, the key swing factor remains execution on supply chain and cost programs rather than this quarter's dividend decision.
The biggest operational risk is that weak volumes, price-sensitive customers and concentration in large retailers keep organic growth flat while high debt limits flexibility. The affirmed US$0.84 dividend looks directionally supportive of the current plan but does not materially change the main earnings and demand catalysts investors are already watching.
The most relevant update here is the approval of the regular fourth quarter dividend of US$0.84 per share, tied to the December 1 record date and December 22 payment date. For an investor, that action sits alongside commentary that Stanley Black & Decker is exposed to industrial demand and micro fastener markets across autos, electronics and aerospace.
Income reliability depends on the business continuing to generate cash while managing tariffs, supply chain changes and pricing pressure. The dividend affirmation highlights management's current confidence, yet the main test for the stock remains whether industrial demand, cost reductions and any mix shift toward higher margin fastening and digital offerings translate into durable earnings progress.
Stanley Black & Decker's current analyst narrative points to forecast 2029 revenue of US$16.4b and earnings of US$1.1b, built on an assumed 2.5% yearly top line expansion and an earnings increase of about US$479.5m from US$620.5m today.
Uncover why Stanley Black & Decker's fair value indicates a 4% potential downside to its current price, which leaves little room for error.
Exploring Other Perspectives
Some of the most optimistic analysts lean hard into the micro fasteners and industrial story for Stanley Black & Decker. They were already modeling revenue around US$16.6b and earnings near US$1.3b by 2029 before this US$0.84 dividend decision, so you see a far more upbeat earnings path that could shift again as views get refreshed.
Explore 3 other Stanley Black & Decker fair value estimates, including one that suggests it could be worth as much as $103.39.
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Stanley Black & Decker research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Stanley Black & Decker. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Stanley Black & Decker's overall financial health at a glance.
Looking For More Investment Ideas Beyond Stanley Black & Decker?
Once you have a handle on Stanley Black & Decker, it helps to widen the lens and compare it with other opportunities using the Simply Wall St screener. That way you can see how its income profile, balance sheet and valuation stack up against different types of stocks.
- For investors who care most about resilience and financial strength, shortlist companies with robust balance sheets using the list of solid balance sheet and fundamentals (25 results) available on the screener.
- If you are hunting for quality at a measured price, scan a curated set of potential value opportunities by running the 29 high quality undervalued stocks directly in the tool.
- Those focused on building a steady income stream can compare Stanley Black & Decker's payouts against a wider universe by filtering for 5 dividend fortresses inside the screener.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com