


Sales Update Could Be A Game Changer For L'Oréal (ENXTPA:OR)
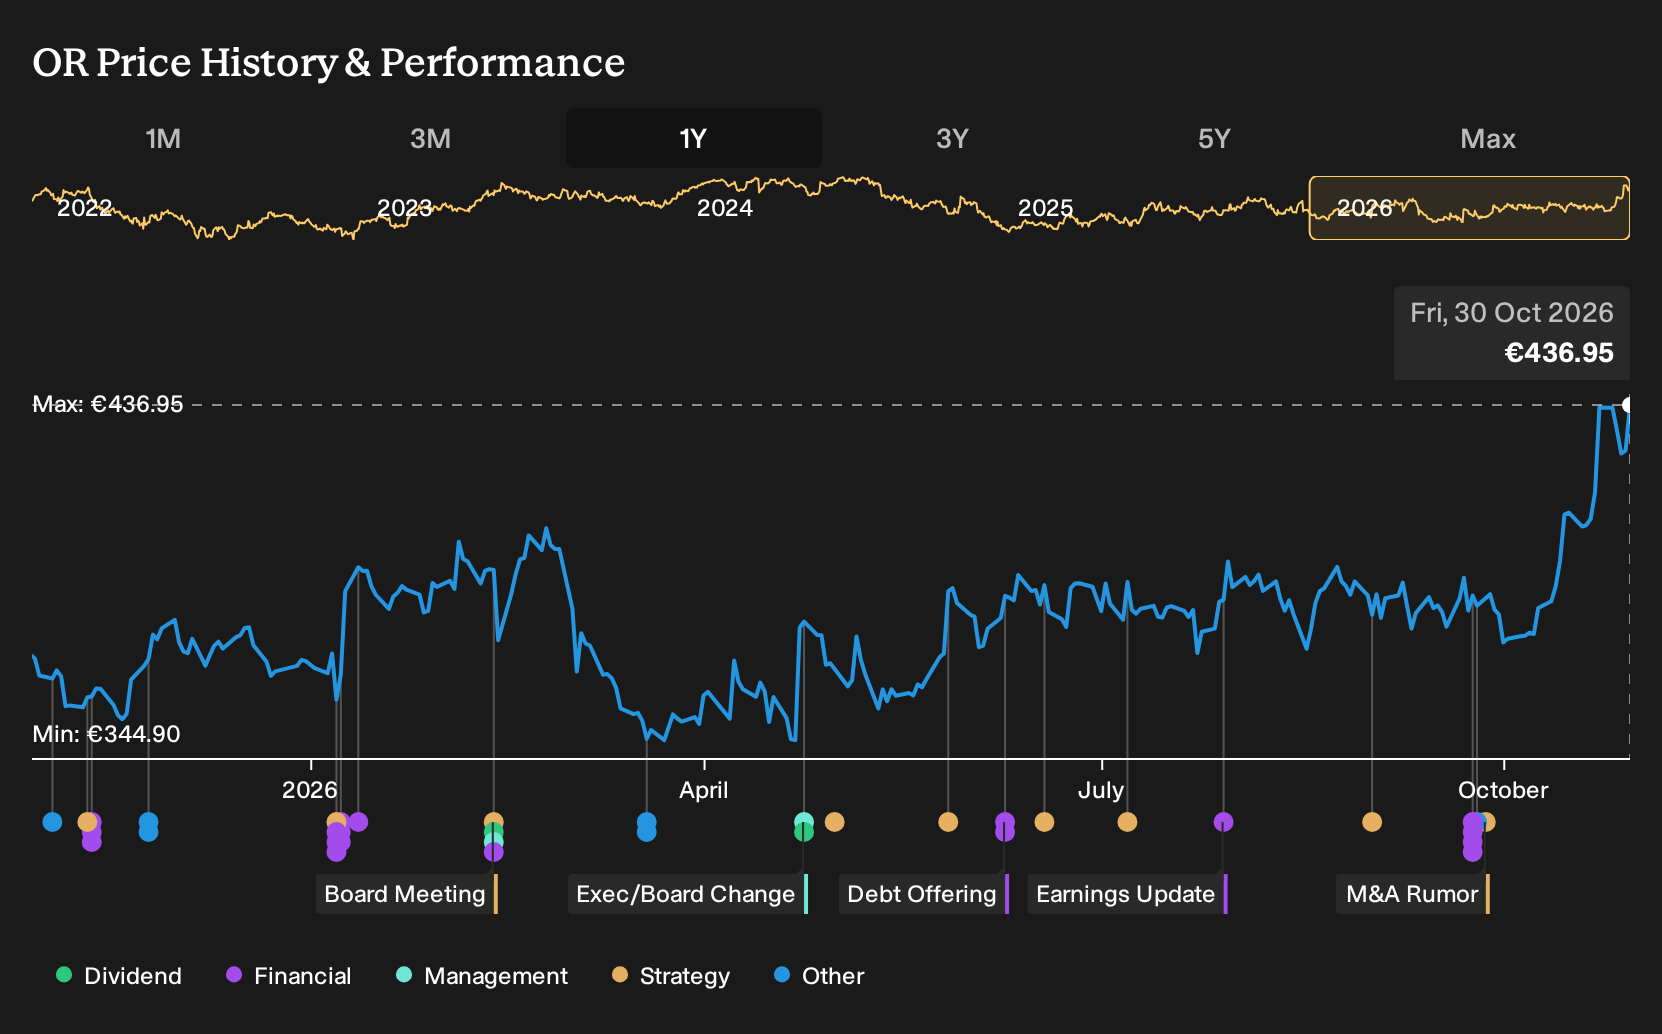
- L'Oréal reported unaudited group sales of €11,561.4 million for the third quarter of 2026 and €35,337.6 million for the first nine months, outlining its recent commercial performance.
- The size of L'Oréal's nine month sales base in 2026 gives investors detail on how the business is scaling across its portfolio and regions.
- This article examines how L'Oréal's updated nine month 2026 sales figures may affect the existing investment narrative around growth.
Scan L'Oréal's latest sales update against other consumer stocks by checking which peers are appearing in the 199 high quality undervalued stocks right now.
L'Oréal Investment Narrative Recap
To own L'Oréal, you need to trust that global beauty demand, especially in premium and dermatological products, remains resilient and that the group keeps refreshing brands fast enough to hold shelf space and online traffic. The fresh nine month sales figure of €35,337.6 million mainly reinforces that the business is still moving at scale rather than resetting the short term story.
The near term swing factor is whether L'Oréal keeps enough momentum in faster growing regions and e commerce to offset pressure from competition and evolving tastes. The biggest watchpoint remains brand relevance against local and indie rivals, along with any fallout from ongoing legal issues that could affect margins or marketing spend.
The most relevant update here is the unaudited sales disclosure itself. It shows L'Oréal delivering €11,561.4 million of quarterly revenue and €35,337.6 million over nine months. This gives you a clearer reference point when you weigh existing expectations on growth, profitability and returns on capital against what the business is actually generating through 2026.
With analysts already factoring in steady revenue expansion, growing online channels and premium mix, this sales run rate matters for how credible those catalysts look. If you are tracking the thesis around emerging markets, e commerce and higher value categories, these numbers help you judge whether execution risk is rising or easing without relying solely on sentiment.
What L'Oréal's Forecasts Build Into the Story
Analysts are effectively asking you to picture L'Oréal as a larger, more profitable version of itself by the end of the decade. Their models point to revenue increasing at 6.5% a year over the next few years and earnings rising from €6.3b today to a consensus estimate of €8.9b in 2029, with higher profit margins doing some of the heavy lifting.
The same forecasts imply that the stock would trade on a P/E of 30.6x those 2029 earnings, compared with 34.4x on current earnings. That profile assumes a gradual improvement in profitability and only a modest step down in the valuation multiple that investors are willing to pay. It also bakes in a small decline in the share count, with analysts expecting outstanding shares to fall by about 0.26% each year over the next three years.
On the revenue side, the consensus view is that L'Oréal could reach €54.7b of sales by 2029 and convert that into €8.9b of profit. At the same time, the group level net margin that sits at 13.9% today is modeled to move up to 16.2% over roughly three years, which would mean a higher share of each euro of turnover dropping through to earnings if things play out as anticipated.
L'Oréal's narrative projects €54.7b revenue and €8.9b earnings by 2029. This setup assumes revenue growth of 6.5% a year and an earnings increase of about €2.6b from current earnings of €6.3b.
For you as an investor, the key question is whether those revenue and margin assumptions feel realistic when set against the latest nine month sales base of €35,337.6m. The forecast path implies that online channels, premium beauty and faster growing regions do enough work to support both top line expansion and higher profitability. It also assumes that competition, regulation and legal issues stay contained enough not to knock that trajectory off course.
Uncover why L'Oréal's fair value indicates a 4% potential downside to its current price, which leaves little room for error.
Exploring Other Perspectives
Three fair value estimates from the Simply Wall St Community cluster between €418 and about €468, which already shows how far views on L'Oréal can stretch. You also need to weigh those personal models against risks such as intensifying local competition and legal overhangs, as well as potential catalysts including faster e commerce and emerging market growth.
Explore 2 other L'Oréal fair value estimates, including one that suggests as much as 7% upside from the current price.
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your L'Oréal research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for L'Oréal. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate L'Oréal's overall financial health at a glance.
Looking for more investment ideas beyond L'Oréal?
Once you have a view on L'Oréal, it helps to put those conclusions alongside other opportunities that fit different return and risk profiles. The Simply Wall St Screener lets you jump straight into shortlists that match what you care about most, whether that is value, resilience, or future growth potential.
- For investors who prize cash generation and balance sheet strength, start with a list of solid balance sheet and fundamentals (203 results) that already clears key financial quality checks.
- If you want ideas where market expectations still look muted, review the 602 high quality undiscovered gems that combine strong fundamentals with relatively low market attention.
- When capital preservation matters as much as upside, focus on a 218 resilient stocks with low risk scores that screens for companies with historically lower risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com