


Will Third Quarter Results Change Texas Pacific Land Stock Narrative
- Texas Pacific Land is preparing to report its third quarter 2026 results after a period of record royalty production and sustained demand for produced water transportation and disposal services in the Permian Basin.
- Investors are focusing on how expanding water management and infrastructure projects could reshape Texas Pacific Land's revenue mix alongside its royalty income base.
- We will examine how Texas Pacific Land's investment narrative is influenced by expectations for record royalty volumes and growing water services demand.
Scan beyond Texas Pacific Land and line up other Permian-exposed royalty and infrastructure plays using our curated 29 high quality undervalued stocks, which is built to highlight potential mispriced opportunities.
Texas Pacific Land Investment Narrative Recap
To own Texas Pacific Land, you need to be comfortable tying your capital to Permian Basin activity and the durability of its royalty and water businesses. The immediate story hinges on how record royalty volumes and higher produced water demand translate into near term cash generation. The upcoming third quarter 2026 update matters most for confirming that royalty production and water throughput are holding up.
The most important short term catalyst is whether water services and infrastructure continue to scale in a way that meaningfully diversifies Texas Pacific Land away from pure commodity exposure. The biggest risk is concentrated exposure to regulatory, environmental, and decarbonization pressure in the Permian. This earnings print does not remove those long term questions, but it can indicate how resilient current activity is.
The central announcement here is Texas Pacific Land’s plan to release third quarter 2026 results on 4 November. That disclosure will provide a clearer view of how the royalty stream and water segment performed after what management has described as record royalty production and firm demand for produced water handling.
This update matters for the catalyst debate because it will show whether water services are starting to carry more weight alongside royalties and whether margins in that segment look sustainable against rising scrutiny around water use in Texas. It also speaks directly to execution risk. Stronger usage of TPL’s infrastructure could support the case for more stable, fee based revenue, while any slowdown or cost pressure would highlight how exposed the business remains to Permian specific risks.
Texas Pacific Land's current analyst storyline points to revenue of US$1.3b and earnings of US$837.1m by 2029, built on an assumed 17.2% yearly revenue growth rate and an earnings increase of about US$333.5m from current earnings of US$503.6m.
Uncover why Texas Pacific Land's fair value indicates a 34% potential upside to its current price before the market closes the gap.
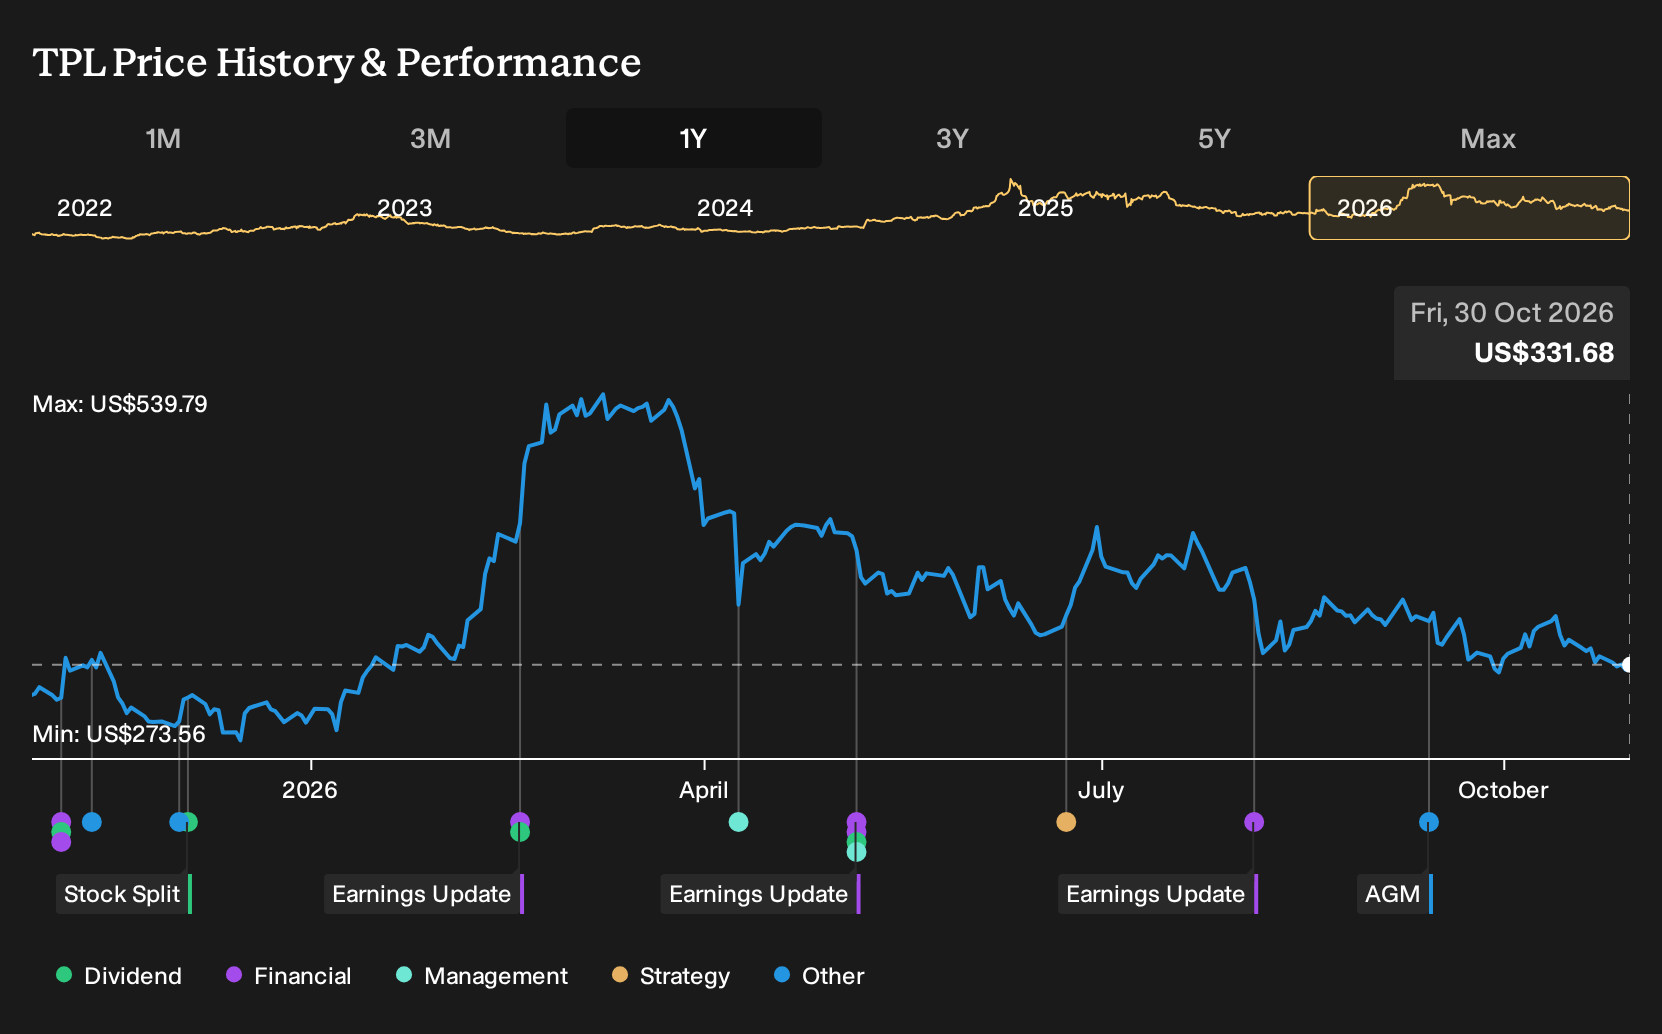
Exploring Other Perspectives
One alternate take on Texas Pacific Land leans hard on data center and power projects as the real swing factor. The lowest analysts were already baking in revenue of about US$1.5b and earnings near US$924.8m by 2029, yet still landed on a US$247 target. That gap shows how widely views can differ. Treat this earnings release as a chance to test several competing storylines yourself.
Explore 5 other Texas Pacific Land fair value estimates, including one that suggests as much as 26% downside from the current price!
Decide For Yourself
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Texas Pacific Land research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Texas Pacific Land. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Texas Pacific Land's overall financial health at a glance.
Looking for more ideas beyond Texas Pacific Land?
Once you have a view on Texas Pacific Land, widen your opportunity set by scanning other listed businesses that fit the kind of balance, income, or upside you want in your portfolio using the Simply Wall St Screener.
- If capital preservation sits high on your list, start with companies that show sturdier finances through our list of solid balance sheet and fundamentals (25 results).
- If you prefer cash returns in your account, focus on stocks that currently offer stronger income potential via the 5 dividend fortresses.
- If you are hunting for mispriced stories with room for sentiment to catch up, sort through our curated 18 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com