


What AutoZone (AZO)'s Commercial Sales Growth Means For Shareholders
- AutoZone reported strong domestic commercial sales growth in fiscal 2026, led by professional repair shops. The company also accelerated store openings, which can initially weigh on returns because new locations take time to reach mature profitability.
- Leadership changes add another layer to this shift. The current CFO is departing to join FedEx, and the vice president and controller is assuming principal financial and accounting officer responsibilities under securities regulations.
- Attention now turns to how AutoZone's growing commercial repair shop business, together with these finance leadership moves, could shape the broader investment narrative.
Scan how AutoZone's commercial shift compares with other repair focused retailers by checking a curated set of list of solid balance sheet and fundamentals (25 results)
AutoZone Investment Narrative Recap
To own AutoZone, you need to believe the commercial repair shop push, supported by Mega Hubs and heavy store openings, can more than offset pressure on do it yourself traffic and a slower Brazil expansion. The near term swing factor is whether high single to low double digit commercial growth actually shows up in same program sales and utilization of the new locations.
The main risk right now is execution. New stores and hubs start out earning very little, and the business already carries high debt and negative shareholders equity. The CFO transition looks manageable and does not obviously change the key near term catalyst or the central risk around returns on this build out.
The resignation of CFO Jamere Jackson and the handoff of principal financial and accounting officer duties to J. Scott Murphy matter most for how AutoZone funds and measures this investment cycle. Investors will likely watch capital allocation, store level return tracking and any tweaks to commercial growth priorities under the new finance setup.
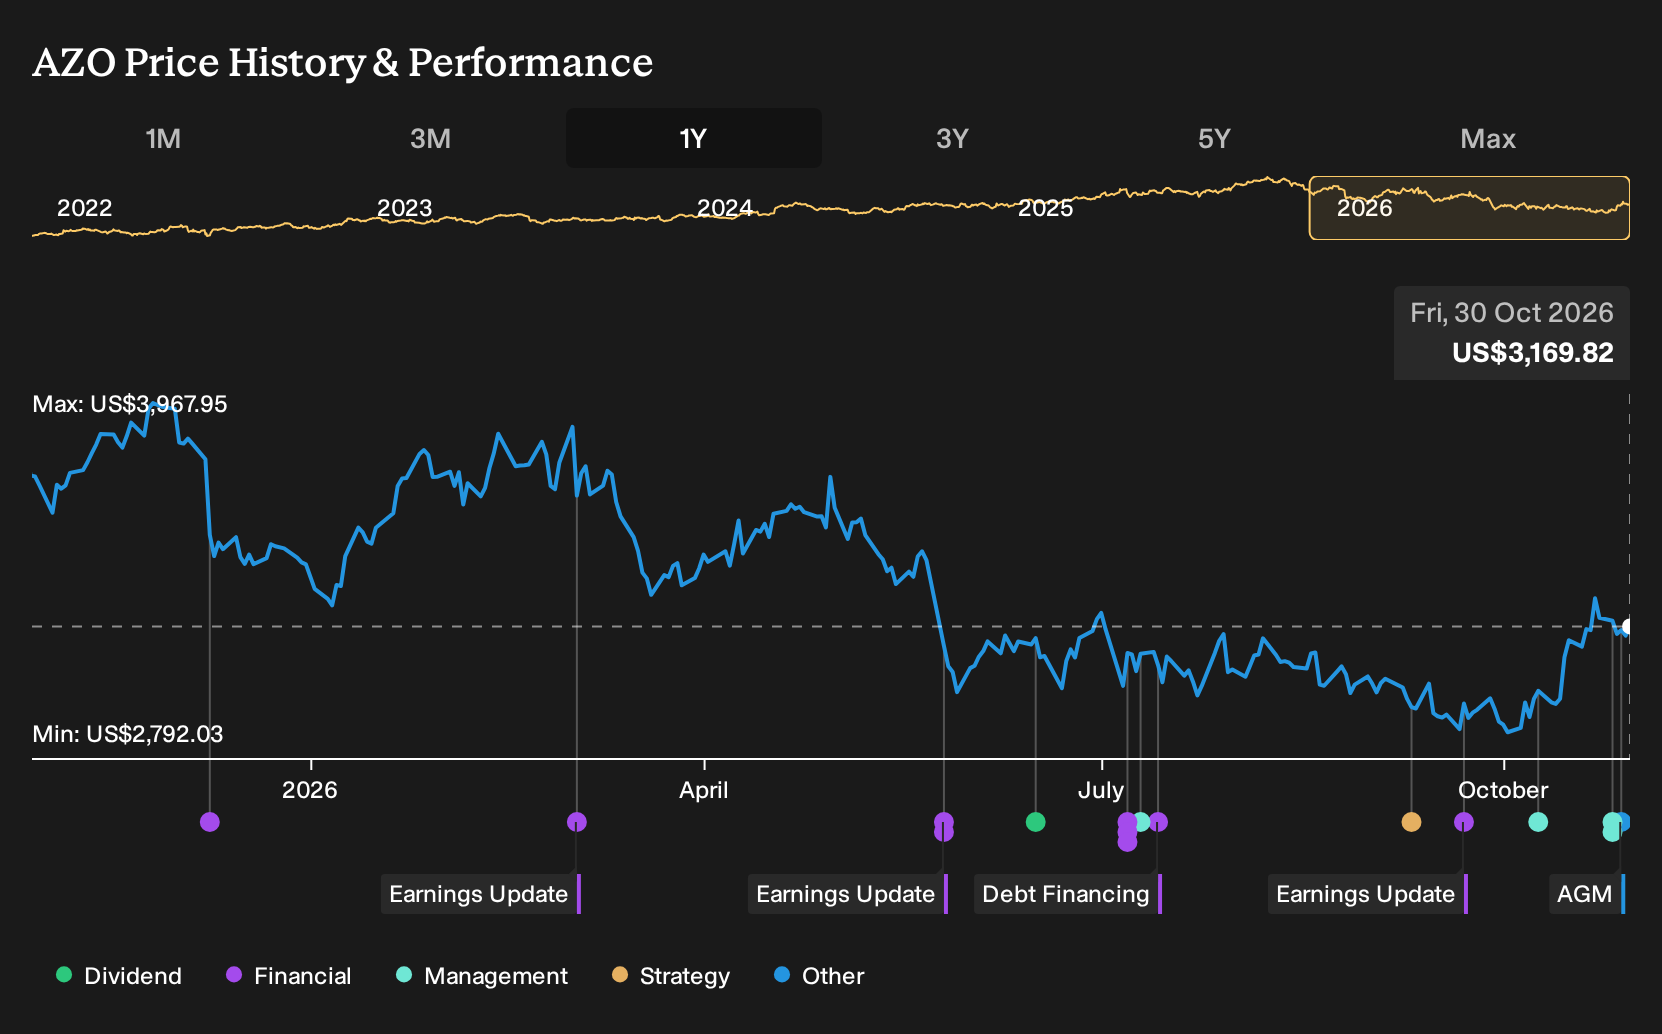
This leadership shift lands while AutoZone is spending heavily on new stores and Mega Hubs and running an ongoing buyback program. Smooth execution on these projects and clear financial communication from Murphy can support confidence in the commercial repair thesis. Any missteps could amplify concerns about leverage, slower DIY demand and recent share price underperformance.
AutoZone's current analyst setup points to revenue of US$24.9b and earnings of US$3.2b by 2029, based on 7.0% yearly top line growth and an earnings increase of about US$0.6b from US$2.6b today.
Uncover why AutoZone's fair value indicates a 17% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
Four fair value estimates from the Simply Wall St Community cluster between about US$2,829 and US$3,720, with some members seeing AutoZone as far closer to the upper end. You are weighing these pre news views against softer DIY traffic, heavy store spending and a CFO transition that could all shift how future forecasts look.
Explore 3 other AutoZone fair value estimates, including one that suggests as much as 11% downside from the current price.
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your AutoZone research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for AutoZone. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate AutoZone's overall financial health at a glance.
Looking for more investment ideas beyond AutoZone?
Once you have a view on AutoZone, it can help to scan a wider watchlist so you are not relying on a single story to carry your portfolio.
- If you want potential mispricings with quality fundamentals, start with a curated 29 high quality undervalued stocks.
- For investors who care most about resilience, narrow your focus to a 30 resilient stocks with low risk scores that screens for sturdier balance sheets and steadier track records.
- If you prefer companies that fly under the radar, broaden your opportunity set with a 18 high quality undiscovered gems that still screens on financial quality.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com