


NETSTREIT (NTST) Raises Guidance And Dividend After Earnings But Is It A Bargain
NETSTREIT (NTST) has just put several moving pieces on the table for investors, combining updated net investment guidance, a higher quarterly dividend, and detailed third quarter 2026 earnings results.
Recent price action around NETSTREIT reflects that story. The share price is down 18.3% over the past three months, while the 3 year total shareholder return is up 30.0%. This signals that longer-term holders have still seen positive compounding despite more cautious near-term sentiment around the latest earnings and guidance reset.
Scan beyond NETSTREIT and spot other income-focused real estate plays by reviewing our curated list of 5 dividend fortresses, which could fit a similar dividend and cash flow thesis.
NETSTREIT now trades at a clear discount to analyst targets after that 18.3% slide in three months. Is the market rightly skeptical, or is sentiment mispricing the earnings and dividend story that just unfolded?
Most Popular Narrative: 18% Undervalued
NETSTREIT’s most followed valuation narrative pegs fair value at $21.41, compared with the recent $17.52 close. This frames the latest pullback as a discount rather than a warning sign if those long range assumptions hold up.
Conservative use of NETSTREIT’s balance sheet, including adjusted net debt to annualized adjusted EBITDA of 3.2x and access to about US$1.1b of liquidity, together with raised net investment guidance of US$700 million to US$800 million for 2026, points to continued capacity for external acquisitions that can add to rental revenue and AFFO over time.
See why 5 investors see NETSTREIT as 18% undervalued.
Result: Fair Value of $21.41 (UNDERVALUED)
Still, if interest rates stay elevated or acquisition spreads compress further, the NETSTREIT narrative could shift, as external growth and valuation assumptions come under pressure.
Find out about the key risks to this NETSTREIT narrative.
Another View: NETSTREIT Looks Expensive On Earnings
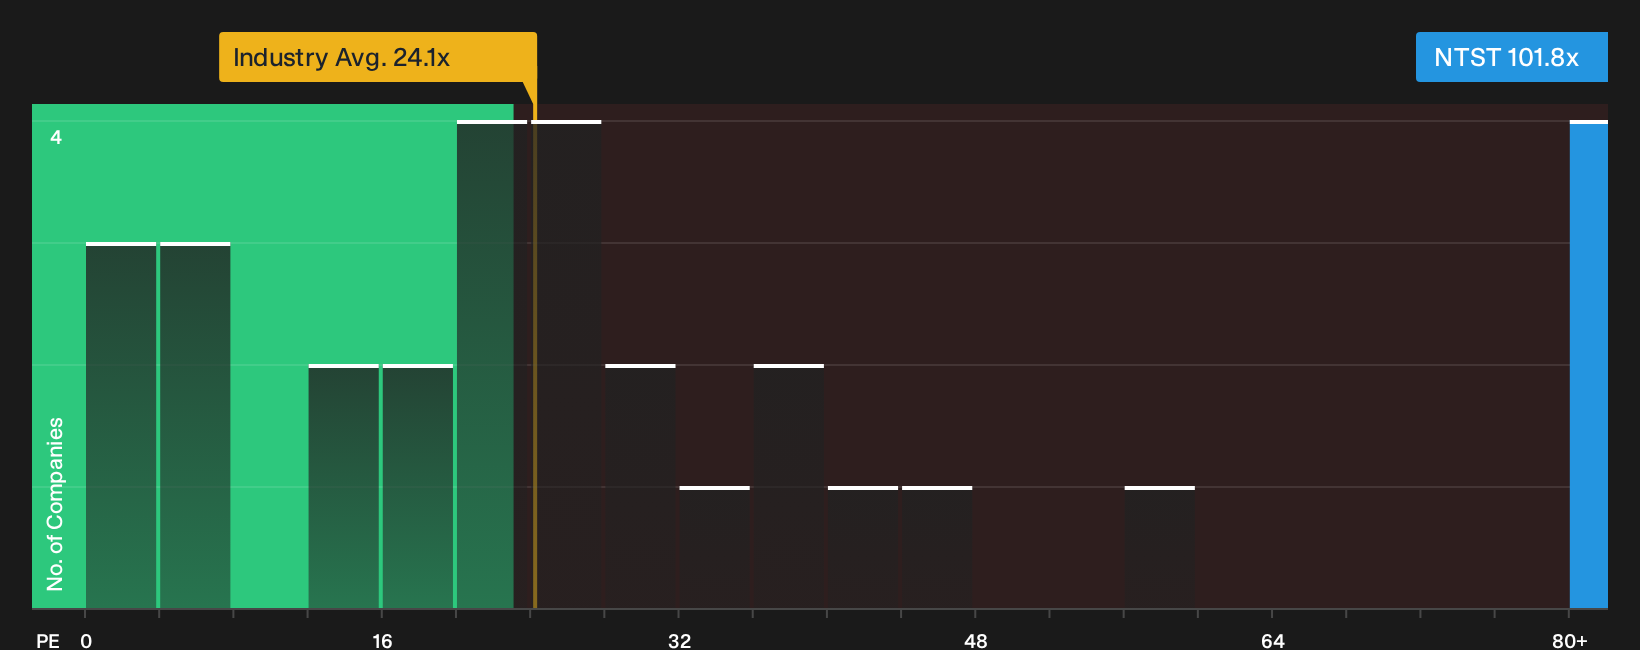
The fair value narrative paints NETSTREIT as materially undervalued, yet the simple P/E story points in the opposite direction. The stock trades on a P/E of 101.8x, compared with 25.3x for US Retail REITs, 46.6x for peers, and a fair ratio of 43.1x. That gap signals real valuation risk. Is the discount thesis strong enough to offset it?
For a closer look at how that rich earnings multiple stacks up against the numbers, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on NETSTREIT so far. If you want to move past the headline takes and form your own judgment quickly, start by weighing its 4 key rewards and 3 important warning signs.
Hunting For More Ideas Beyond NETSTREIT?
If NETSTREIT sharpened your focus on income, value, and balance sheet strength, do not stop here. Fresh opportunities rarely wait for slow decision makers.
- Target resilient income by scanning for companies in our 5 dividend fortresses that combine higher yields with disciplined fundamentals and consistent shareholder payouts.
- Pursue value-led upside through the 29 high quality undervalued stocks, where quality fundamentals and pricing gaps sit side by side for you to compare in minutes.
- Prioritise capital preservation with the 30 resilient stocks with low risk scores, built to surface businesses that pair sturdier financial profiles with lower overall risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com