


Cullinan Therapeutics (CGEM) Stock Dropped, So What Is Driving Attention Now?
Why velinotamig’s new trial matters for Cullinan Therapeutics
Cullinan Therapeutics (CGEM) just received clearance from U.S. and Australian regulators to begin a global Phase 1b/2a trial of velinotamig in difficult immune thrombocytopenia and warm autoimmune hemolytic anemia.
Against this backdrop, Cullinan Therapeutics shares trade at US$15.03 after a 1-day share price return that declined 2.72%. This caps a choppy few months where the 90-day share price return fell 8.91%, but the year-to-date share price return is up 48.52% and the 1-year total shareholder return has reached 73.56%. These moves suggest that investors have been reassessing both the opportunity in velinotamig and recent zipalertinib data while weighing higher near term volatility against a potentially stronger long term payoff profile.
Scan 34 healthcare AI stocks that, like Cullinan Therapeutics, are pushing immunology and complex disease research forward and could see sentiment swing quickly as new trial data lands.
After a 73.56% 1-year total return and fresh trial momentum for velinotamig, is most of Cullinan Therapeutics’ rerating already behind it, or does the current US$15.03 price still leave meaningful upside on the table?
Most Popular Narrative: 55% Undervalued
Cullinan Therapeutics last closed at $15.03 while the most followed narrative pegs fair value at $33.55. The gap between today’s price and that estimate is wide and hinges heavily on how its T cell engager and EGFR programs play out over time.
Emerging data for CLN-978 as a subcutaneous CD19 T cell engager that induces drug free remission and deep B cell depletion in refractory SLE and RA positions Cullinan Therapeutics for entry into autoimmune indications that may broaden the company’s revenue mix and reduce reliance on any single oncology asset.
See why 1 investors see Cullinan Therapeutics as 55% undervalued.
Result: Fair Value of $33.55 (UNDERVALUED)
Still, the analyst story around Cullinan Therapeutics can break if safety issues, such as adverse event related deaths in zipalertinib combinations, persist or if revenue ramps slower than the current 2029 forecasts assume.
Find out about the key risks to this Cullinan Therapeutics narrative.
Another View: What Cullinan Therapeutics’ P/B Says
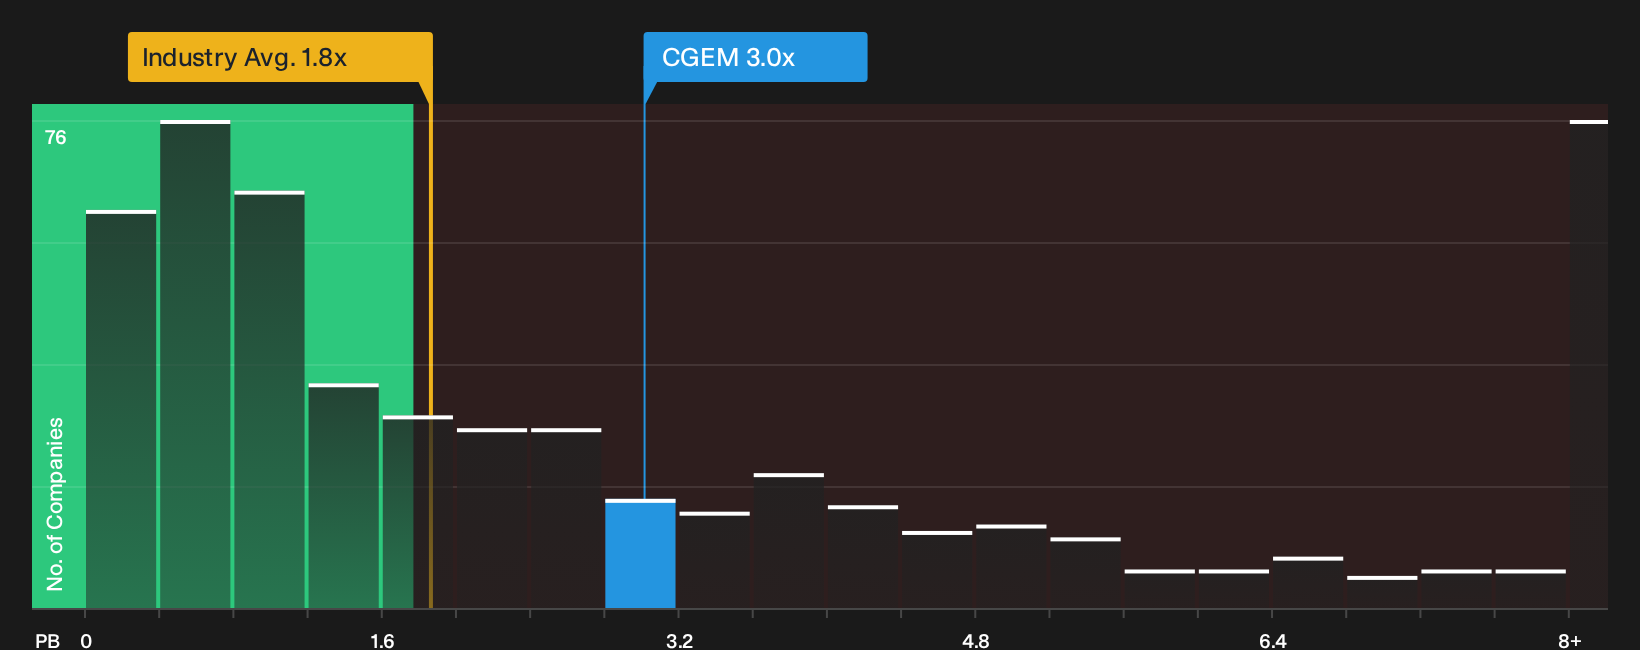
The story looks very different once you shift from fair value narratives to a simple price tag. Cullinan Therapeutics trades on a P/B of 3x, while the US Biotechs group averages about 2x and peers sit closer to 2.1x. That richer multiple can signal confidence, but it also raises the risk that any clinical setback or funding concern leads to sharper price swings than a plain “undervalued” label suggests.
For investors weighing that gap, the question is simple: Does the current premium feel like a reasonable price for pipeline optionality, or is it a sign expectations already lean too far ahead of the data?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If this mix of optimism and caution around Cullinan Therapeutics feels familiar, do not sit on the sidelines and let others frame the story for you. Review the latest balance of upside potential and downside warnings through the 2 key rewards and 4 important warning signs.
Looking for more investment ideas beyond Cullinan Therapeutics?
Do not stop your research with Cullinan Therapeutics when a wider opportunity set could fit your goals just as well or even better.
- Target resilient cash flows and stronger financial footing by reviewing a curated list of solid balance sheet and fundamentals (25 results) that can help anchor a more durable portfolio core.
- Hunt for mispriced opportunities by scanning a focused 18 high quality undiscovered gems that might not yet be crowded with attention but still show solid fundamentals.
- Stack potential income streams by checking out a hand picked set of 5 dividend fortresses that can support a returns profile less reliant on price moves alone.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com