


PPL (PPL) Gains Bullish Earnings Backing As Valuation Debate Builds
Recent optimism around PPL (PPL) has been driven by expectations for higher earnings and revenue in the upcoming quarterly release, with sentiment also tied to its regulatory backdrop, financing approach, and capital investment plans.
PPL’s recent move has been more than a one week blip, with a 30 day share price return of 8.39% helping to lift year to date gains. Longer term investors still sit on a 3 year total shareholder return of 55.19% and a 5 year total shareholder return of 47.60%, suggesting momentum has cooled from earlier years but has started to build again ahead of the upcoming earnings update.
Scan how PPL compares with other utilities gearing up for their next move by checking our curated list of 39 power grid technology and infrastructure stocks in one place.
The recent 8.39% 30 day jump has pulled PPL closer to analyst targets, yet its own intrinsic estimate points in the opposite direction. Where does fair value really sit between those two anchors?
Most Popular Narrative: 11% Undervalued
PPL’s most followed narrative pegs fair value at $40.13 using a 7.24% discount rate, compared with a last close of $35.65, so the story leans toward undervaluation even after the recent rebound.
The accelerating growth in data center construction and new economic development, now supported by roughly 32 GW of advanced stage projects in Pennsylvania and a 13.7 GW pipeline in Kentucky, continues to point to sizable future load additions for PPL that are expected to require more infrastructure and support higher regulated revenue over time.
See why 18 investors see PPL as 11% undervalued.
Result: Fair Value of $40.13 (UNDERVALUED)
Still, the PPL story hinges on regulators staying supportive of multi year capex recovery and on large data center projects in Pennsylvania and Kentucky actually materialising as planned.
Find out about the key risks to this PPL narrative.
Another View: What P/E Says About PPL
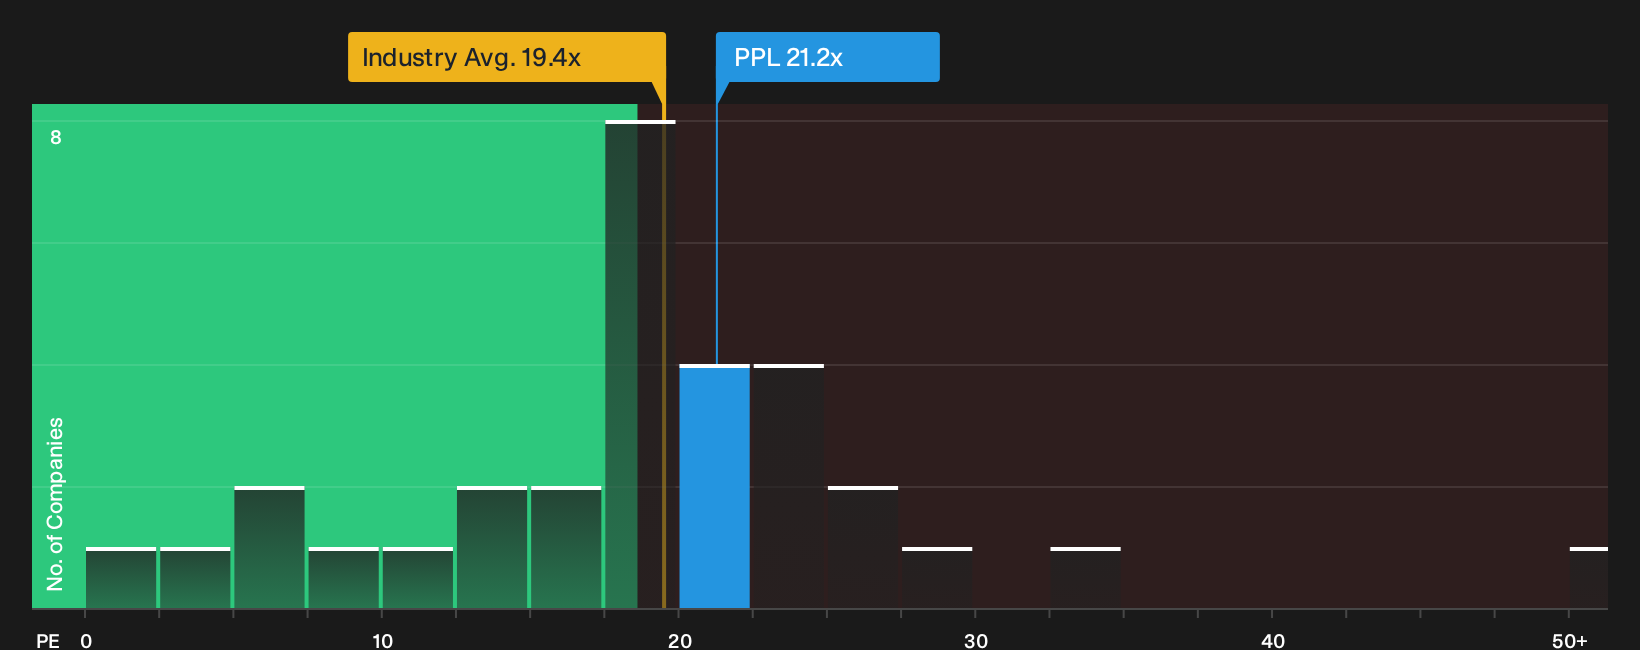
While the PPL narrative leans on a fair value of $40.13, the current P/E of 21.2x tells a more cautious story. It is slightly above the fair ratio of 21.1x, above the US Electric Utilities industry at 20.2x, and well above peer averages at 14.1x, which points to less room for error if growth or regulation disappoints. If the market leans on earnings multiples again, does that small premium feel like comfort or risk to you?
For a closer look at how this earnings based view stacks up against the broader valuation picture, check the See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages around PPL’s value and growth potential can pull you in both directions, so move quickly, test the assumptions, and weigh the 2 key rewards and 2 important warning signs
Looking for more investment ideas beyond PPL?
If PPL has your attention, do not stop here. Broaden your watchlist with other opportunities that match your style before they move without you.
- Target resilience by scanning a 30 resilient stocks with low risk scores that focuses on companies with steadier risk profiles and potentially smoother rides through choppy periods.
- Hunt for quality at a discount by checking a 29 high quality undervalued stocks that filters for stronger fundamentals paired with prices that may not fully reflect them yet.
- Prioritize balance sheet strength by reviewing a list of solid balance sheet and fundamentals (25 results) that highlights businesses backed by sturdier finances and fewer funding pressure points.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com