


Royalty Pharma (RPRX) Nears Q3 Earnings, Is The Upside Already Priced In?
Royalty Pharma (RPRX) heads into its upcoming Q3 2026 earnings release with investor attention focused on analyst expectations for higher revenue and earnings per share, as well as the performance of key royalty streams.
Royalty Pharma’s share price has climbed 15.1% over the past month and 72.9% year to date, lifting the stock to US$67.19 and building clear positive momentum. A 1 year total shareholder return of 82.5% and a 3 year total shareholder return of about 1.6x highlight how strongly longer term holders have been rewarded as sentiment around its royalty portfolio and upcoming earnings updates has shifted in its favor.
Scan Royalty Pharma’s royalty driven momentum against other potential opportunities by reviewing the hand picked 18 high quality undiscovered gems in the broader healthcare and biotech space.
After a 1-year gain above 80% and a share price now slightly above the average analyst target, the puzzle is whether Royalty Pharma still trades at a discount to its own fundamentals or the market’s caution is better grounded.
Most Popular Narrative: 3% Overvalued
On the most followed view, Royalty Pharma screens as slightly overvalued, with an implied fair value of $65.13 against the latest $67.19 close. The debate therefore shifts from price to whether the growth and cash flow story can justify that premium using a 7.2% discount rate.
Growth in synthetic royalty financing and late stage R&D co funding, which has reached about 5% of the roughly US$290b raised by unprofitable biotechs over the last five years, gives Royalty Pharma a larger pool of deals that can feed future portfolio receipts and earnings.
See why 31 investors see Royalty Pharma as 3% overvalued.
Result: Fair Value of $65.13 (OVERVALUED)
Still, this narrative can crack if the royalty dispute over Alyftrek drags on at a lower rate or if capital intensive deals continue to squeeze free cash flow margins.
Find out about the key risks to this Royalty Pharma narrative.
Another View: Royalty Pharma Through A Cash Flow Lens
The first take says Royalty Pharma looks about 3% overvalued at $67.19 compared with a $65.13 fair value built from analyst earnings assumptions. A very different picture comes from our DCF model, which points to a future cash flow value of $207.76, implying the stock trades well below that estimate.
For anyone weighing these two signals, the question is simple. Which set of assumptions feels closer to how you think Royalty Pharma’s royalty streams and reinvestment decisions will play out over time, and how comfortable are you with the gap between them.
Look into how the SWS DCF model arrives at its fair value.
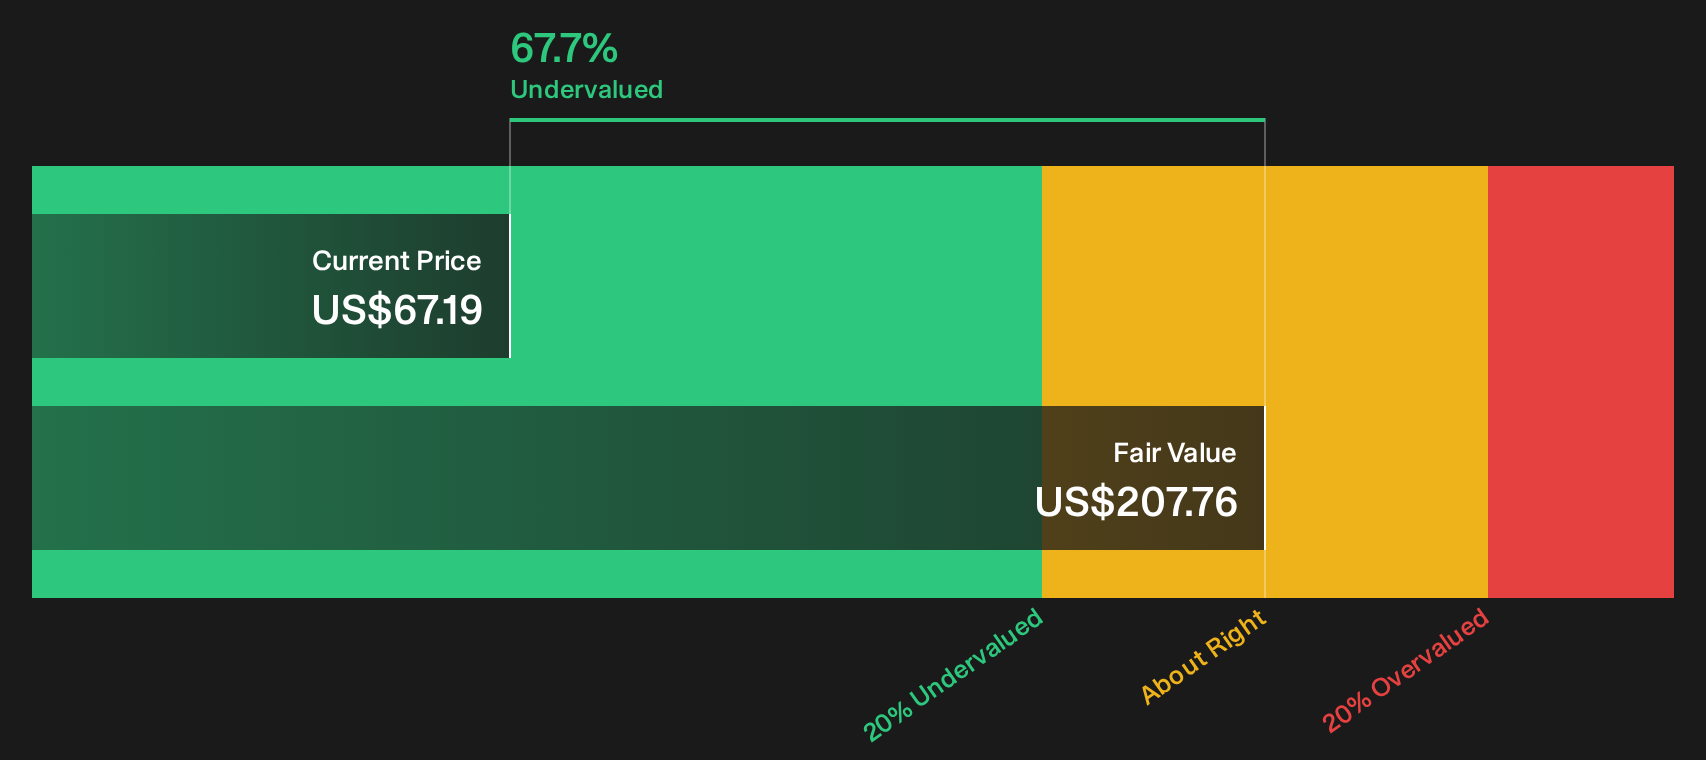
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Royalty Pharma for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 29 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Sentiment around Royalty Pharma is clearly split, with some investors focusing on upside potential and others worried about specific pressure points. If you want to move quickly from headline reactions to your own grounded thesis, start by weighing the 2 key rewards and 2 important warning signs
Looking for more Royalty Pharma style investment ideas?
If you want broader context around Royalty Pharma, use that curiosity to refresh your watchlist with a few focused screens that surface different types of opportunities.
- Target resilient cash generators and compare Royalty Pharma with a 29 high quality undervalued stocks that blend strong balance sheets with pricing that still looks restrained.
- Strengthen your income stream by scanning beyond Royalty Pharma and reviewing 5 dividend fortresses that may better align with your payout goals.
- Pressure test your risk tolerance by setting Royalty Pharma alongside 30 resilient stocks with low risk scores where business quality and balance sheet resilience sit front and center.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com