


Learn Why The Bull Case For PENN Entertainment Stock Could Change Following Earnings Preview
- PENN Entertainment is preparing to report results for the quarter ended September 2026, with Wall Street expecting higher revenue and year-over-year earnings growth.
- The key twist is that the Most Accurate Estimate and Earnings ESP both sit below consensus, which points to growing concern about near term profitability despite revenue expectations.
- This article examines how PENN Entertainment's investment narrative is affected by higher revenue expectations alongside a more cautious earnings ESP signal.
See how PENN Entertainment compares with other potential breakout candidates by running through our curated 29 high quality undervalued stocks for ideas with stronger earnings sentiment signals.
PENN Entertainment Investment Narrative Recap
To own PENN Entertainment, you need to believe the mix of physical casinos and interactive betting can eventually translate into durable, profitable cash flow. The near term story still hinges on whether ESPN BET integration, omni channel loyalty and new property projects can lift digital losses while offsetting pressure in mature regional markets.
The latest earnings setup, with higher revenue expectations but a more cautious near term profit signal, makes execution the key short term catalyst. Earnings quality and cash generation from Interactive now matter more than headline growth. The biggest immediate risk remains that competitive intensity and higher gaming taxes keep profitability under strain.
The most relevant update here is the earnings preview for the September 2026 quarter, where Wall Street is looking for higher revenue and improved earnings versus a year ago. For you, the focus is not the consensus itself. It is whether PENN Entertainment can translate its ESPN ecosystem tie up and omni channel strategy into cleaner operating leverage.
A negative Earnings ESP alongside slightly firmer EPS expectations tells you the near term bar on profitability is tricky. Any miss on digital losses, tax drag or interest expense could blunt the impact of higher sales. That is why this upcoming report is a useful test of PENN Entertainment's ability to execute on its core catalysts without letting risks widen.
PENN Entertainment's narrative projects US$8.3b revenue and US$466.8m earnings by 2029. That outlook assumes 4.9% yearly revenue growth and an earnings swing of roughly US$1.37b from a loss of US$906.7m today.
Uncover why PENN Entertainment's fair value indicates a 53% potential upside to its current price that may not last much longer.
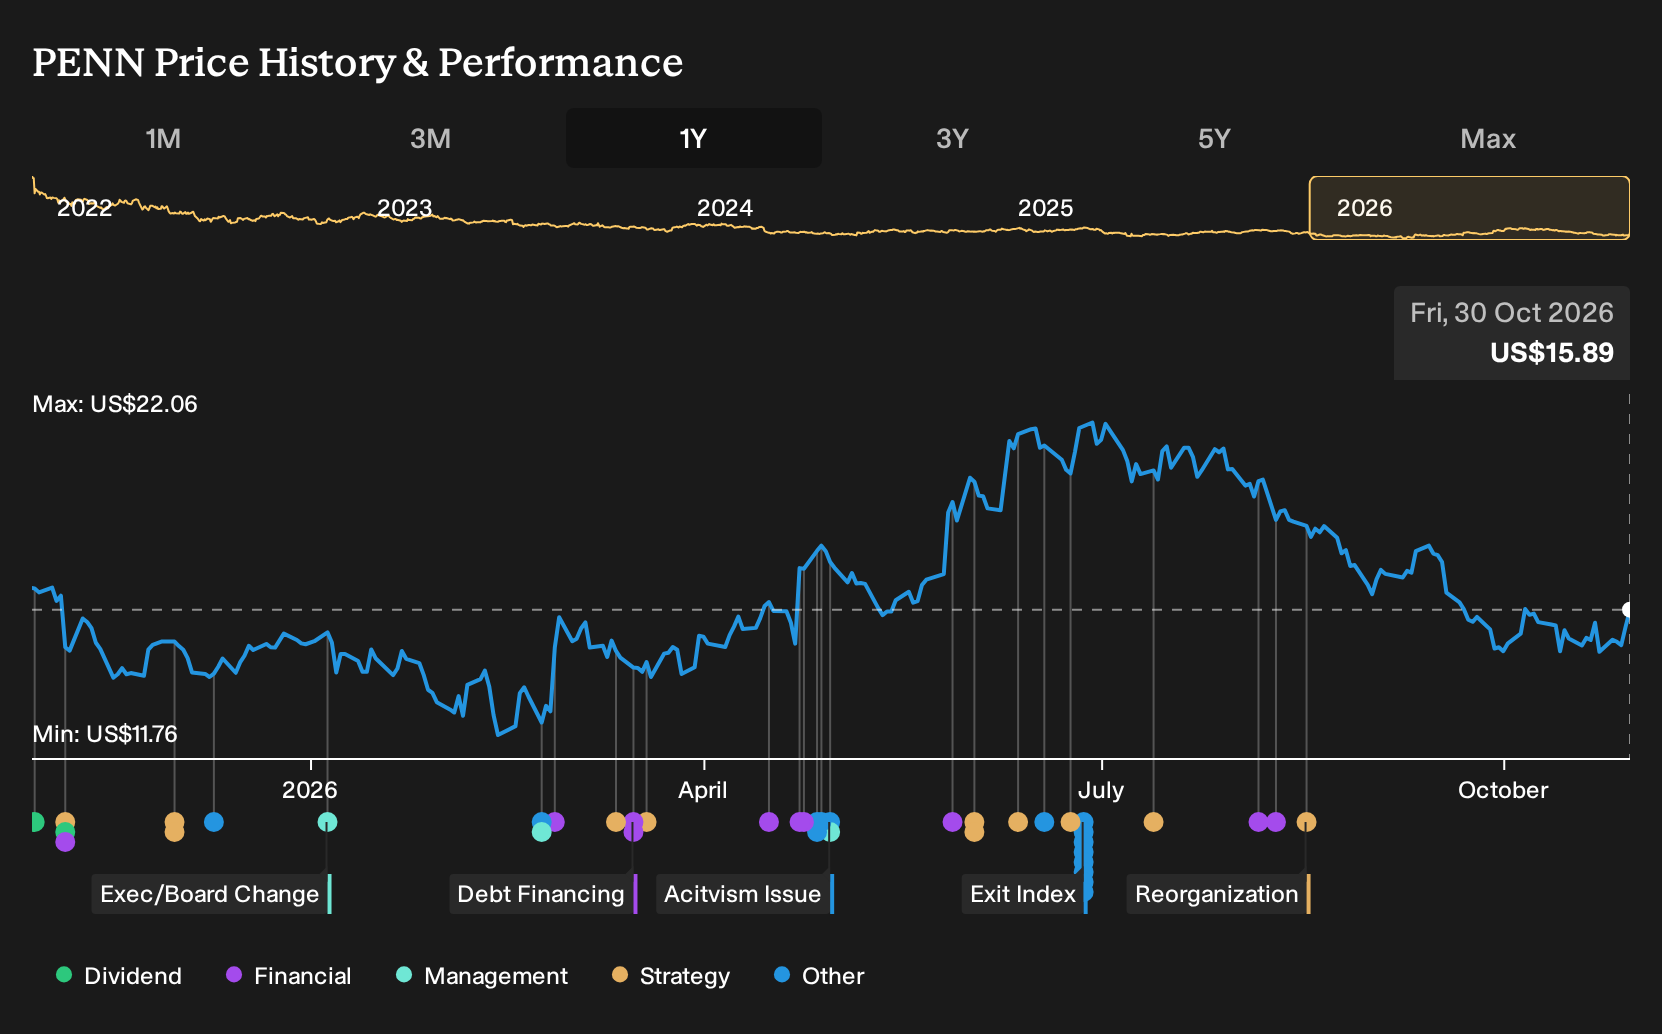
Exploring Other Perspectives
For PENN Entertainment, the sharpest contrast comes from the bearish focus on potential historical horse racing devices in Massachusetts. Those analysts were working off a backdrop where they projected about US$7.7b of revenue and US$302.9m of earnings by 2029, far below consensus, and viewed this regulatory risk as a direct threat to that already cautious setup. You can see how opinions vary widely, so it makes sense to explore several viewpoints and then decide how this new earnings update might reshape your own expectations.
Explore 4 other PENN Entertainment fair value estimates, including one that suggests it could be worth just $23.47!
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your PENN Entertainment research is our analysis highlighting 4 key rewards that could impact your investment decision.
- See our latest analysis for PENN Entertainment. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate PENN Entertainment's overall financial health at a glance.
Looking for more PENN Entertainment style investment ideas?
If PENN Entertainment has you thinking about where risk and reward line up best, it can help to scan a wider field of potential opportunities using the Simply Wall St Screener.
- For investors who want quality at a discount, filter for companies with stronger fundamentals and sentiment using our curated 29 high quality undervalued stocks.
- If capital protection is front of mind, focus on businesses with steadier profiles by reviewing a 30 resilient stocks with low risk scores that may better fit your risk tolerance.
- When balance sheet strength is non negotiable, zero in on financially robust operators through a list of solid balance sheet and fundamentals (25 results) that highlights more resilient options.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com