


What Telia Company Shares 5G Network Means For Shareholders
- Telia Company reported third quarter 2026 sales of SEK 21,306 million and net income of SEK 2,704 million, alongside a shared 5G radio access network plan in Norway with operator Ice and the continued rollout of commercial 5G standalone services.
- The combination of more data on recent earnings and a cost focused 5G sharing deal in Norway provides a clearer view of how Telia Company is trying to balance capital intensity, network quality and long term service demand across its Nordic footprint.
- We will now see how Telia Company's investment narrative could evolve as 5G sharing with Ice reshapes cost and capacity expectations.
Telia Company Investment Narrative Recap
To stay invested in Telia Company, you need to be comfortable with a slow growing Nordic telecom focused on connectivity, bundled services and disciplined capital use. The latest quarter put some weight behind that view, with SEK 21,306 million in sales and SEK 2,704 million in net income supporting the case for a still cash generative profile.
The key short term swing factor remains Norway, where profitability has been under pressure. The planned 5G sharing arrangement with Ice points to future cost relief, but the impact is not immediate. Competitive intensity in Finland and pressure on Swedish broadband ARPU still sit as the biggest operational risks to watch.
The shared 5G radio access network in Norway looks most relevant for the current story. Telia Company is targeting NOK 300 million to NOK 400 million in annual cost and capex savings from 2029, alongside better coverage and capacity, while each operator keeps its own core network and commercial proposition.
For you as an investor, the interest is in execution. If Telia Company can use this shared build to contain capex and energy costs while maintaining service quality in a tough Norwegian market, it could ease one of the major earnings headwinds. Any setbacks in rollout, regulation or service quality would quickly erode that potential benefit.
Telia Company Analyst Expectations and 5G Investment Frame
Analyst models around Telia Company currently knit together the 5G build, cost programs and portfolio reshaping into a relatively tight earnings path. Consensus pencils in revenue growth of 2.0% a year over the next three years, paired with an uplift in profit margins from 6.4% today to 12.7% by around 2029, which effectively assumes that cost discipline and network sharing offset pressure in Norway and Finland.
On the earnings line, forecasts cluster around SEK 11.2b by 2029 against current earnings of SEK 5.3b. That implies a projected increase of roughly SEK 5.9b over the period, with some analysts going as high as SEK 13.1b if execution on 5G, convergence and cost cuts tracks better than the base case. For your purposes, the gap between today and that SEK 11.2b outcome can act as a simple reality check on how much improvement you think is achievable from the 5G sharing in Norway, broadband repricing in Sweden and efficiency programs across the region.
Telia Company's narrative links these earnings expectations to a specific valuation anchor. Consensus views assume that by 2029 the group generates SEK 88.5b in revenue and SEK 11.2b in earnings, with the shares trading on a P/E of 19.8x, compared with about 35.9x today and a current sector multiple around 34.5x. That implies investors would be paying a lower earnings multiple in return for higher margins and a more focused connectivity profile that leans on recurring service contracts and a more efficient 5G network footprint.
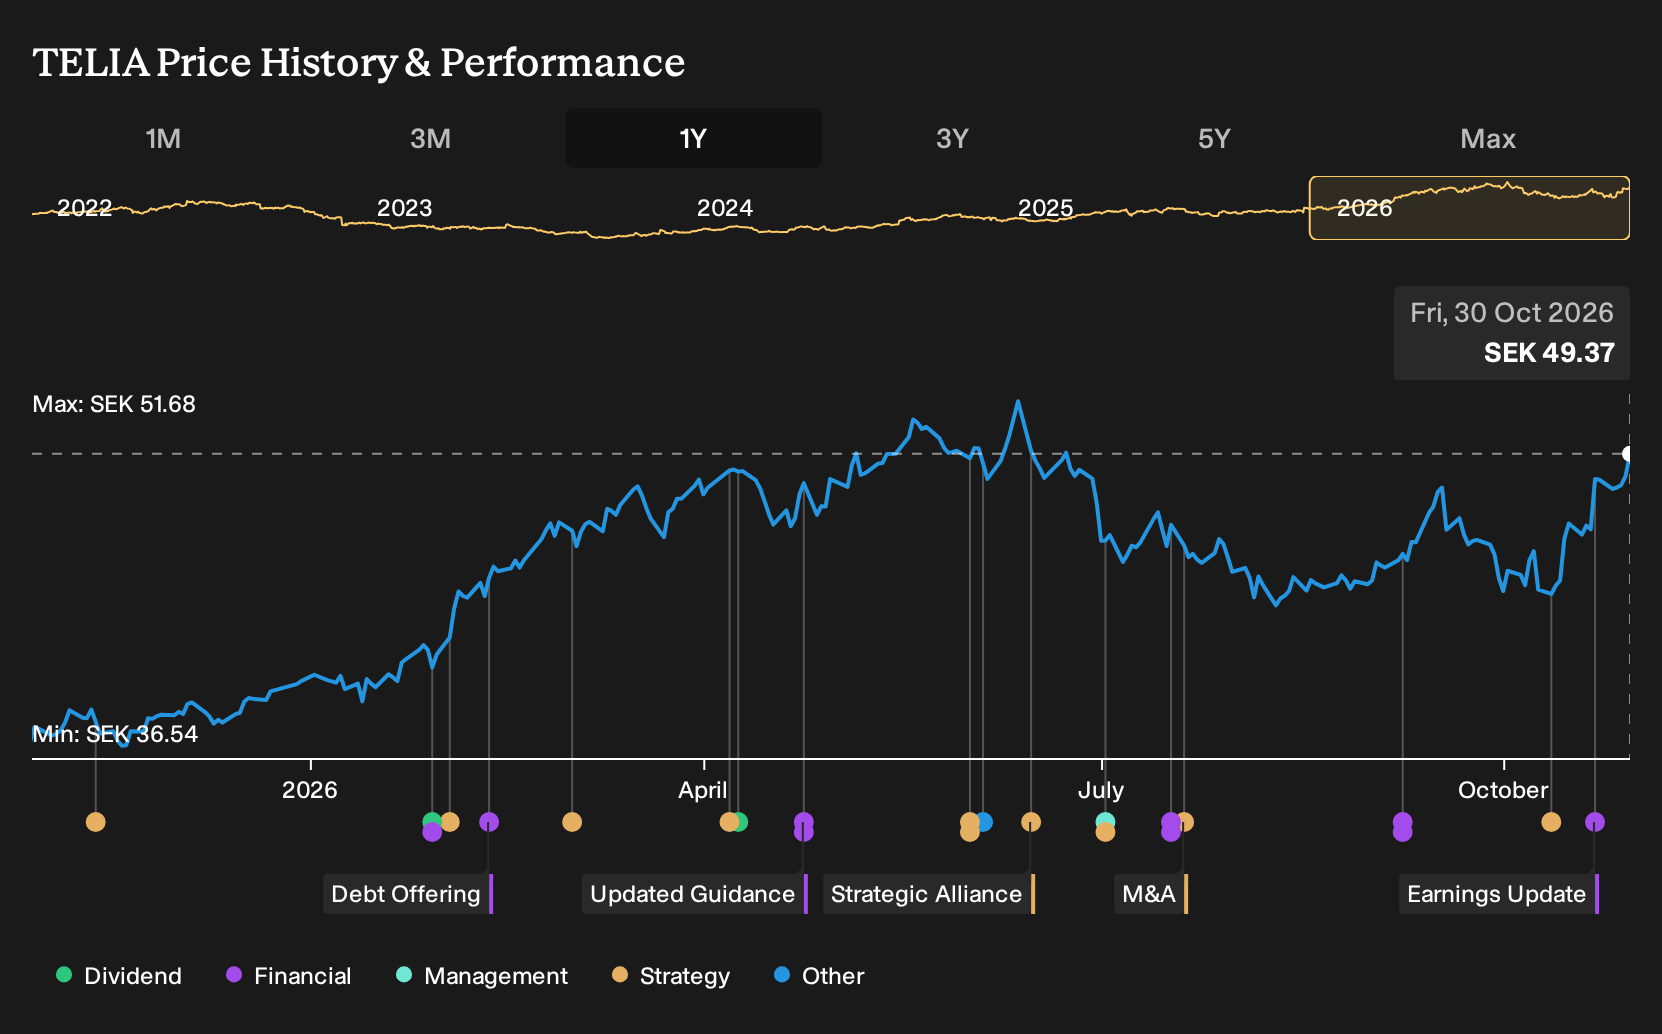
Putting that into price terms, analysts on average see a target of SEK 48.05 per share against a current quote of SEK 48.23, only 0.4% lower. That narrow gap suggests the market price already broadly reflects the consensus story around moderate revenue expansion, margin repair and the Norway 5G sharing upside, leaving less room for error if execution slips or if Norwegian competition and Swedish broadband pricing prove tougher than expected.
Telia Company's current consensus path points to revenue of SEK 88.5b and earnings of SEK 11.2b by 2029. This assumes 2.0% yearly revenue growth and an earnings increase of about SEK 5.9b from SEK 5.3b today.
Uncover why Telia Company's fair value indicates a 3% potential downside to its current price, which leaves little room for error.
Exploring Other Perspectives
You have a very different story if you focus on the bearish Telia Company view that worries about structurally weaker Swedish broadband pricing. Those analysts were only pencilling in revenue of SEK 83.3b and earnings of SEK 11.1b by 2029 before this news. That more cautious camp might now revisit its thesis, and you can compare these forecasts with your own expectations.
Explore 3 other Telia Company fair value estimates, including one that suggests it could be worth just SEK 48.05.
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Telia Company research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Telia Company. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Telia Company's overall financial health at a glance.
Looking For More Ideas Beyond Telia Company?
If you want to round out your view beyond Telia Company and build a broader watchlist, the Simply Wall St Screener can help you quickly surface other stocks that fit different risk and income profiles.
- If you prefer steadier profiles with an emphasis on resilience and fewer red flags, you can scan a curated 218 resilient stocks with low risk scores that may suit a more cautious approach.
- If balance sheet strength matters most to you, you can filter for companies on a list of solid balance sheet and fundamentals (203 results) to focus on businesses with room to invest through different cycles.
- Income focused investors who want yields supported by underlying fundamentals can review a hand picked 221 dividend fortresses offering established payout streams.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com