


Eurozone Utility Stocks Built For Steady Dividends Under Pressure
French GDP slipping 0.1% in Q3, inflation pressing toward 3.8% and sovereign yields near 5% all point to a tougher backdrop for Eurozone assets. That sort of mix often rewards investors who pay attention to steadier balance sheets and reliable dividends rather than chasing the hottest story. This article highlights three large cap, dividend-paying stocks that appear most exposed to the latest French shock and explains where the risks and potential resilience may sit.
The three stocks below are just a sample of what this theme can look like in practice. The full screen surfaced 34 more large cap Eurozone dividend payers with equally compelling stories that are not covered here.
If you want to go straight to the source and identify, filter and analyze potential high conviction ideas in this defensive income basket, head into the Defensive, Dividend-Paying Large Caps in the Eurozone screener.
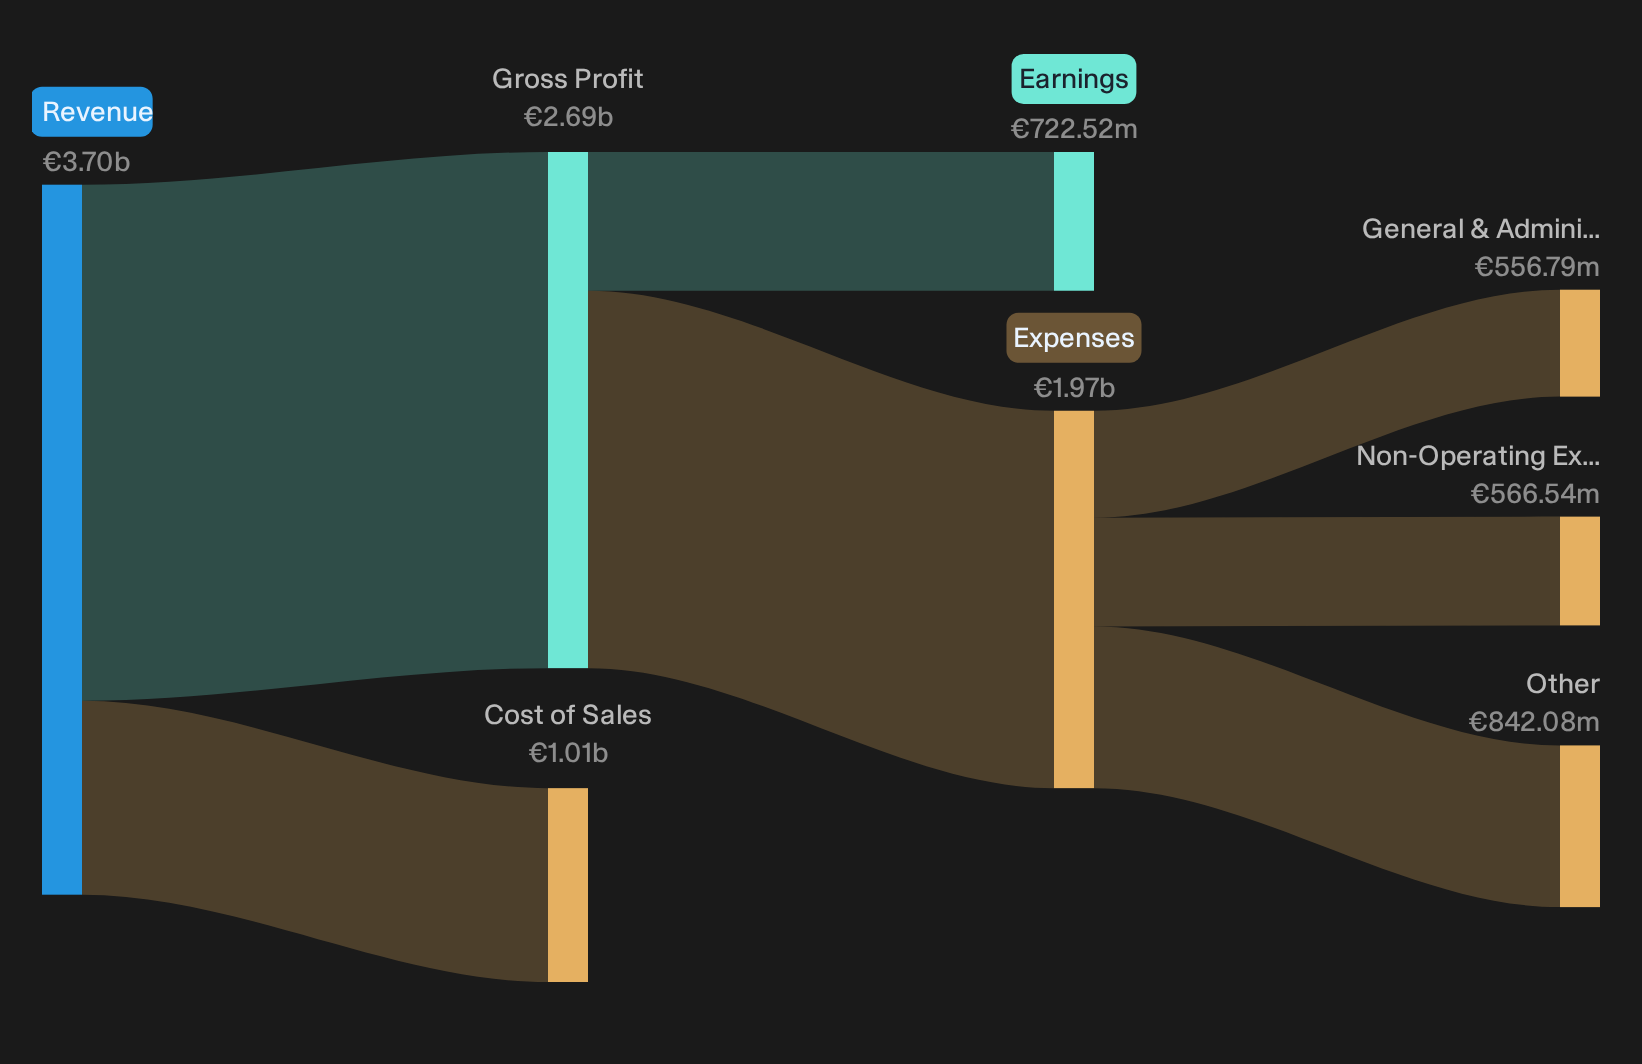
Italgas (BIT:IG)
Overview: Italgas operates regulated gas distribution networks and related water and energy efficiency services across Italy, Greece and other EU markets. This makes it a classic Eurozone defensive income utility.
Market Cap: €9.1b
Italgas illustrates why regulated utilities often feature in a defensive dividend screen, with relatively visible cash flows and income potential that can appeal when growth stories feel fragile.
"The multi decade shift from fossil gas to biomethane, hydrogen and synthetic methane, backed by REPowerEU and rapidly expanding biomethane projects and reverse flow investments, positions Italgas as a key enabler of renewable molecules."
The key variable for Italgas is how one emerging pressure eventually flows through into margins, cash generation and dividend headroom.
That pressure point is exactly what the full narrative for Italgas unpacks, revealing where regulatory shifts, capex cycles and income ambitions could be quietly decoupling.
VERBUND (WBAG:VER)
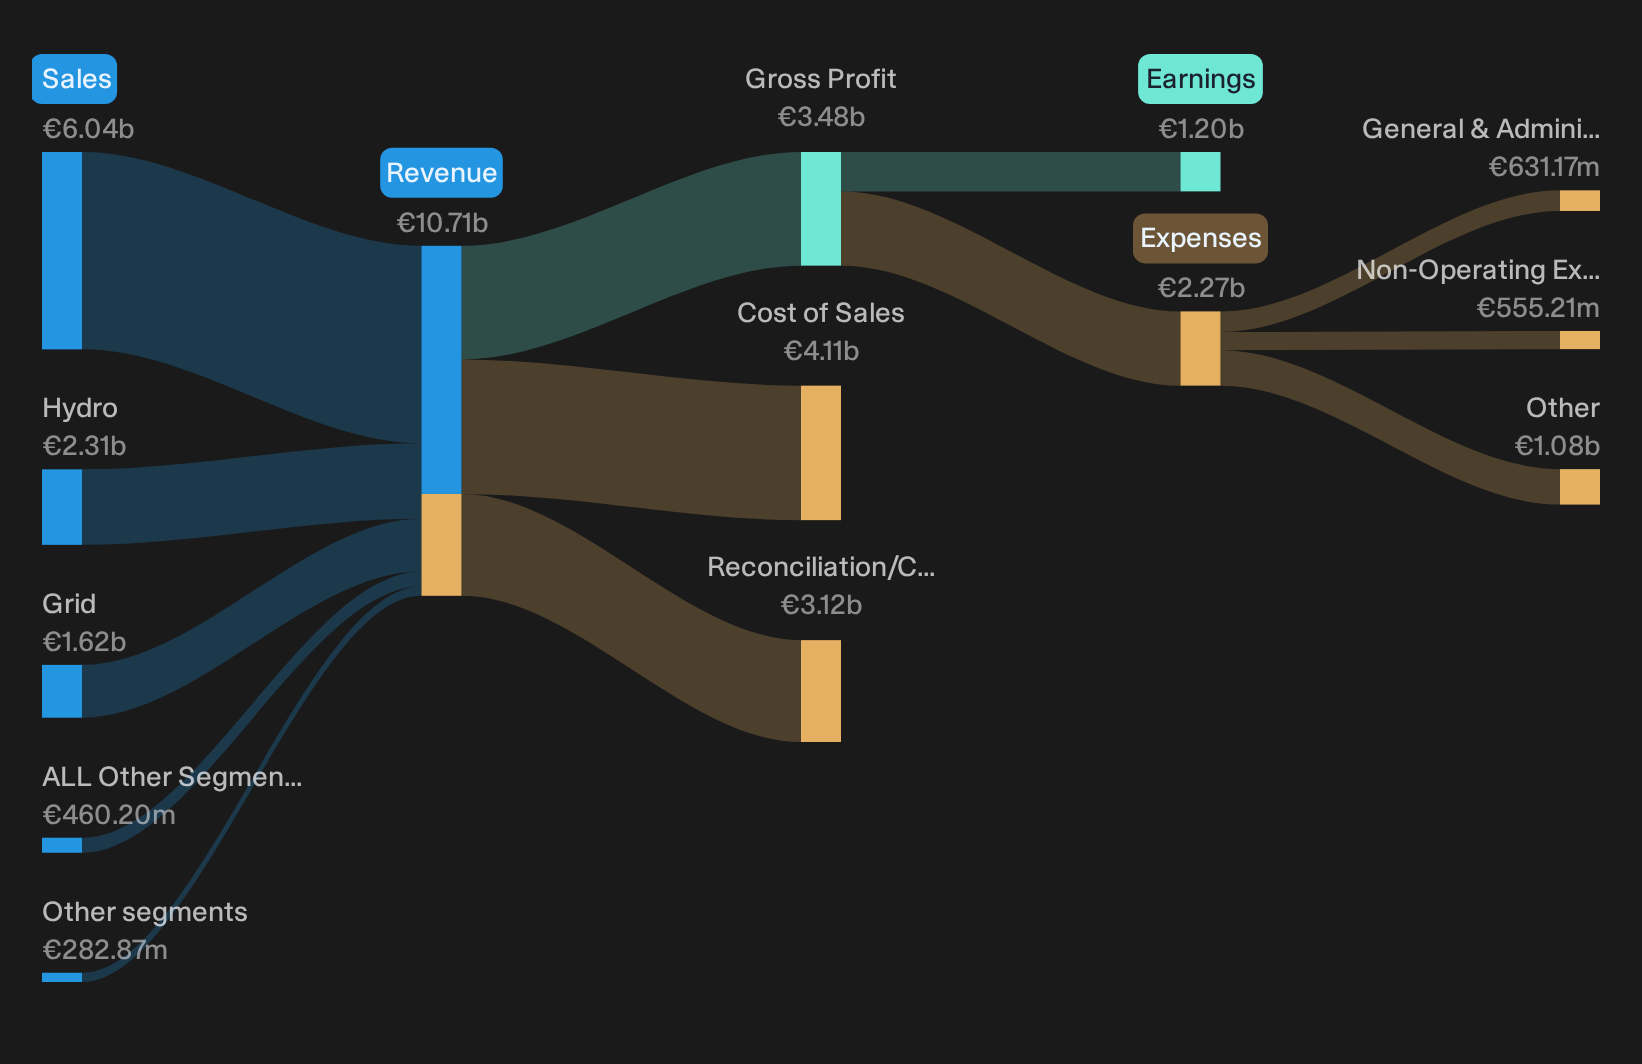
Overview: VERBUND is a major Austrian utility that generates and sells electricity across Europe, anchored in hydropower with growing renewables and storage.
Operations: VERBUND earns €6.0b from Sales, €2.3b from Hydro, €1.6b from Grid and €263 million from New Renewables across Austria and abroad.
Market Cap: €24.1b
VERBUND fits this Eurozone defensive income screen as a large regulated utility. Its mix of hydro generation and storage gives income-oriented investors exposure to relatively more predictable cash flows when cyclical sectors feel fragile.
"The planned execution of VERBUND’s 300 MW pumped storage project in Germany points to future additional hydropower based storage capacity that can be used to serve demand for flexible renewable supply and support revenue over time."
What really matters now is how one quiet shift in funding and payout discipline shapes the reliability of those future distributions.
That funding and payout tension is exactly what the full narrative for VERBUND unpacks, revealing where VERBUND’s storage build out could quietly accelerate or cap future income resilience.
Endesa (BME:ELE)
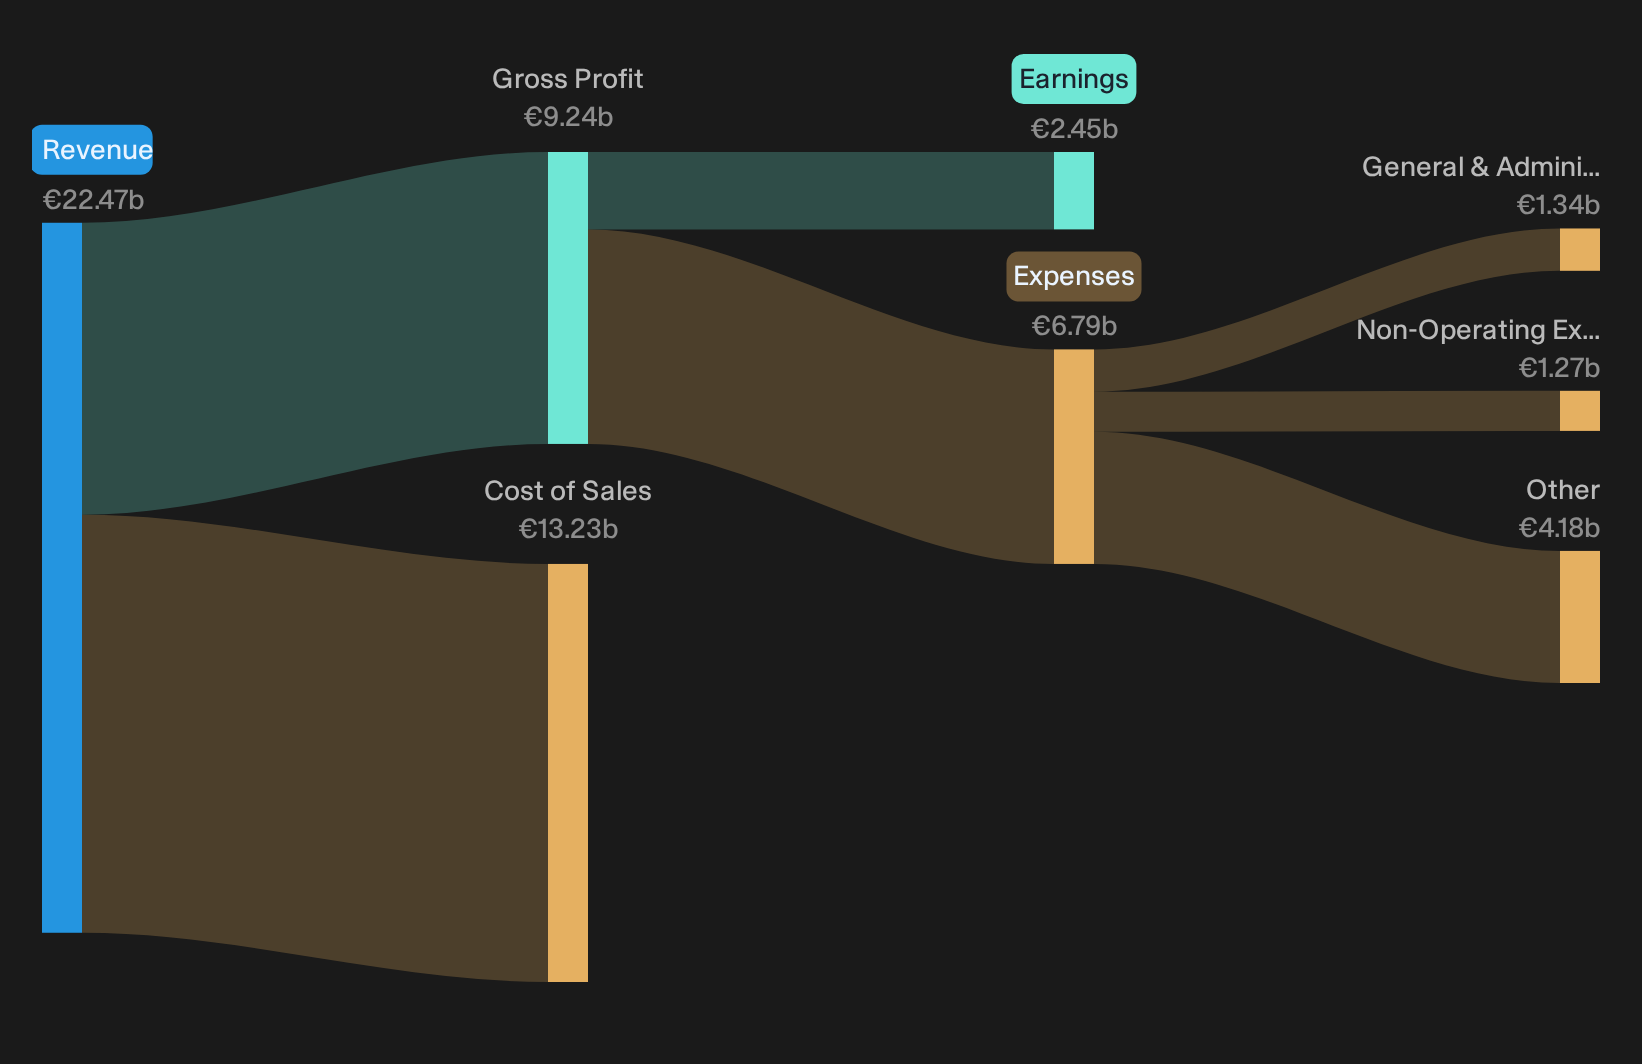
Overview: Endesa is a Spanish electricity utility that generates power, runs distribution networks and supplies energy to households and businesses across Europe.
Market Cap: €44.5b
Endesa fits this defensive dividend screen as a large Eurozone utility where much of the earnings base is regulated or contracted. This can appeal when investors want more predictable income as growth expectations cool.
"Large grid capacity constraints in Spain, with Endesa reporting around 94% of its network nodes saturated and only 18% of new demand requests granted so far, point to a multi year need for reinforcement investment. Management plans to address this with €5.5b of network CapEx that is largely added to the regulated asset base and is expected to support EBITDA and net income."
The real swing factor is how one unresolved regulatory decision shapes the balance between future returns, payout capacity and Endesa’s defensive profile.
That regulatory call is exactly what the full narrative for Endesa tackles head on, showing where grid upgrades could quietly accelerate Endesa’s income profile.
Seeking Alternatives Before Momentum Flies
Fresh opportunities rarely stay under the radar for long. Once momentum builds, entry points get caught in the rush and pricing power drops fast, so it can be useful to look early.
- Spot income workhorses built on sturdy cash generation and cleaner balance sheets through the curated list of solid balance sheet and fundamentals (203 results) while that funding strength still feels underappreciated by the crowd.
- Front run potential AI infrastructure spending trends by scanning 54 AI infrastructure stocks before data center and chip demand stories attract broader attention.
- Track the backbone of electrification using 39 power grid technology and infrastructure stocks while these grid and equipment players are still often compared with utilities rather than higher momentum infrastructure names.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com