


Bayer (XTRA:BAYN) Stock Stays Undervalued On Fresh NUBEQA Trial News
Bayer has delivered a sharp share price recovery over the past year, and that kind of move naturally raises a question for you as an investor. Is the current valuation of the stock still grounded in what the group is generating through its sales base, or has the market moved ahead of the revenue story?
- Bayer shares are up 88.2% over the past year, which puts a lot of weight on whether the present market value can be explained by the scale and quality of its sales.
- Recent developments around oncology medicines, gene therapy work and litigation progress may support different expectations for future revenue mix, pricing power and long term cash generation from Bayer's product portfolio.
- There is a second opinion on Bayer worth weighing. See what analysts think Bayer's shares could be worth.
The stock's next move may depend on whether today's share price is appropriately aligned with what Bayer is currently producing in sales.
If you are considering whether Bayer's 88.2% one-year rebound still aligns with its sales performance, it can help to compare that situation with 199 high quality undervalued stocks.
Is Bayer Still Cheap on Sales?
For Bayer, the P/S ratio is a straightforward way to see what the market is paying for each euro of current revenue, without getting tangled up in near term earnings swings.
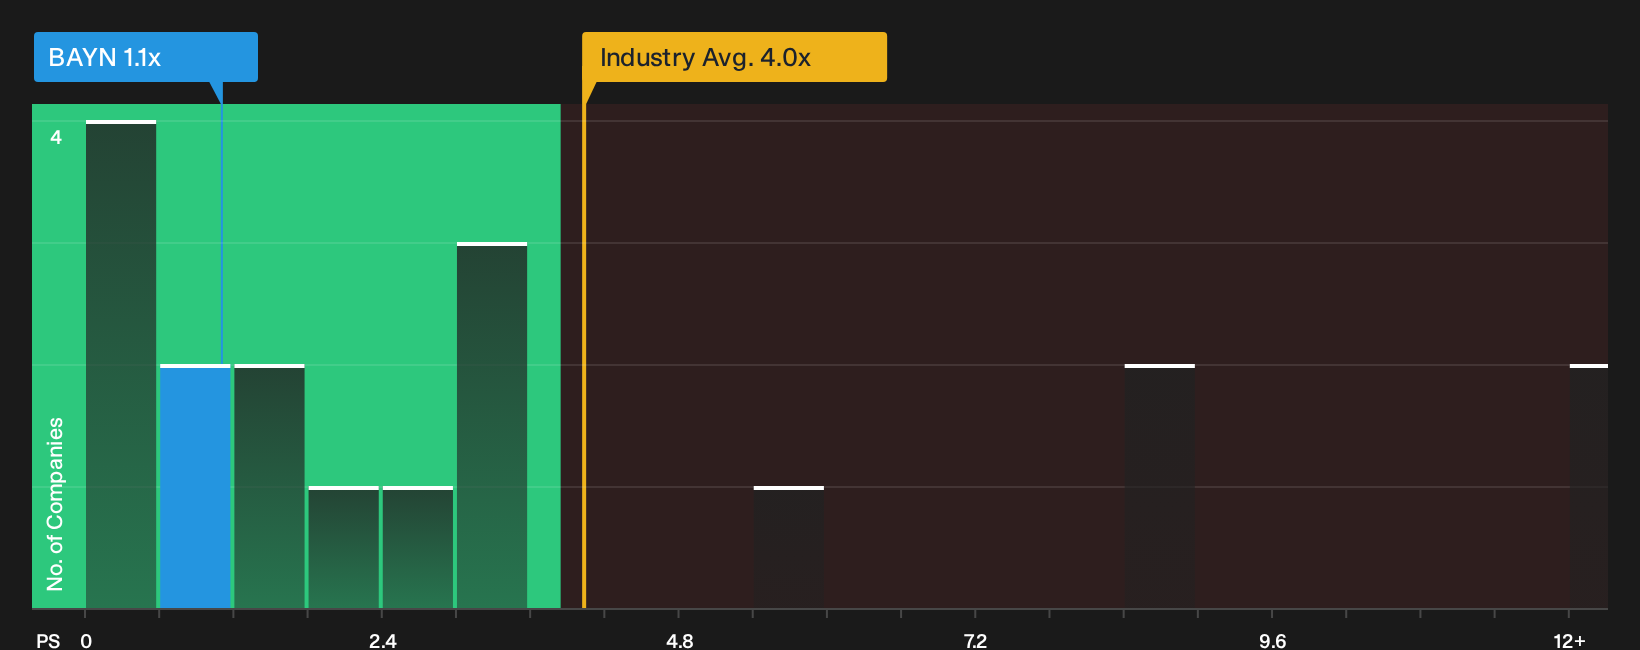
On this measure, Bayer trades on a P/S of 1.1x, which is below both the Pharmaceuticals industry average of 2.5x and the peer group average of 4.0x. The tailored fair multiple implied by its fundamentals sits above the current 1.1x level, so the shares screen as undervalued on this framework. Because the recent NUBEQA prostate cancer data gives the pipeline more visibility in oncology, a discounted P/S ratio suggests investors are still pricing Bayer cautiously relative to what comparable drug makers command.
The gap between the present P/S level and the fair benchmark points to a market that is valuing Bayer's revenue base at a lower rate than similar pharmaceutical groups, which you may or may not agree with after weighing its litigation track record, pipeline mix and crop science exposure. Explore the numbers behind Bayer's P/S valuation.
The Bayer Narrative: What Would Justify Today's Price?
Narratives pick up where this valuation puzzle leaves off by spelling out what kind of future for Bayer's growth, margins and earnings would need to play out for the share price to look meaningfully higher or lower than it is today, all hosted on Simply Wall St's Community page. Each one is framed as a specific, testable view of Bayer's business rather than a one off snapshot so you can see how the logic holds up over time.
Community views on Bayer are split between those who see execution upside and those who think the recent rebound already prices in a lot of that progress.
Bull case: 13% undervalued
"Execution of Bayer’s 2024 to 2029 Crop Science framework, which targets more than €1b of EBITDA improvements and over €1.5b of working capital cash release…"
Discover why this Narrative puts Bayer at 13% undervalued.
Bear case: 26% overvalued
"Os litígios relacionados ao glifosato (Roundup) continuam a ser um fardo significativo nas finanças da Bayer, com impactos que se estendem a 2026…"
Explore why this Narrative puts Bayer at 26% overvalued.
One more Bayer angle that could reshape your view
Sales, valuation and community debates tell only part of the story, because professional research teams also map out where they expect Bayer to be in a few years. That gap or alignment with today's pricing is worth checking. Explore where analysts expect Bayer to be in a few years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com