


Is NMI Holdings (NMIH) Stock Priced Right After An 88% Run?
NMI Holdings has delivered a strong share price run in recent years, which naturally puts the focus on whether the current quote still lines up with what the business is earning. With the stock now well above where it traded five years ago, the key issue for you is how much of those earnings are already reflected in today's valuation.
- Over the past 5 years the stock has returned 88.1%. This raises the question of how much future earnings strength the market is already pricing in.
- The insurer's model, which converts mortgage credit exposure into fee and premium income, means profitability and capital discipline can heavily influence how much investors are willing to pay for each dollar of earnings.
- Your read on NMI Holdings is one view; the desks covering it have another. See what analysts think NMI Holdings's shares could be worth.
The issue now is whether today's NMI Holdings share price is justified by its earnings when set against the Fair Ratio benchmark.
If you want to apply this same earnings question across a wider field, compare NMI Holdings with 29 high quality undervalued stocks.
Does NMI Holdings Look Undervalued on Earnings?
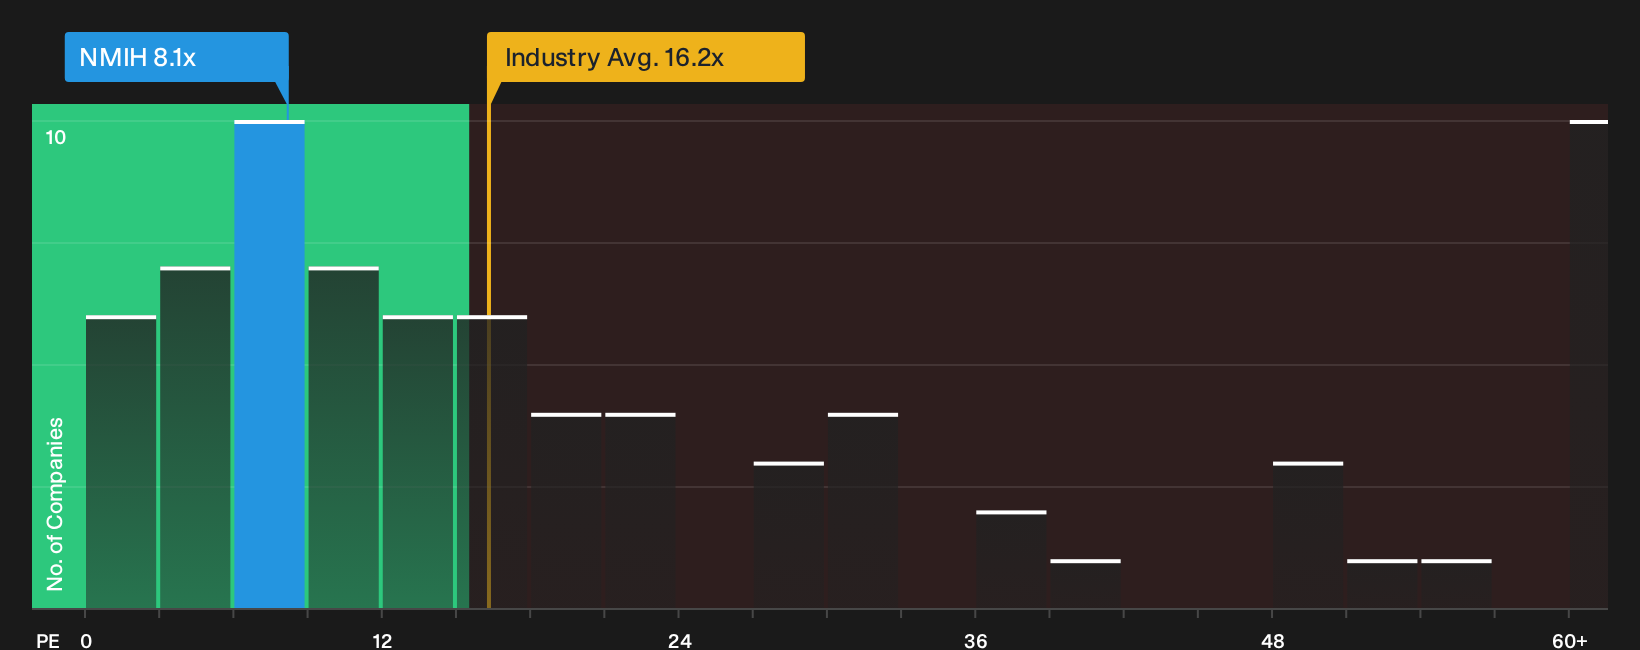
The P/E ratio fits NMI Holdings because earnings are a primary driver of value for a fee based financial business. The stock trades on a P/E of 8.1x, which is below the diversified financial industry average of 16.2x and also under the peer group on 10.4x. On a simple market comparison, the shares change hands at a lower price tag for each dollar of earnings than many similar insurers.
The Fair Ratio, which estimates the P/E that might suit NMI Holdings given its returns on equity, balance sheet profile and analyst earnings expectations, sits above the current market multiple. That points to the shares pricing in a discount to what this tailored yardstick implies, even after the strong long term share price performance already on the board. For a closer read on how wide that gap is and whether it still leaves a margin of safety for your own hurdle rate, compare the live multiple against the Fair Ratio and peers in. Explore the numbers behind NMI Holdings's P/E valuation.
The NMI Holdings Narrative: What Would Justify Today's Price?
NMI Holdings' Simply Wall St Narratives pick up where the P/E and Fair Ratio leave off, spelling out which future paths for growth, margins and earnings would need to play out for the stock to be worth materially more or materially less than today's price. Rather than giving just one headline figure, they lay out the business conditions that number relies on so you can watch over time whether those assumptions keep holding up.
One of the top community narratives on NMI Holdings: 14% undervalued
"The main thing that has to go right is that NMI Holdings maintains its high quality insured portfolio and effective reinsurance and capital management while credit losses normalize..."
Discover why this Narrative puts NMI Holdings at 14% undervalued.
NMI Holdings valuation leaves one more key angle unanswered
You have a snapshot of what NMI Holdings looks like today, but analyst views on where earnings might land a few years from now give a very different lens on the same price tag. Explore where analysts expect NMI Holdings to be in a few years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com